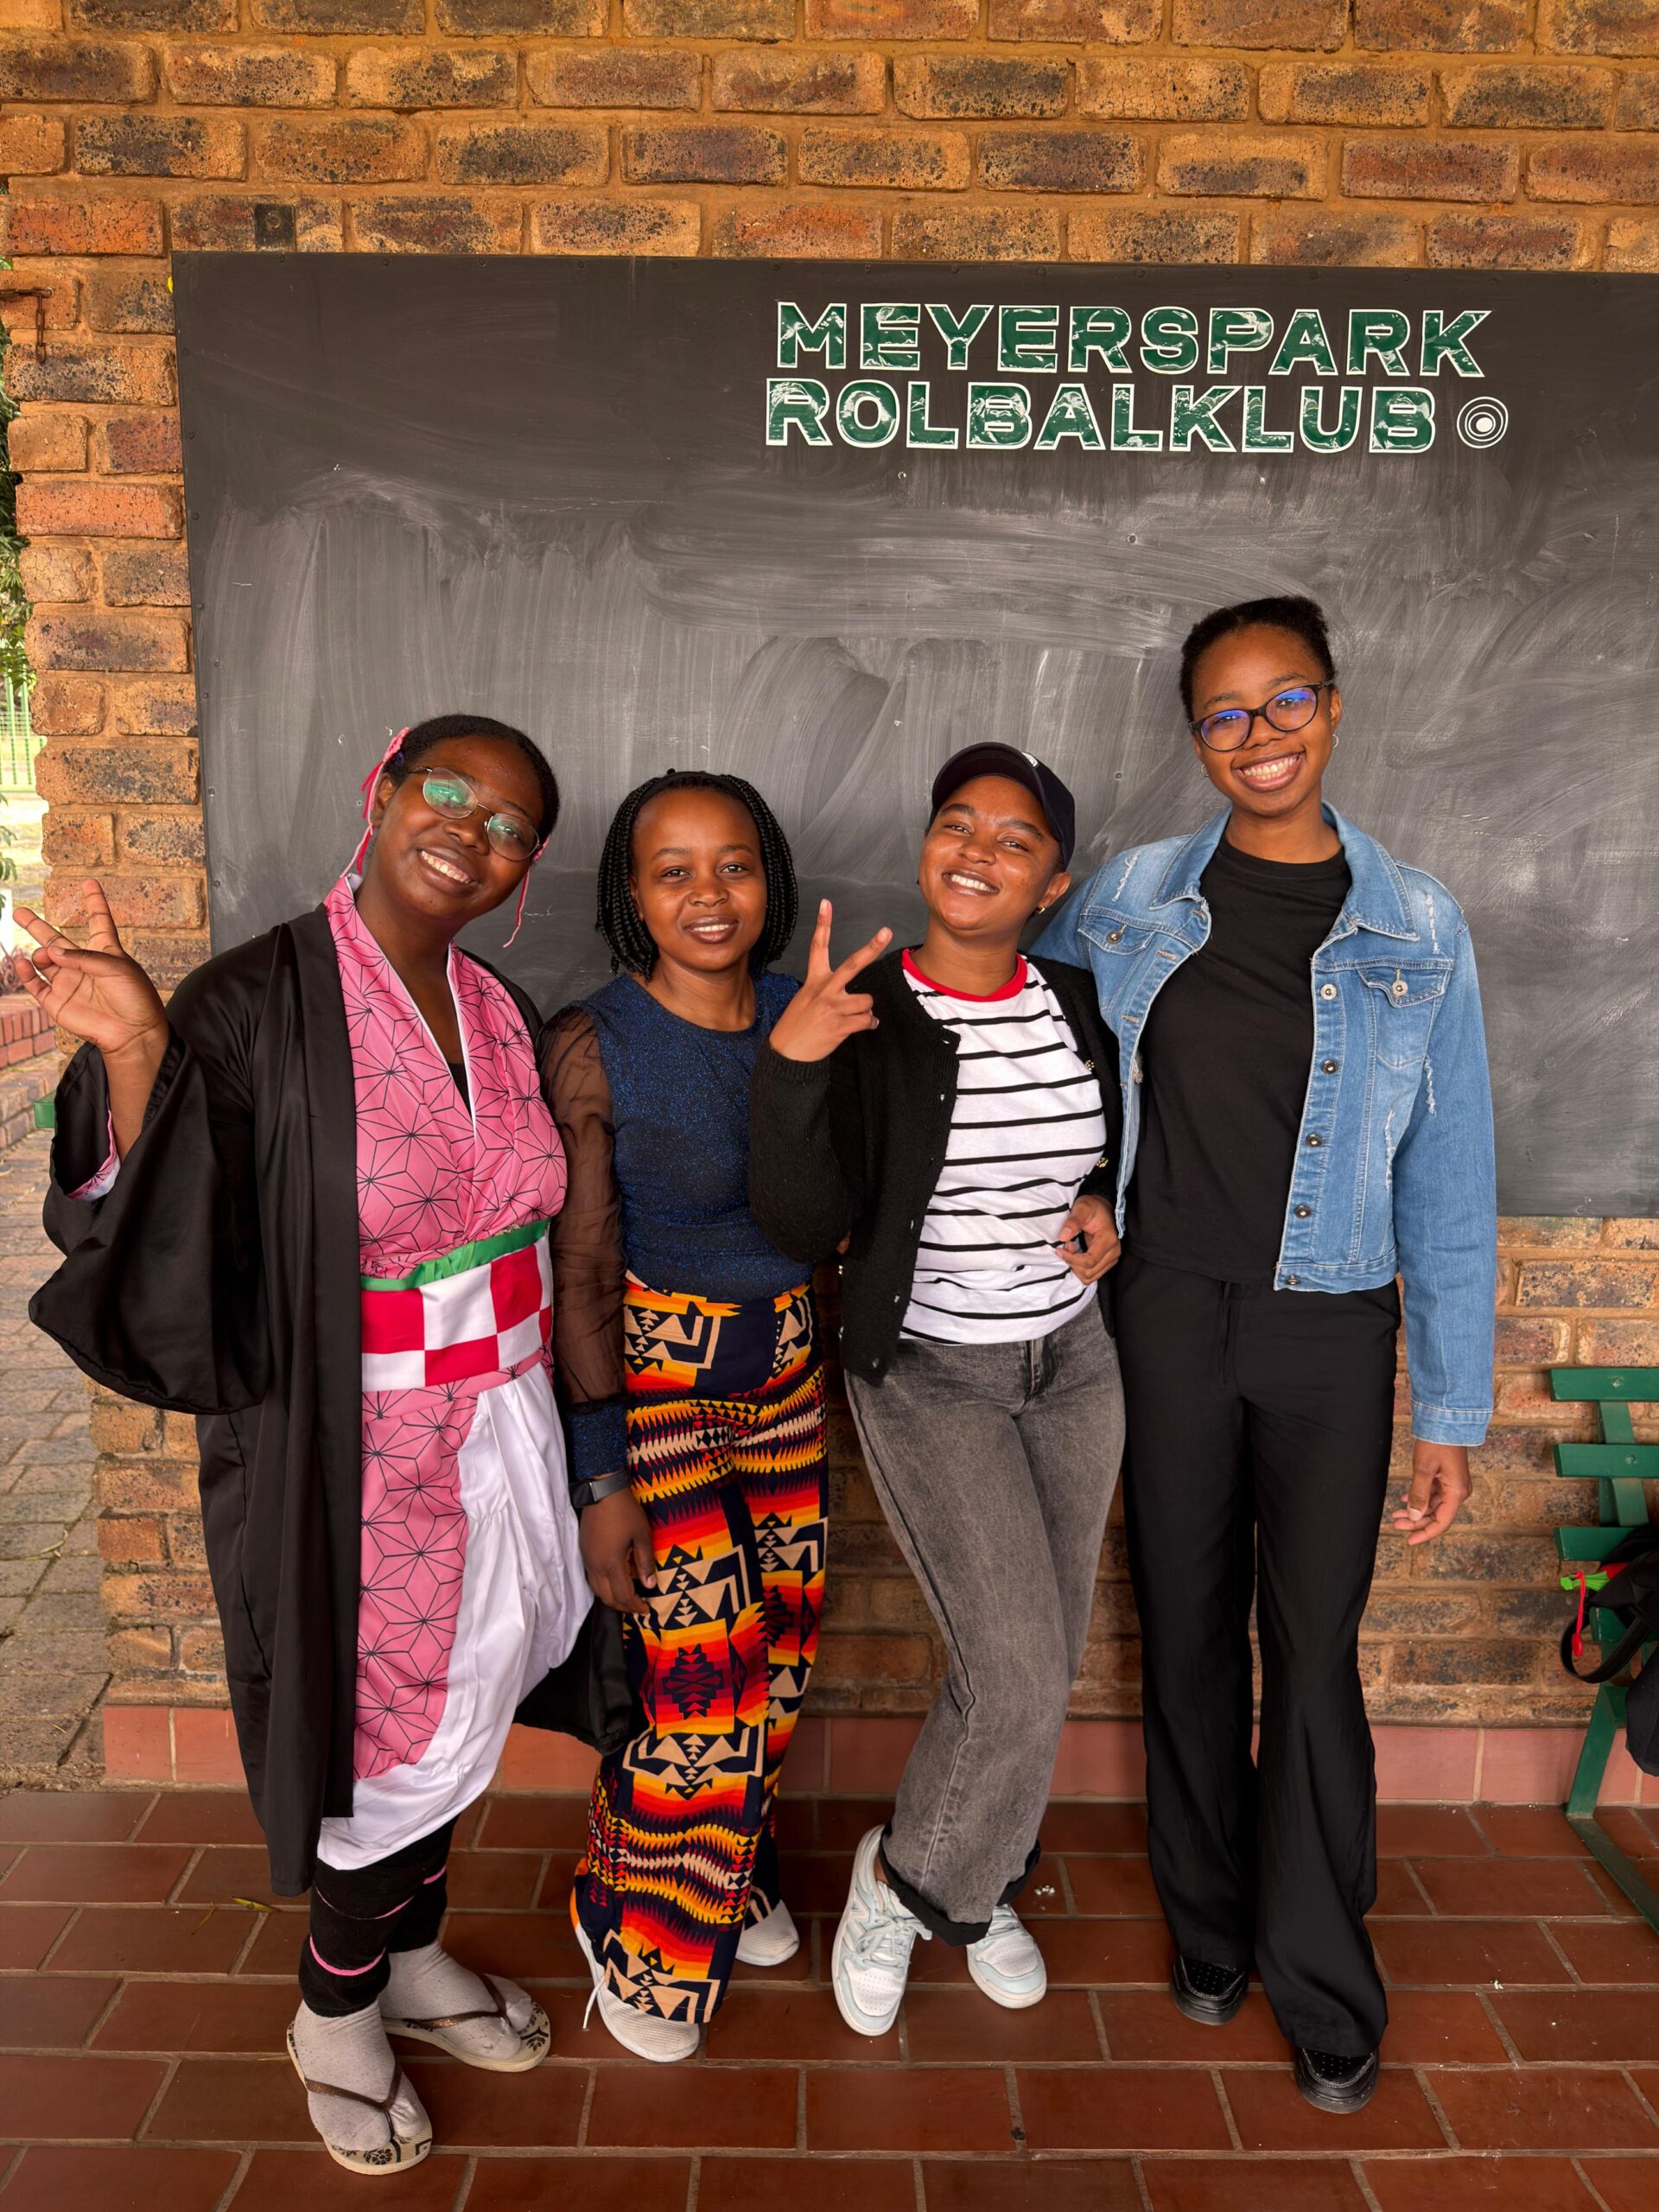News Category: Finance

Powering a Sustainable Future

Powering a Sustainable Future: LOGISTA extends its congratulations to the role-players in reaching this a Major Solar Energy Milestone

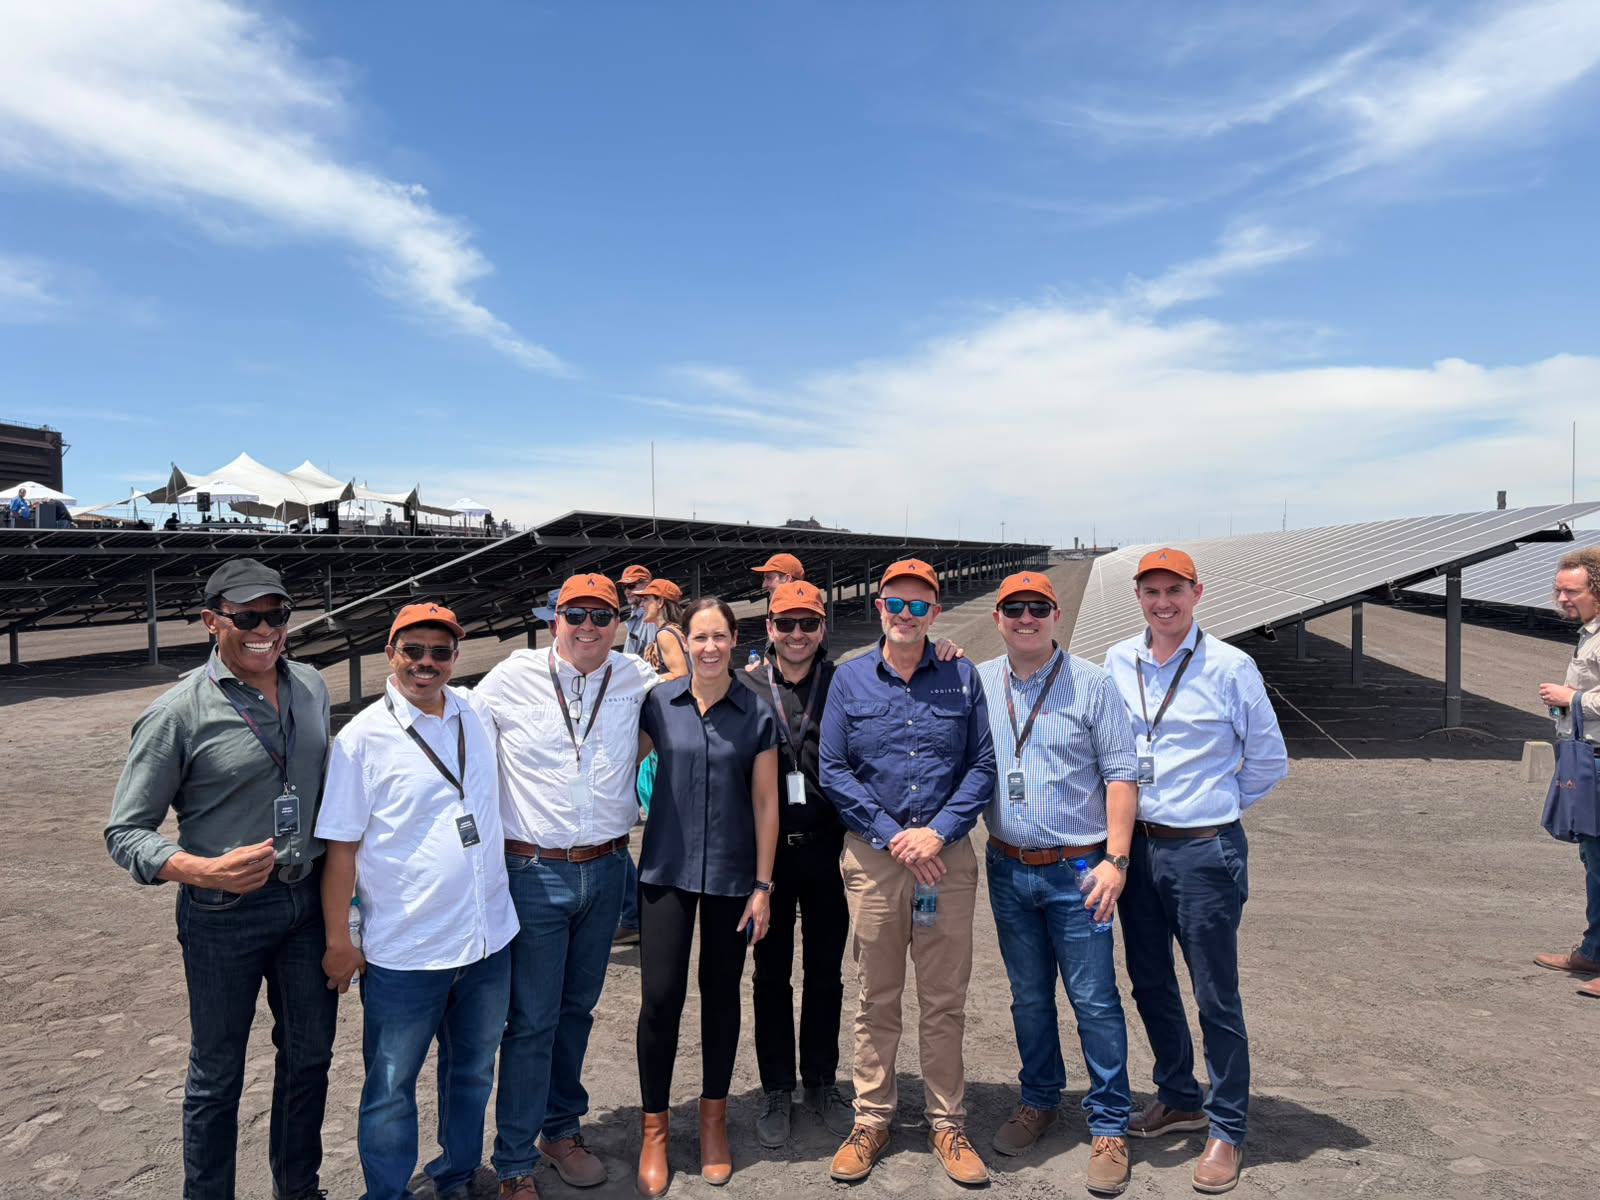
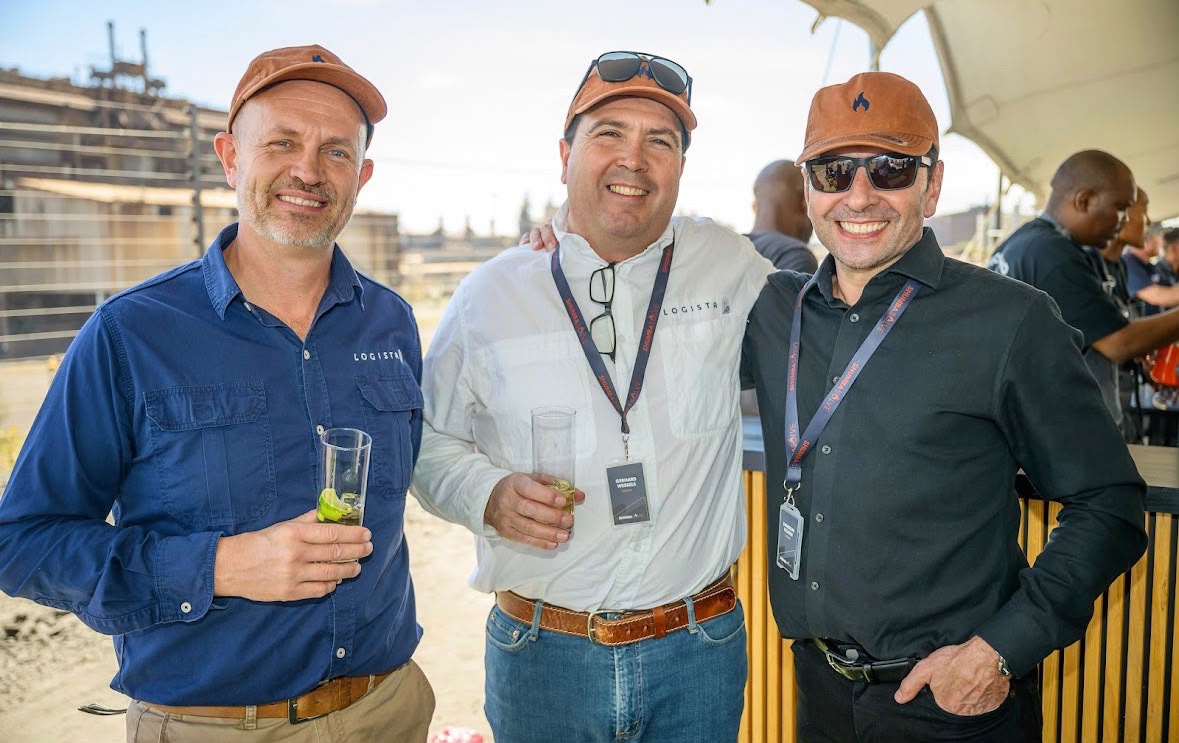
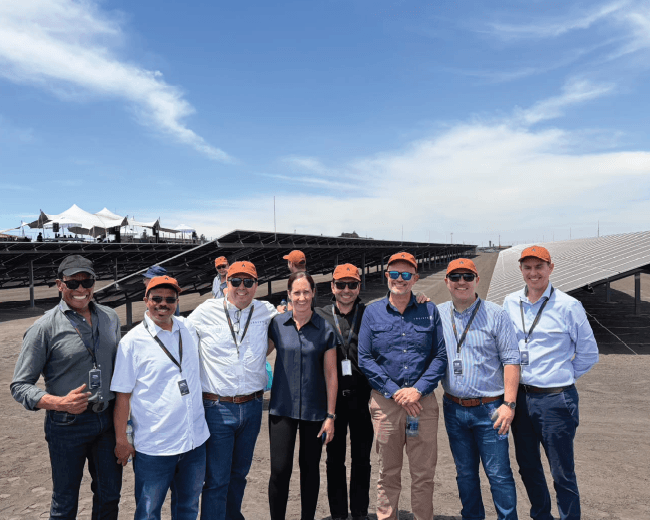
LOGISTA was proud to attend the recent opening of a 6.5 MW solar power plant at the Highveld Industrial Plant, marking an exciting milestone in South Africa’s ongoing transition towards cleaner, more sustainable energy solutions.

The event brought together representatives from Highveld Industrial Plant (HIP), the Moolman Group, Fledge Capital and several other key stakeholders to celebrate the successful development of this renewable energy project. The occasion highlighted the importance of collaboration, forward-thinking investment and a shared commitment to building a more sustainable future.

As South African businesses continue to navigate rising energy costs and the need for reliable electricity, investments in renewable energy are becoming increasingly important. Solar installations of this scale demonstrate how the private sector can take meaningful steps towards greater energy efficiency, reduced environmental impact and long-term operational sustainability.

Projects such as these also reflect the growing role of renewable energy in strengthening South Africa’s industrial landscape. By embracing alternative energy solutions, businesses can improve their resilience, support sustainable economic development and contribute to a more secure energy future.

Pedalling for a Purpose

Pedalling for a Purpose: LOGISTA Supports Beeld-Kinderfonds

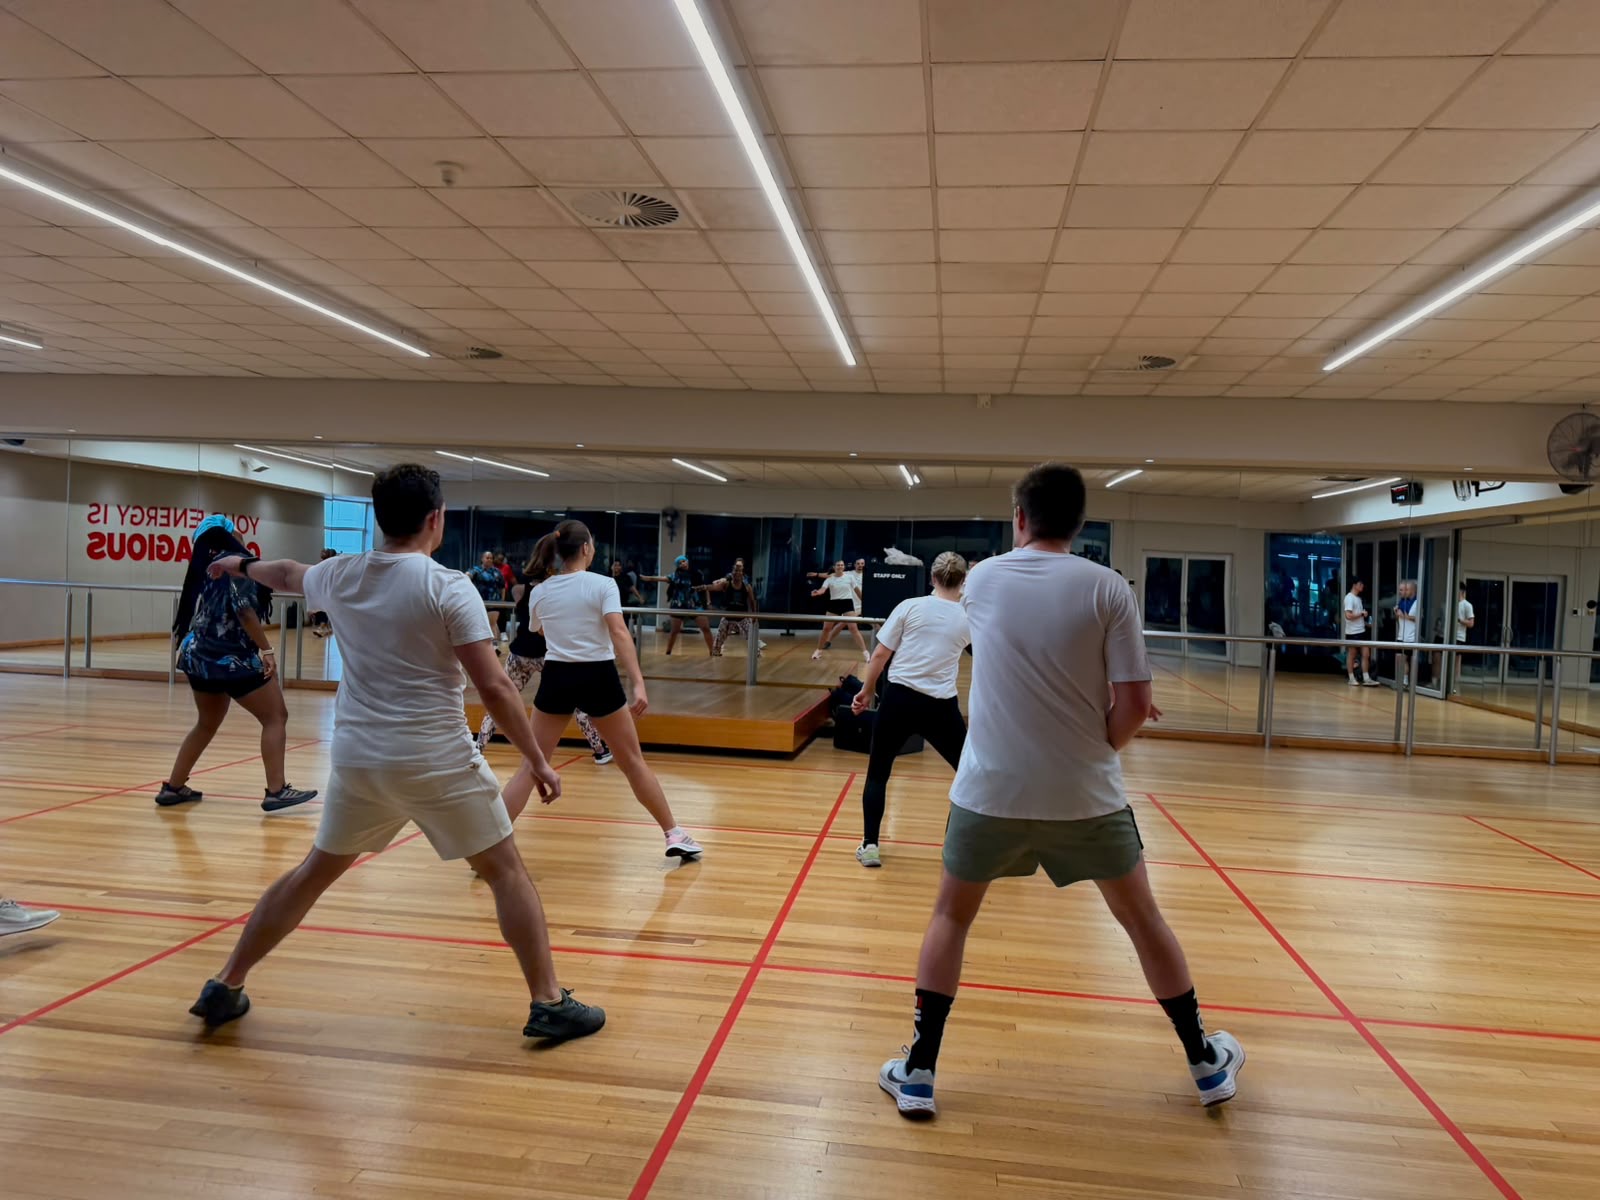
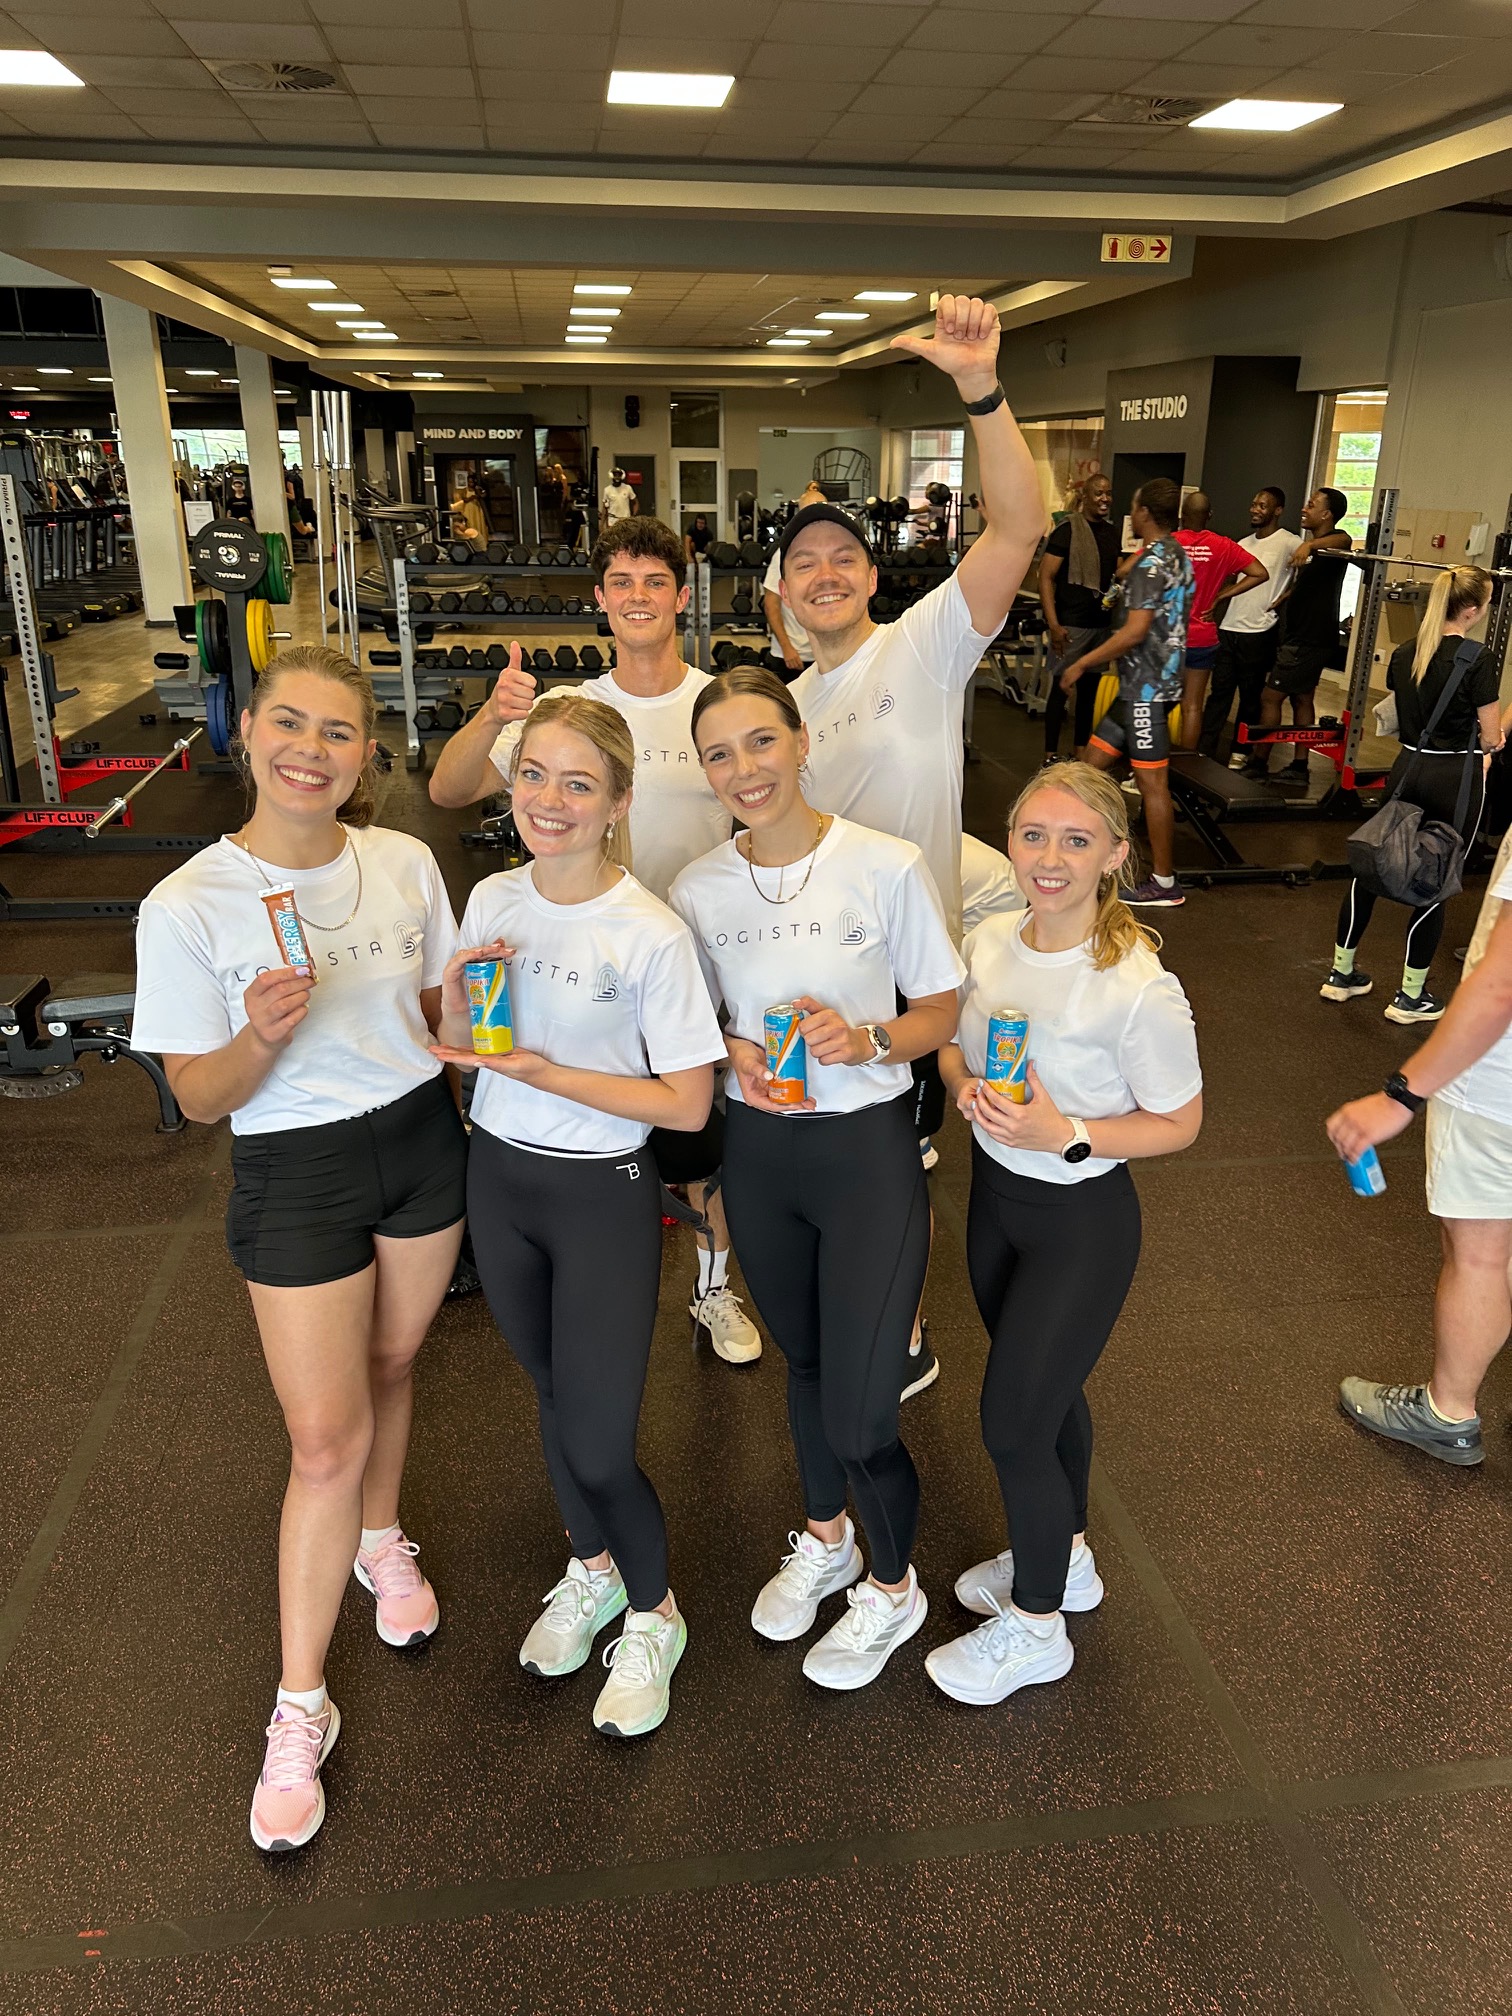
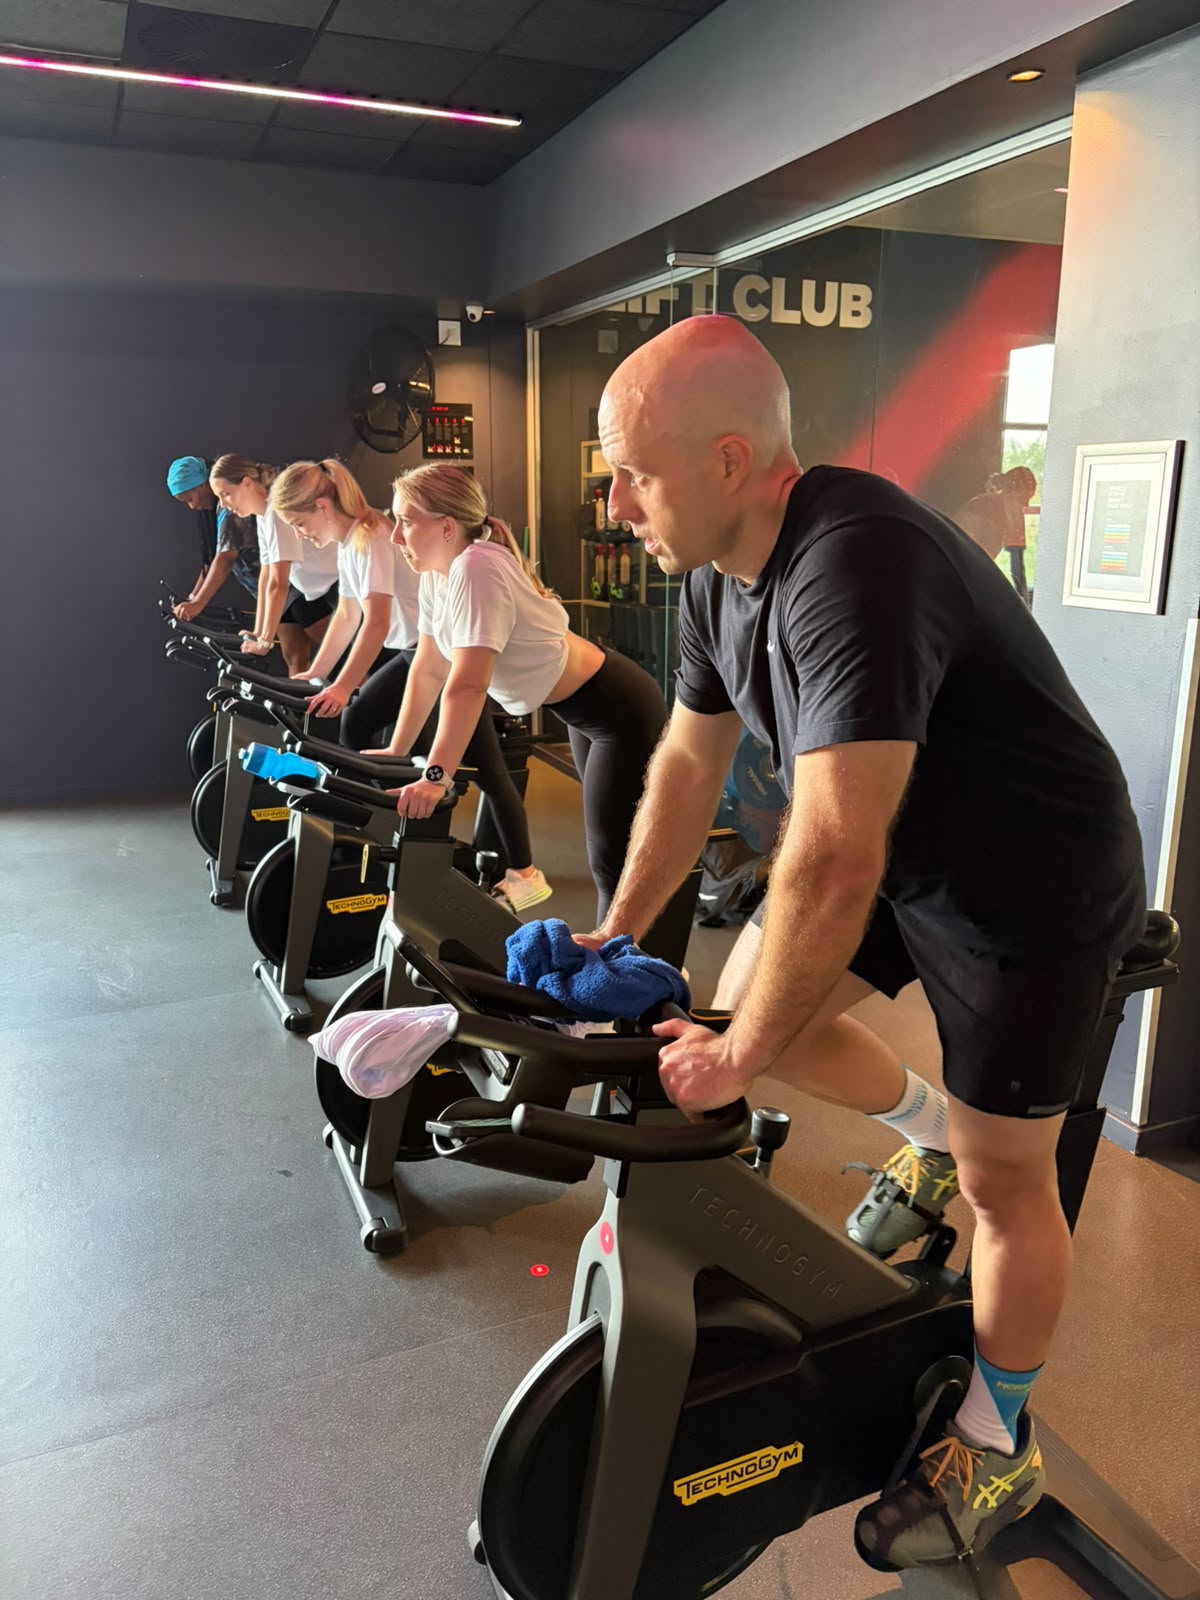
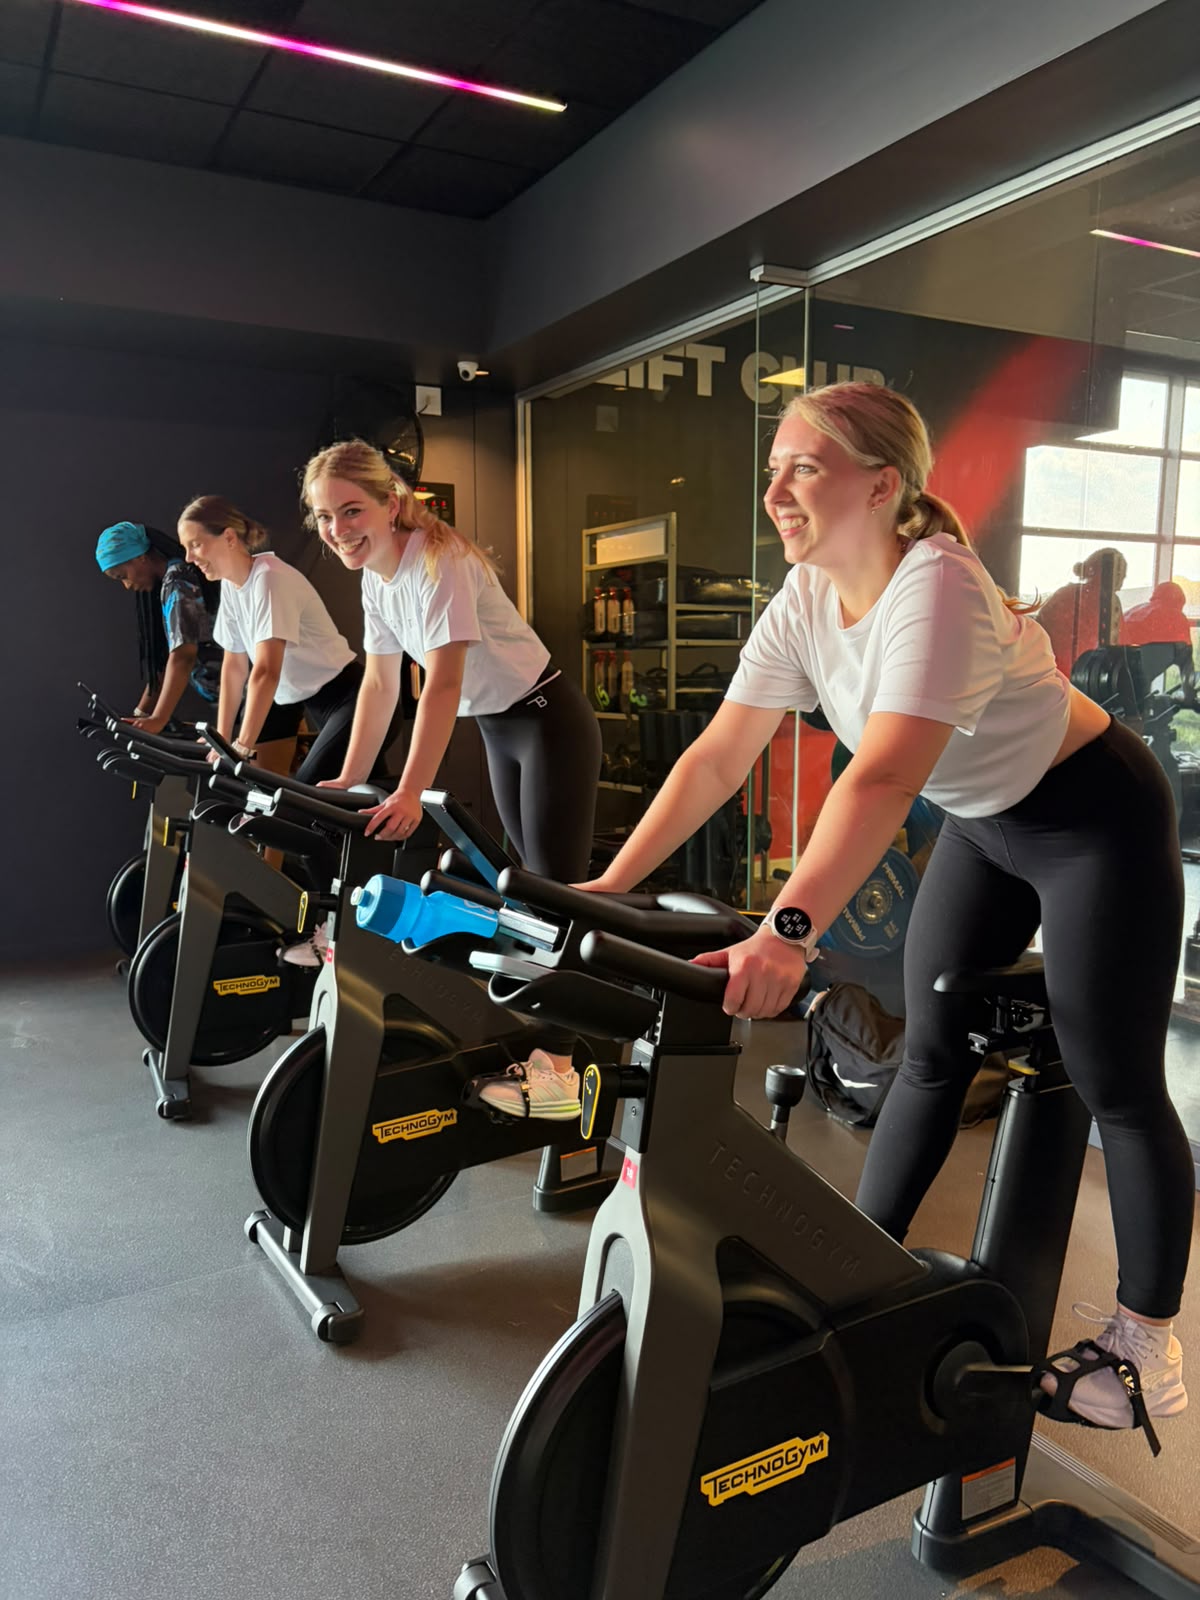
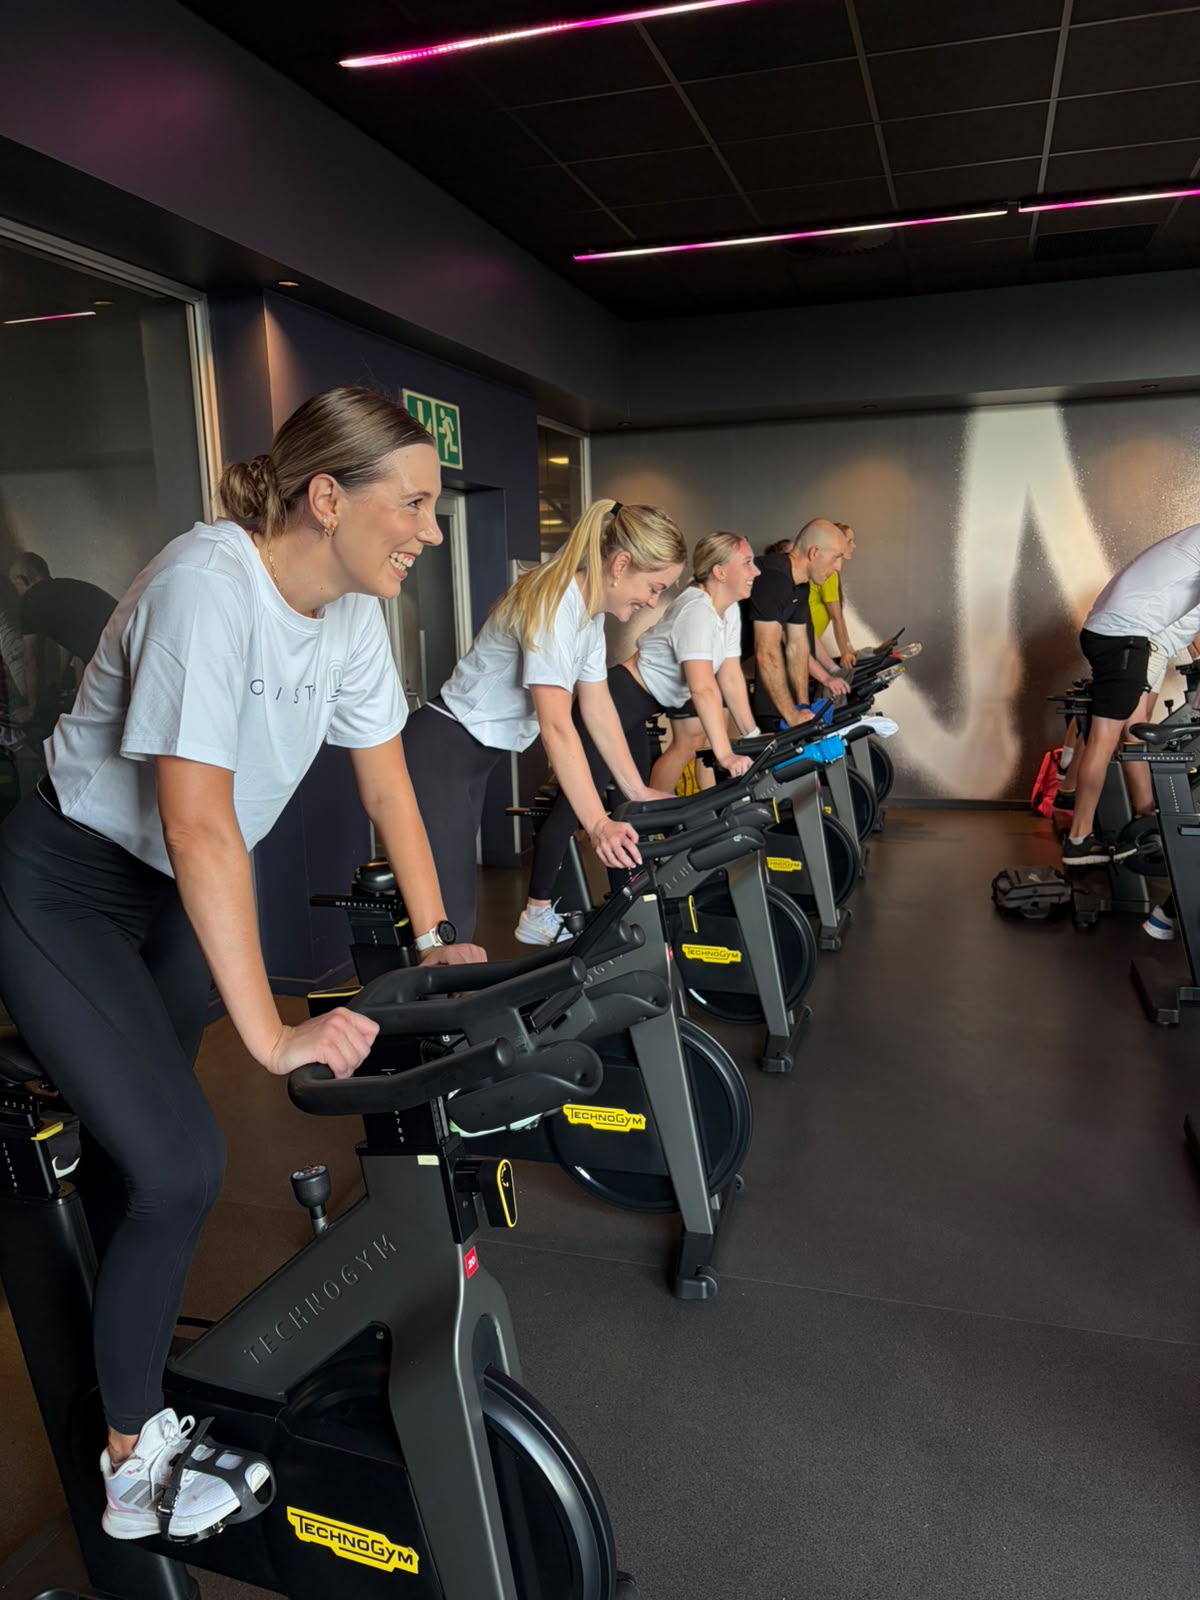
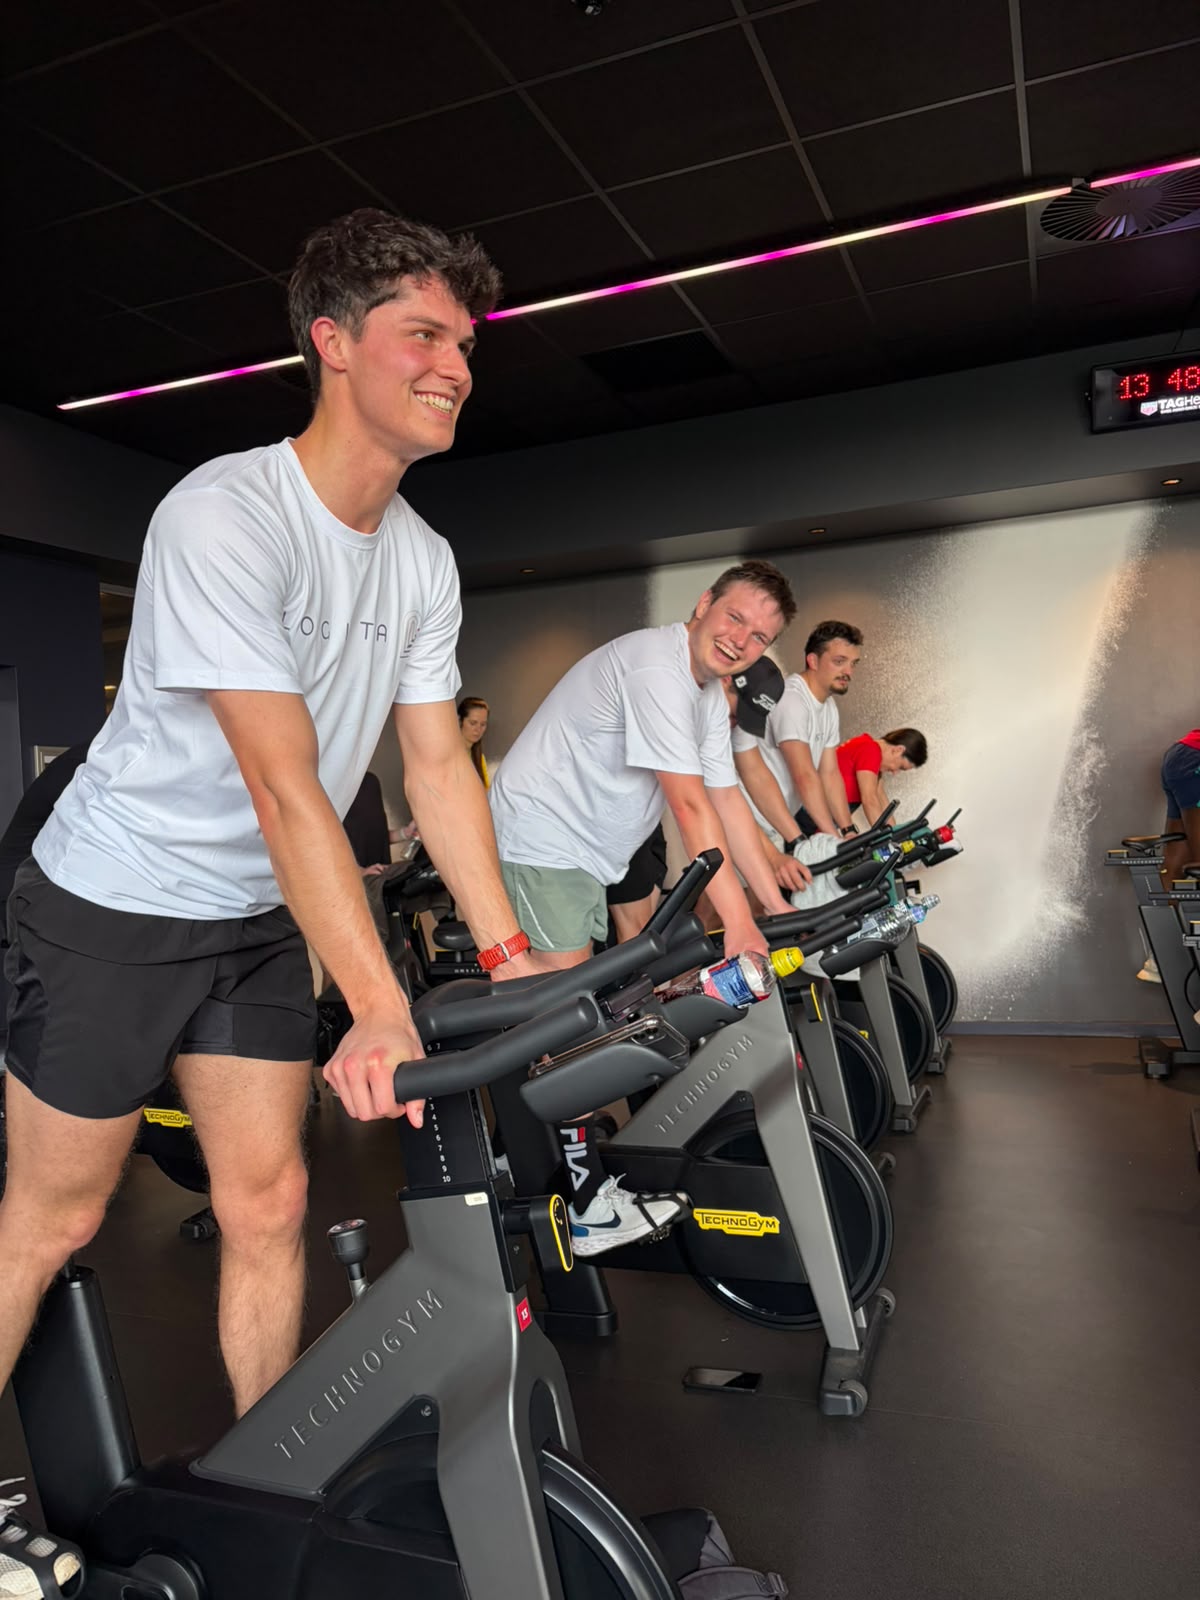
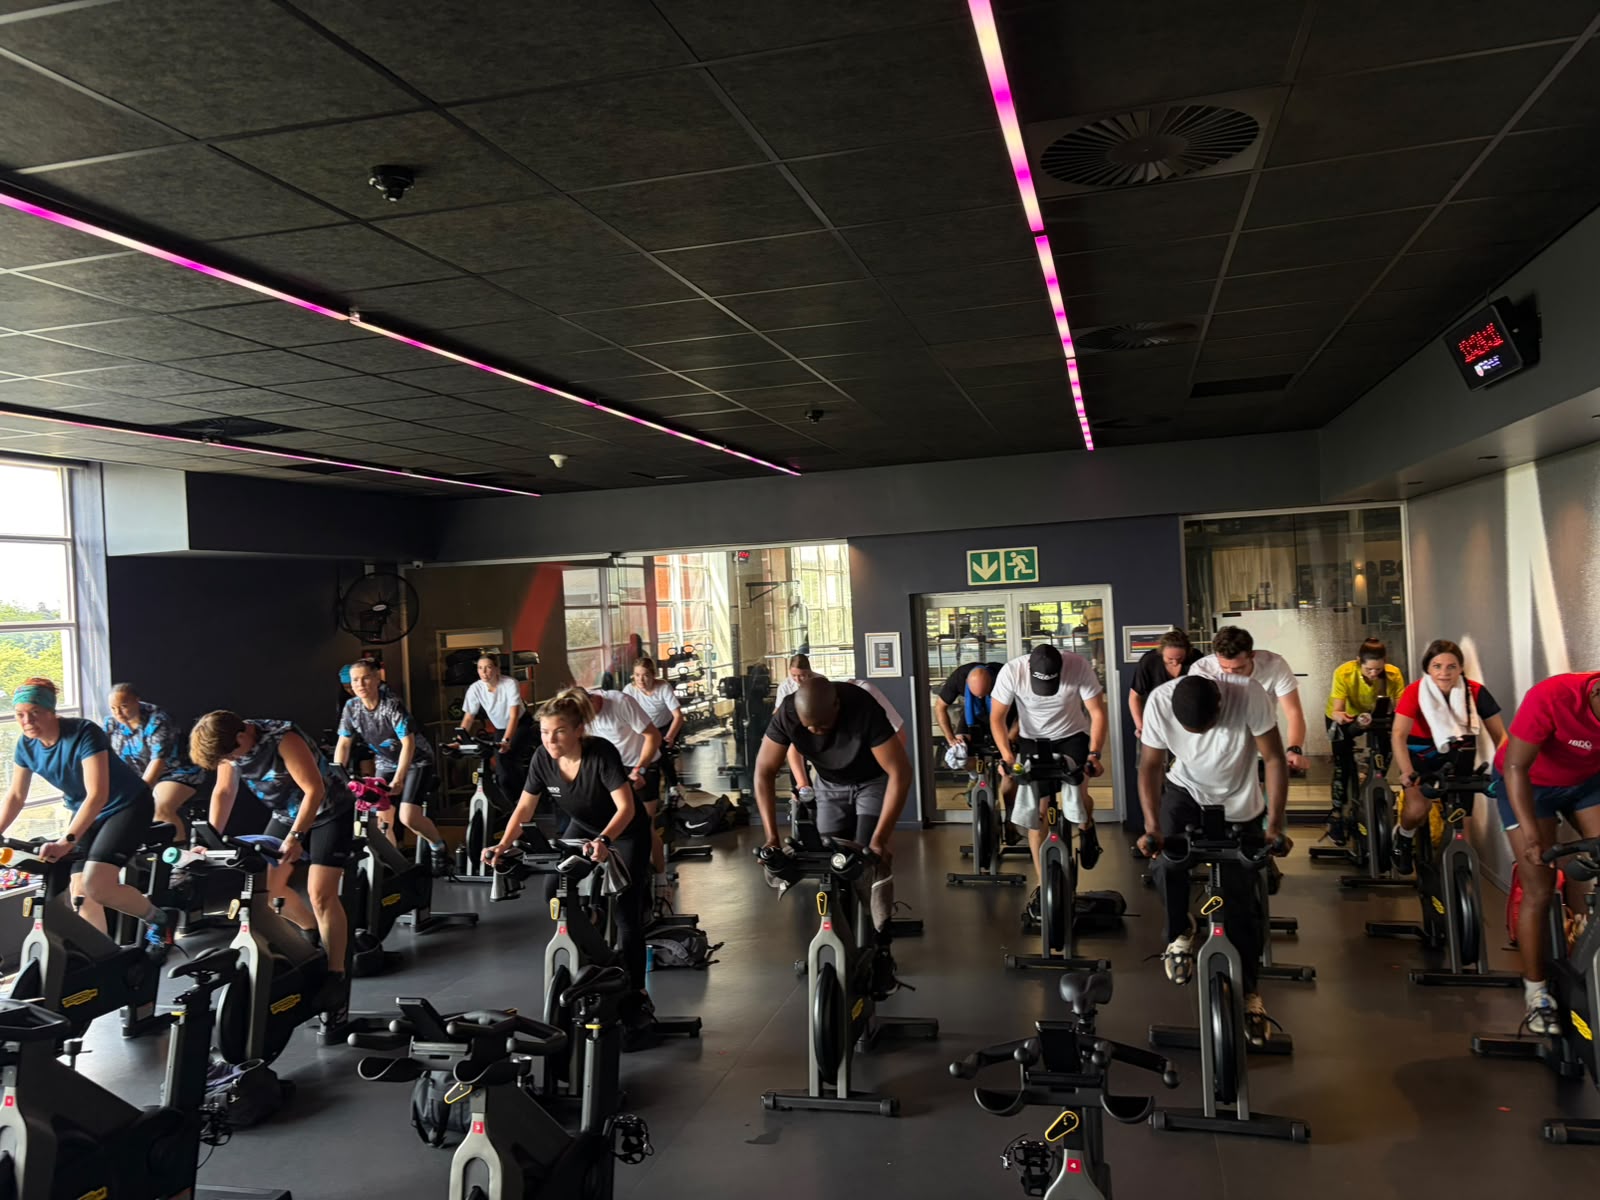
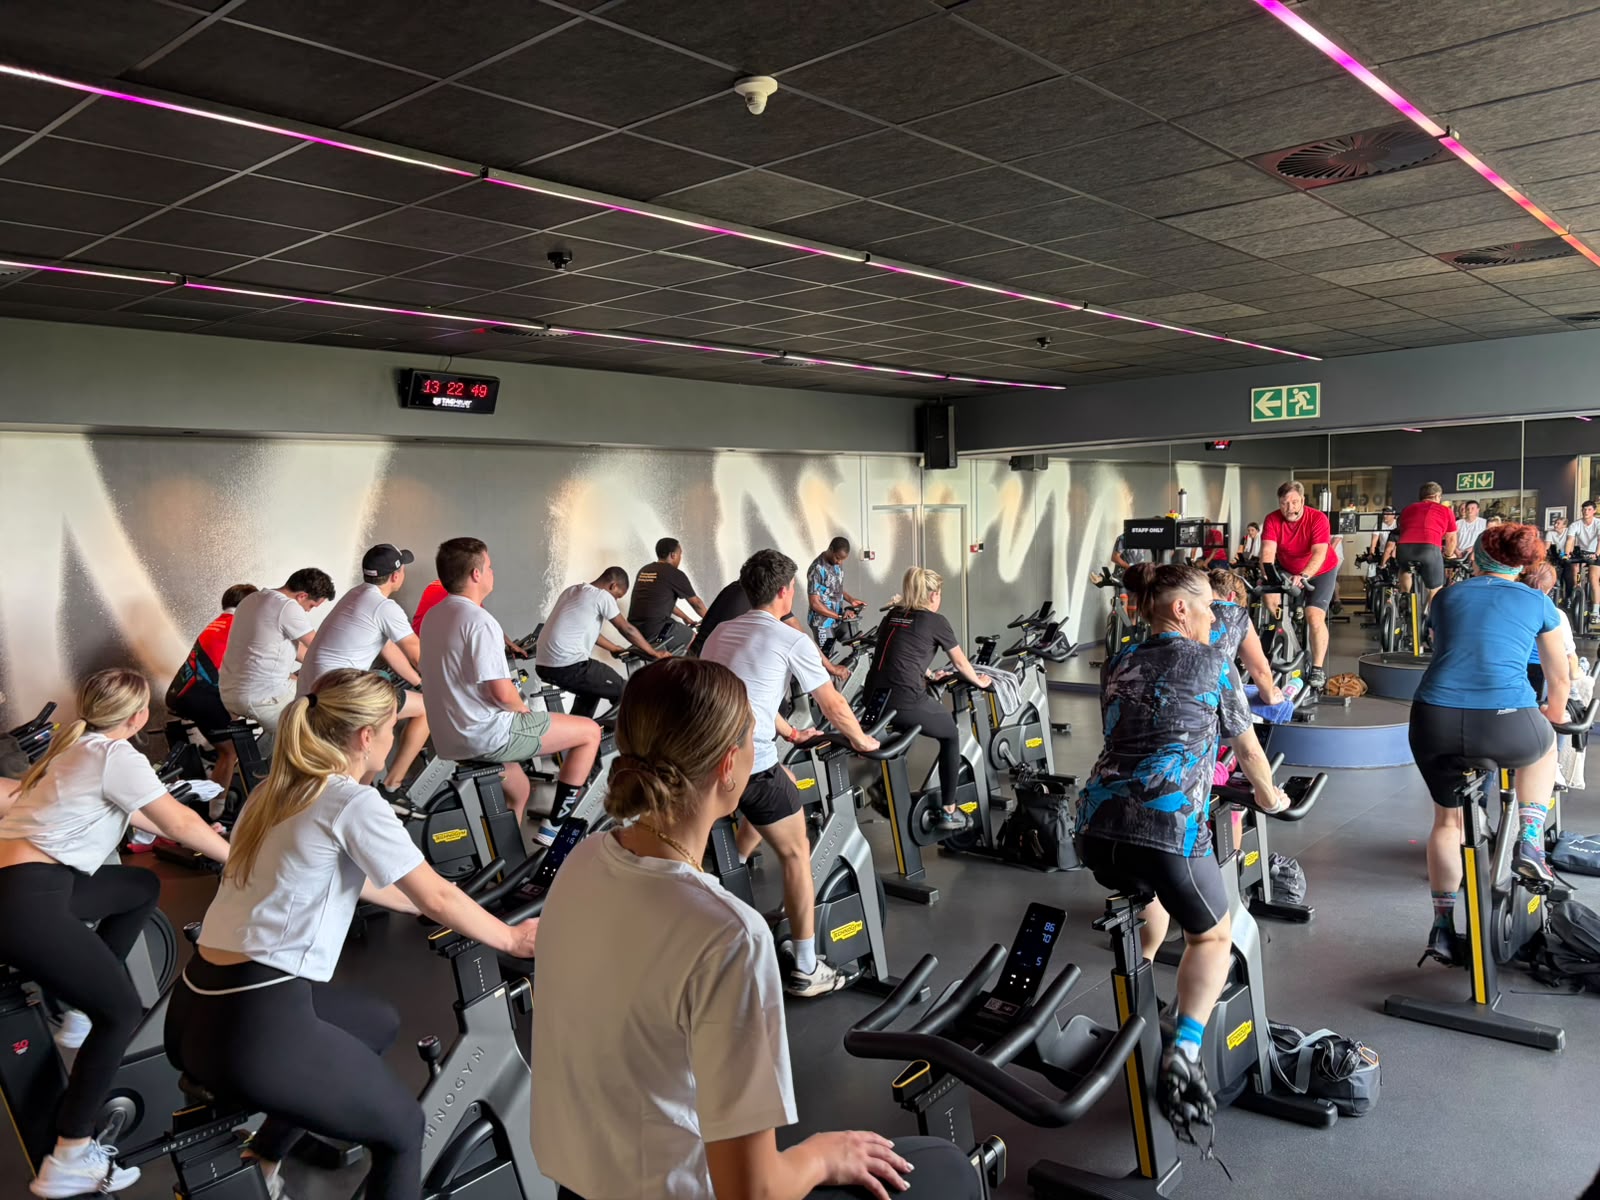
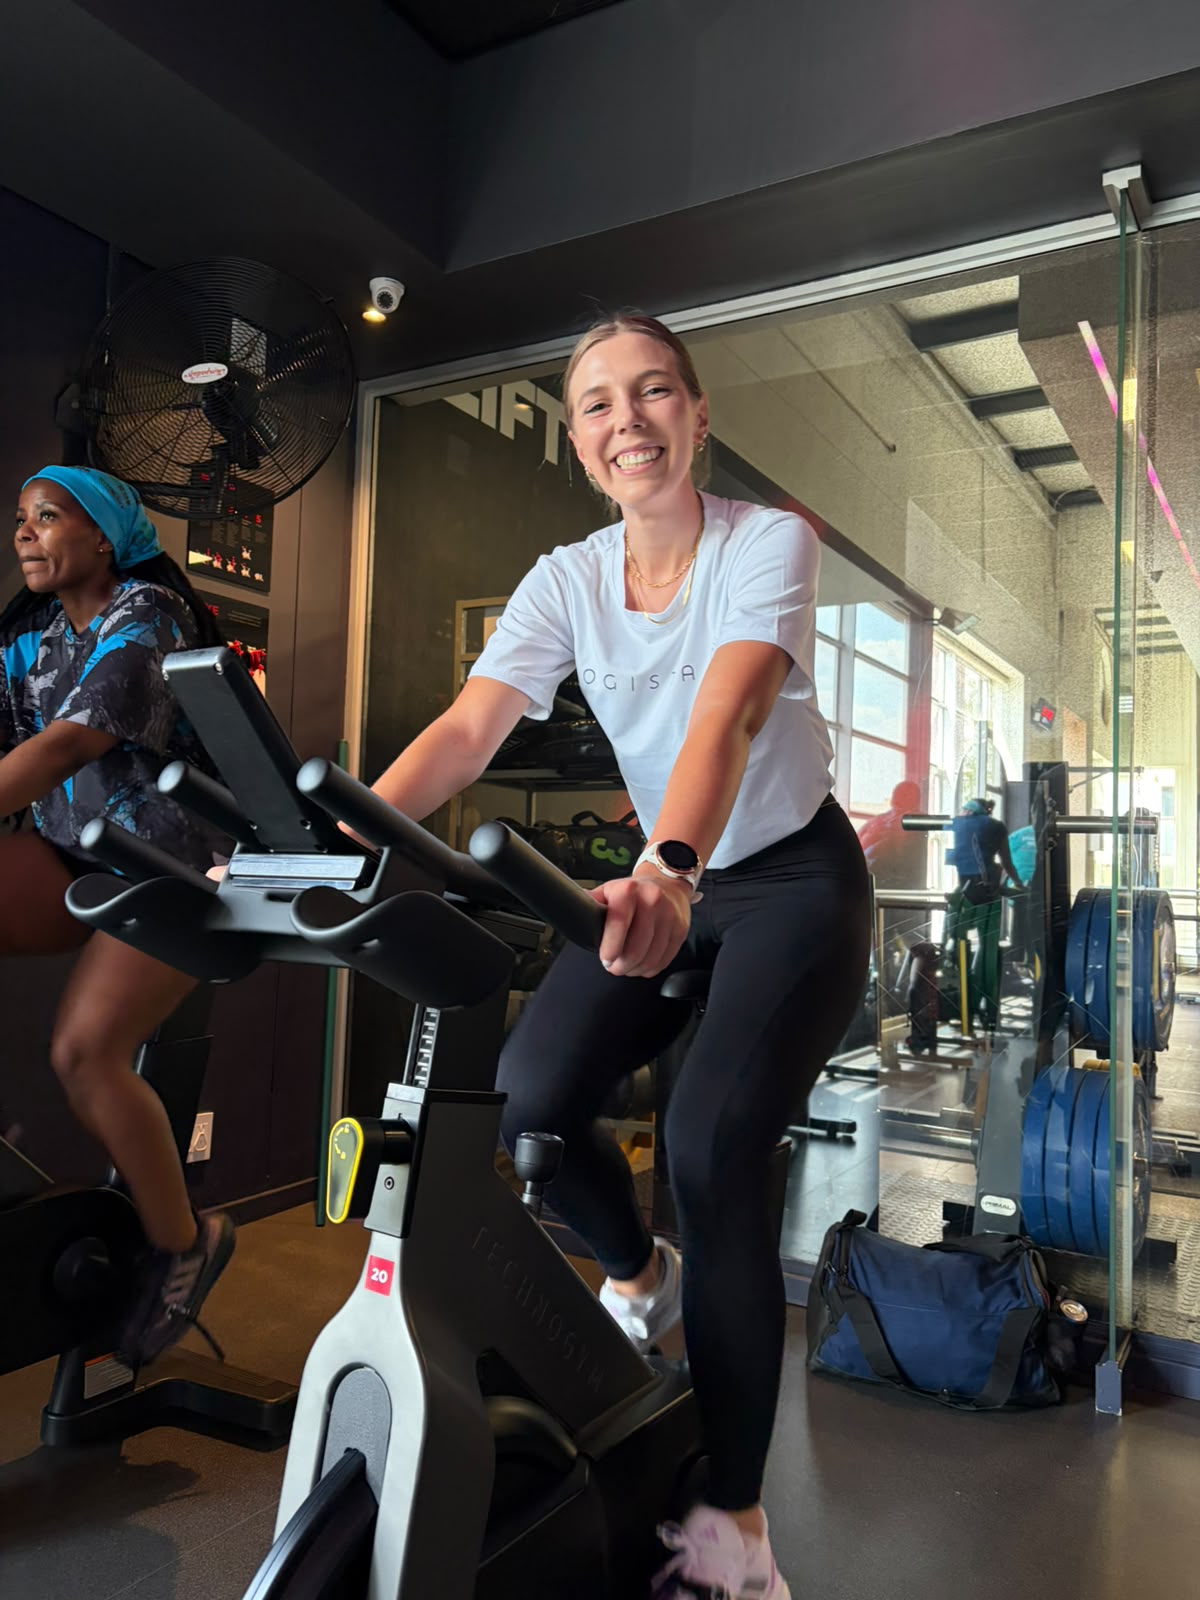
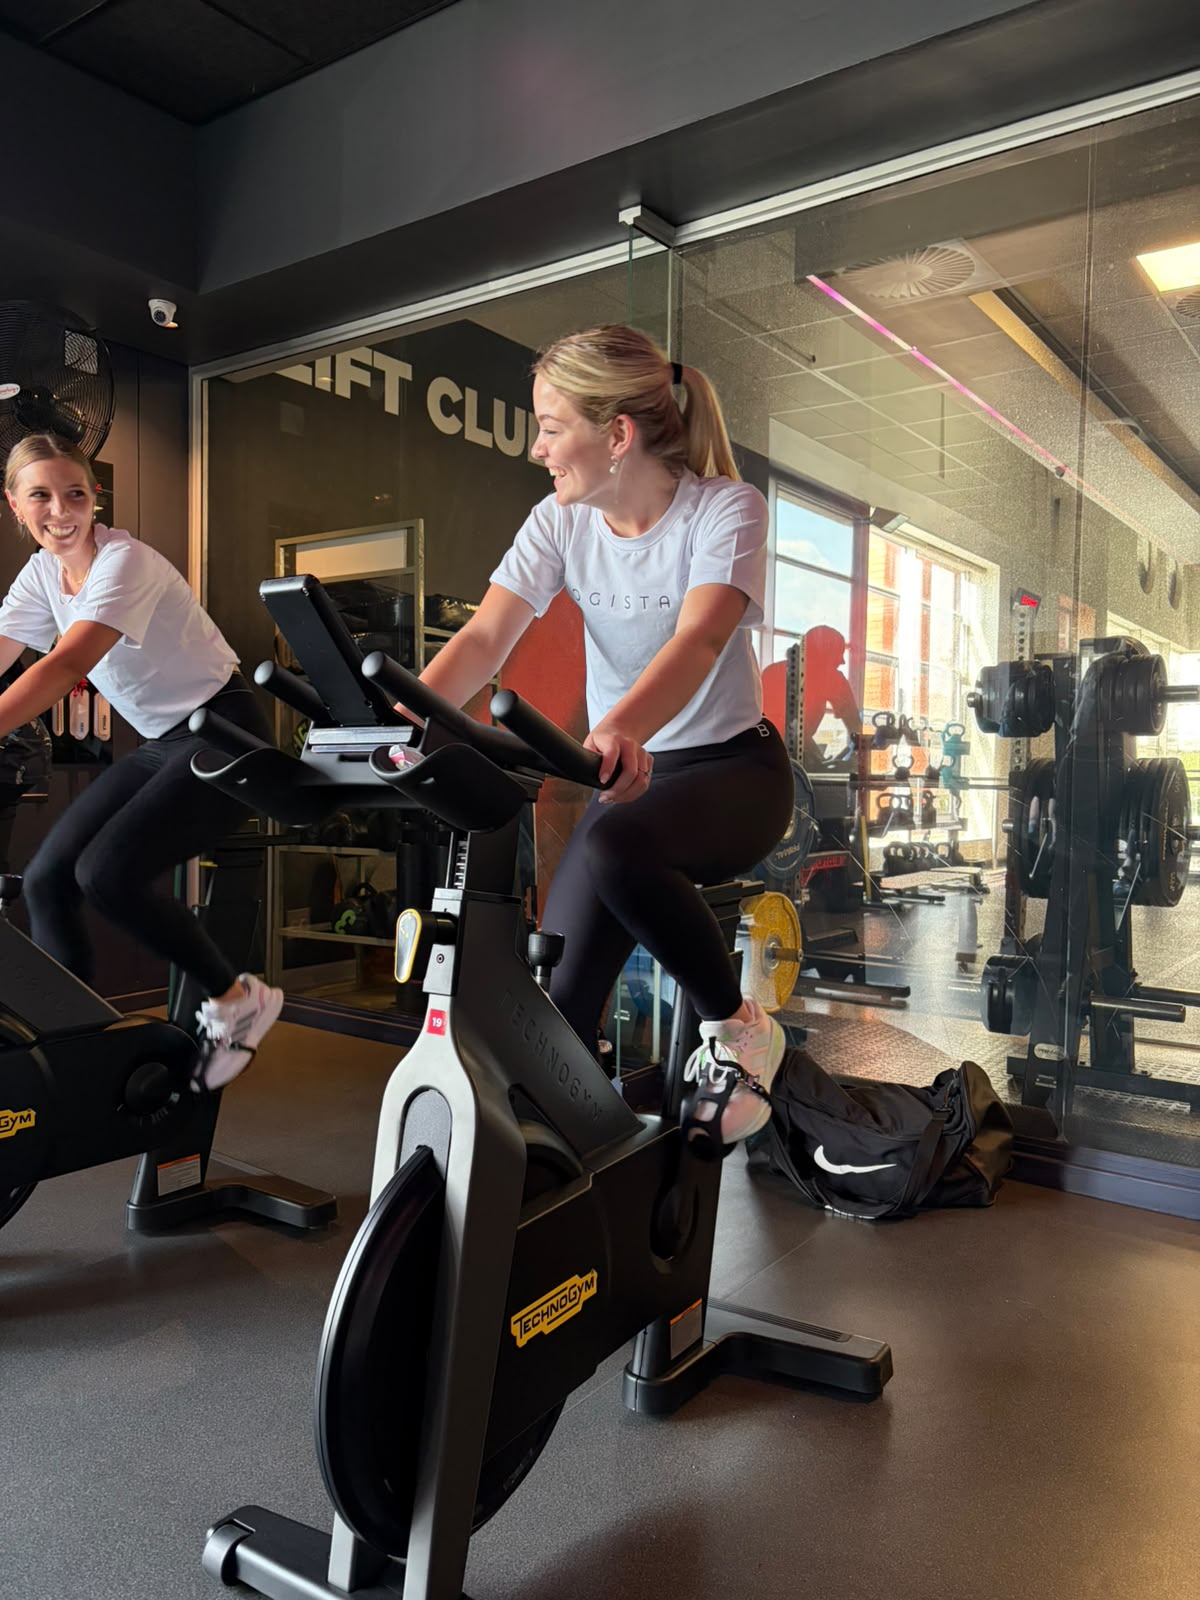
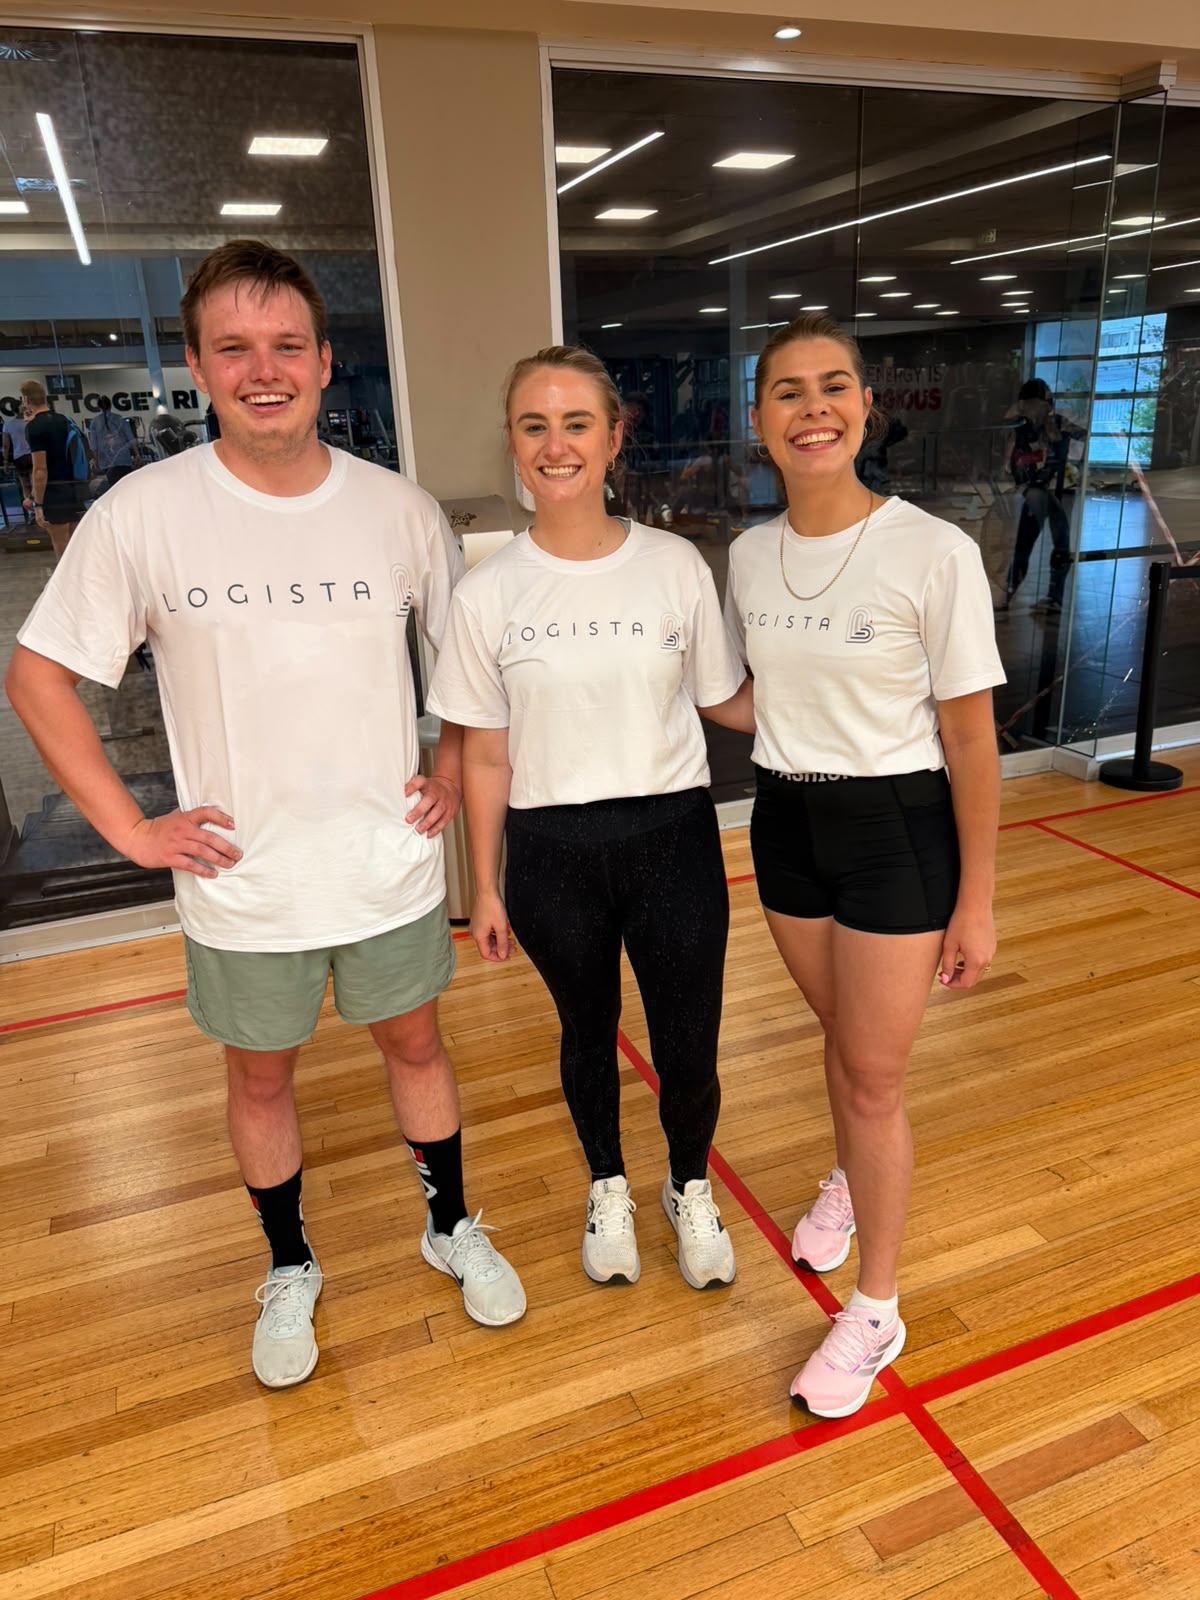
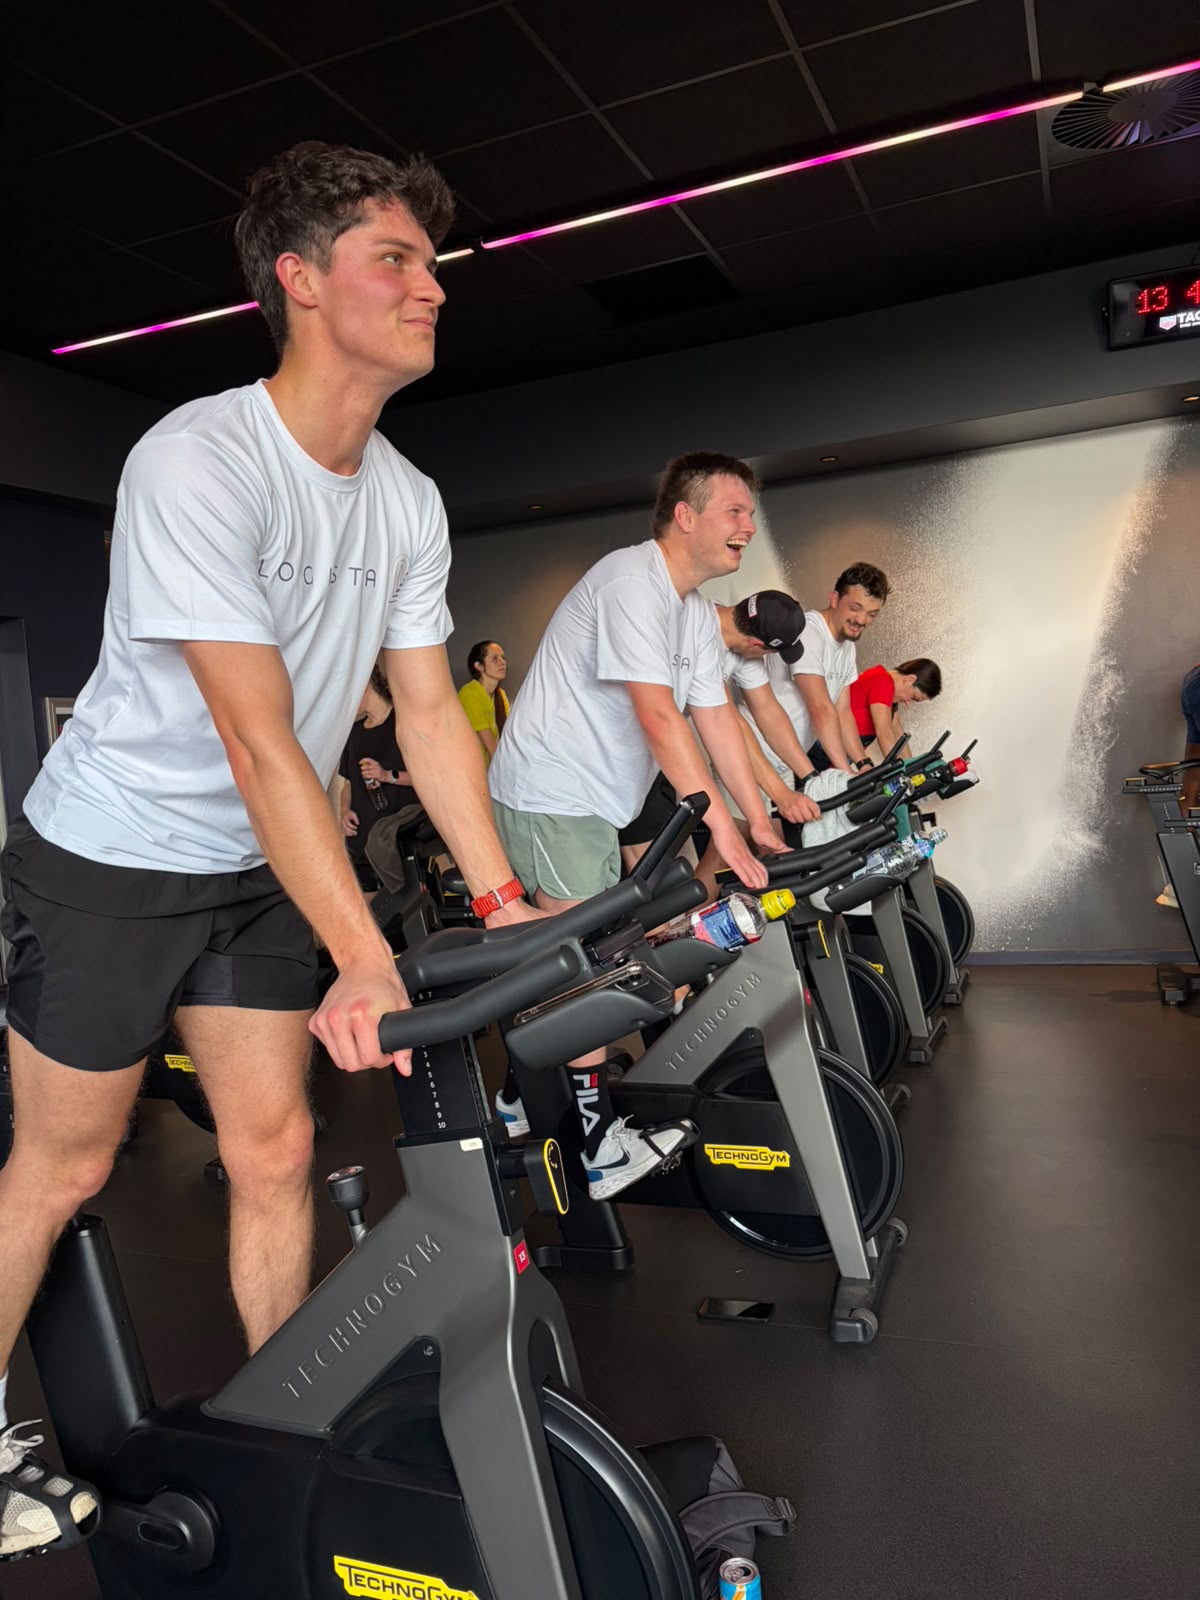
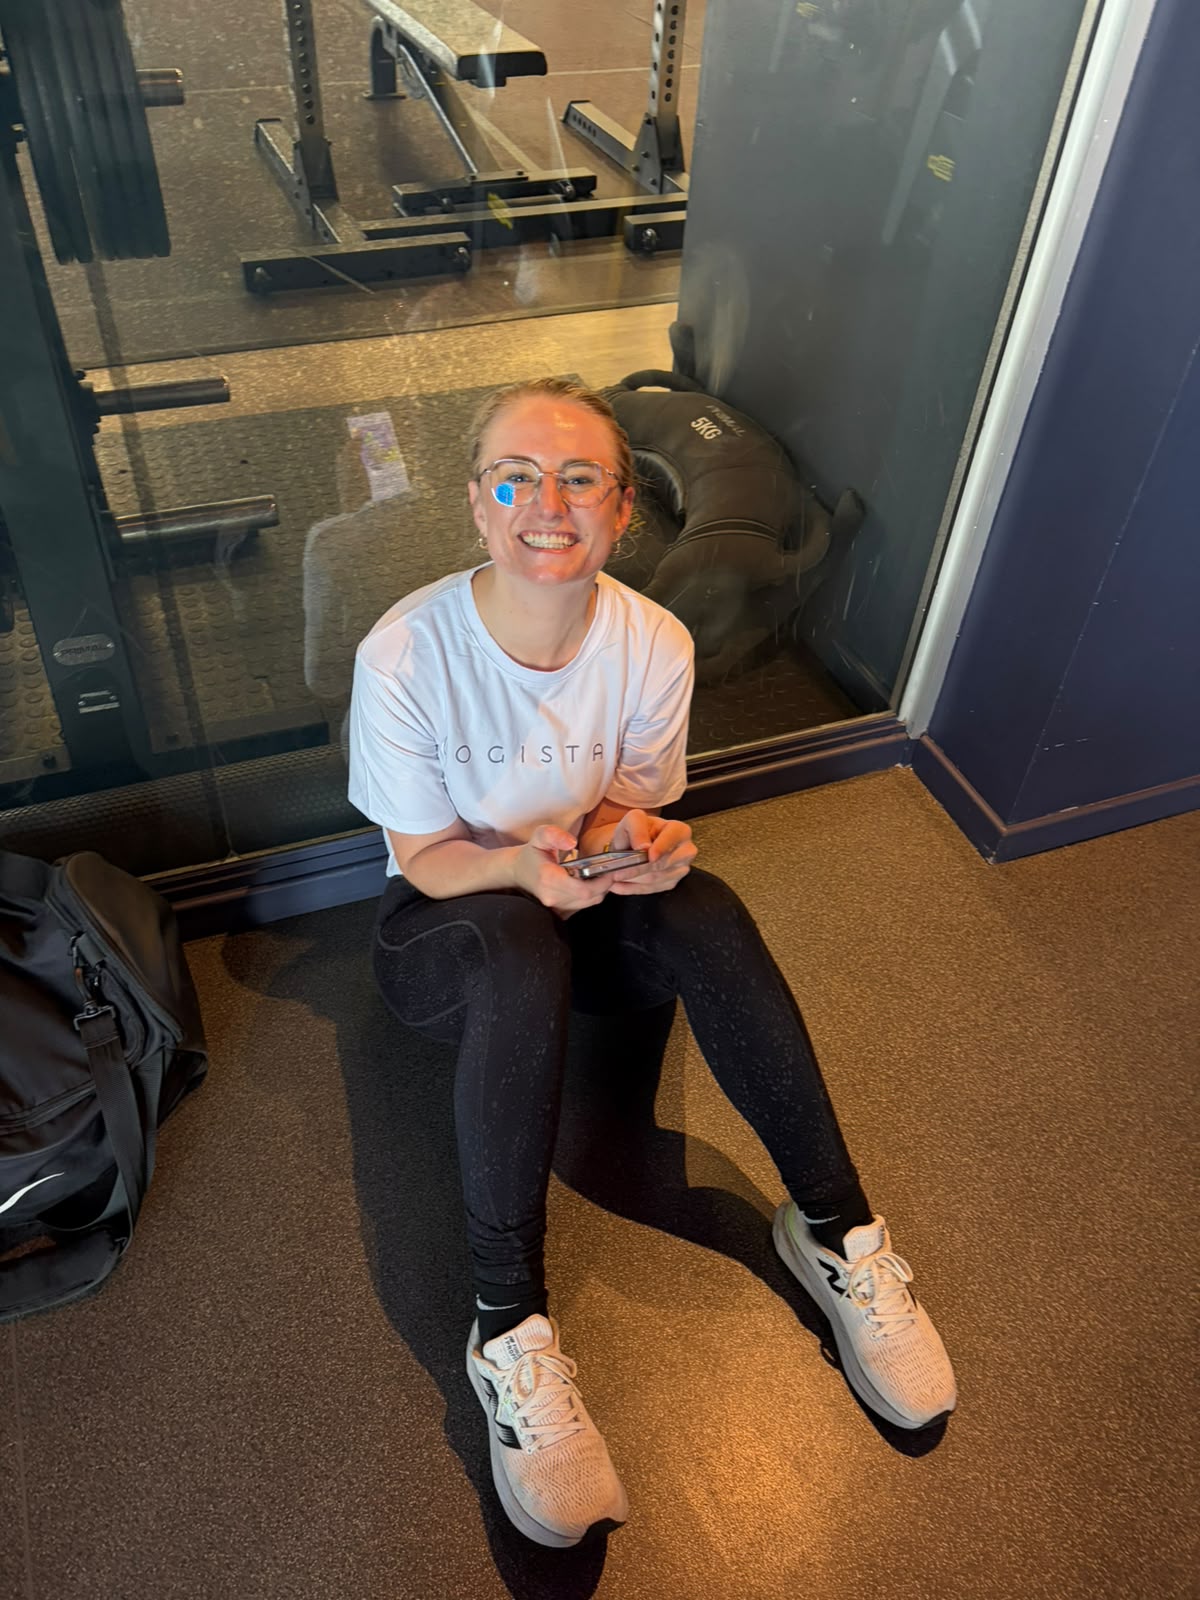
On Friday, 16 October 2026, the LOGISTA team proudly participated in the annual Beeld-Kinderfonds Spinning Marathon, joining fellow participants in an inspiring fundraising initiative dedicated to making a meaningful difference in the lives of vulnerable children.

The event brought together fitness enthusiasts, businesses and community members, all united by a common purpose: raising funds to provide occupational therapy for abused and neglected children. Participants could choose from a variety of activities, including spinning, Zumba, yoga and a relaxing sound bath, making the occasion both an energetic and rewarding experience.

Established in 1977, Beeld-Kinderfonds, now known as Die Kinderfonds, has a long-standing commitment to supporting children in need. Through fundraising initiatives and partnerships, the organisation helps provide access to essential developmental programmes and therapeutic services that support children’s physical and emotional well-being.

At LOGISTA, we believe that making a positive impact extends beyond the work we do for our clients. Supporting initiatives such as the Spinning Marathon reflects our commitment to community involvement, compassion and creating opportunities for a brighter future.

We are proud to have been part of this worthwhile initiative and extend our appreciation to the organisers, participants and everyone who contributed towards making a difference in the lives of children who need it most.

Unlock All the Benefits of Accounting This International Accounting Day

Unlock All the Benefits of Accounting This International Accounting Day

All the creditors must appear in the ledger at the right-hand side, and all the debtors at the left. All entries made in the ledger have to be double entries — that is, if you make one creditor, you must make someone debtor.

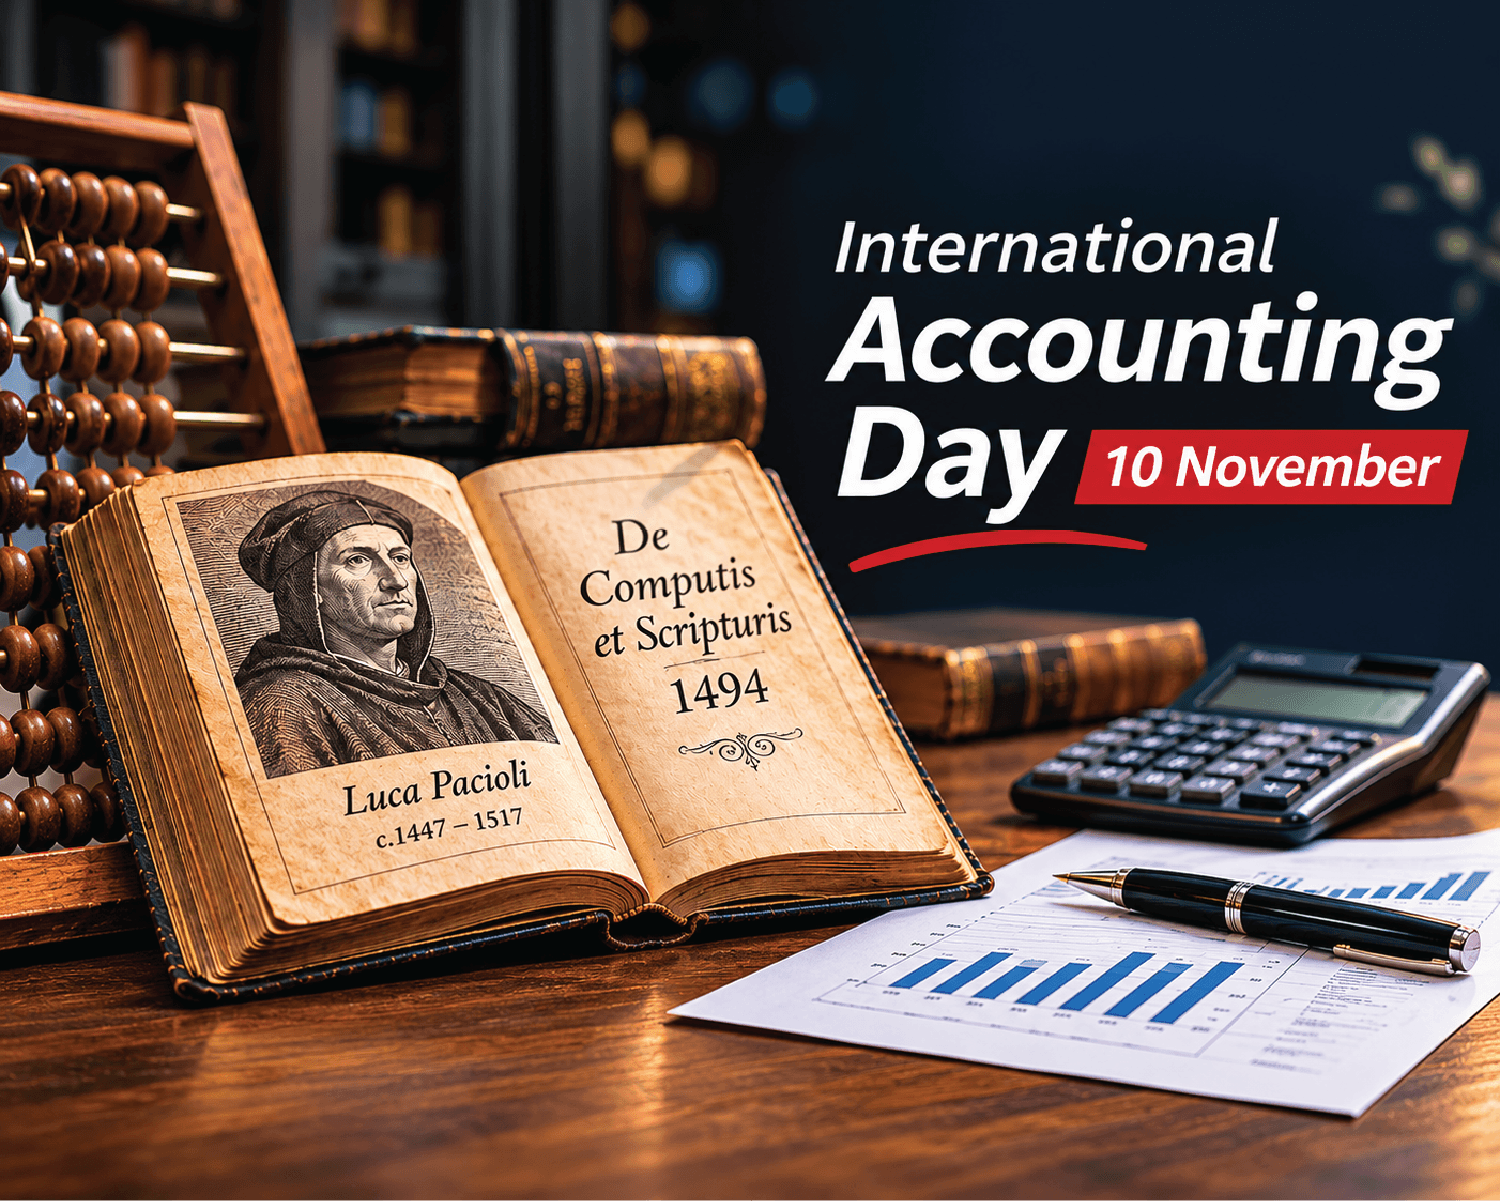
International Accounting Day, observed on 10 November, marks the date Luca Pacioli, the Father of Modern Accounting, published the first detailed description of double-entry bookkeeping in 1494. This day recognises the indispensable role accountants play in supporting businesses and economies worldwide: from ensuring compliance and managing cash flow to enabling strategic growth and detecting fraud.

International Accounting Day is celebrated on 10 November every year, the day Luca Pacioli published the first detailed description of double-entry bookkeeping in his 1494 work Summa de Arithmetica. His system, which requires every debit to have a corresponding credit, remains the foundation of modern accounting. The day acknowledges the critical role of accountants in supporting businesses, as well as the economy at local, national and global levels.

Accountants supporting the economy

Quality financial reporting, auditing, and ethical behaviour by accountants enable strong, sustainable, and inclusive global economic growth. Research by the International Federation of Accountants (IFAC) shows that an increase in the number of accountants correlates to better economic performance. Accountants who are members of professional accountancy organisations make an even more meaningful contribution, correlating to stronger performance on economic indicators.

Accountants supporting businesses

For individual businesses, a professional accountant delivers a wide range of benefits. Among many other skills, they can:

  • Translate financial data so all stakeholders can “understand the numbers”. Accounting is the language of business.
  • Monitor, record and report business performance accurately.
  • Keep track of finances to manage cash flow effectively.
  • Enable accurate budgeting and informed forecasting of revenue and expenses.
  • Ensure compliance with laws and regulations to avoid penalties.
  • Manage payrolls and employee tax obligations.
  • Administer tax obligations and optimise tax positions within the law.
  • Facilitate informed, data-driven decisions with clear financial reports.
  • Identify the most profitable products or services for strategic focus.
  • Optimise spending and reallocate resources to high-growth areas.
  • Detect and prevent fraud by identifying red flags and investigating suspicious transactions.
  • Support strategic planning for future growth and expansion.

Reap all the benefits available

This International Accounting Day is the ideal opportunity to ensure that you and your business are enjoying all the benefits a professional accountant can unlock. From daily financial management to long-term strategic direction, the right accounting partner transforms complexity into clarity.

We will gladly assist you in identifying areas where our expertise and experience can add further value to your business… Be it ensuring compliance, optimising tax, or enabling strategic planning for future growth. Give us a call!

The Death of Cash is Taking Longer Than Expected and Here’s Why

The Death of Cash is Taking Longer Than Expected and Here’s Why

Cash remains the most popular means of payment in the economy, and we are committed to ensuring cash remains readily available and convenient.

Cash was supposed to be on its deathbed. Instead, notes and coins are still changing hands every day, from spaza shops and taxis to supermarkets and small businesses. Digital payments are growing rapidly, but the latest data shows that cash remains deeply embedded in Mzansi’s economy. So why has the cashless future taken so long to arrive?

For years, the story seemed straightforward: smartphones, banking apps, contactless cards and instant payments would steadily push cash towards the exit. South Africa has embraced those technologies, and digital payments are increasingly normal, and yet cash has proved harder to dislodge than many predictions suggested. Using 2024 as its base year, the South African Reserve Bank’s 2026 Cost of Cash study found that cash still accounted for about 56% of consumer transactions by volume. That doesn’t mean digital payments have stalled. It means South Africa is developing a payment system in which digital and cash transactions coexist, serving needs and circumstances for millions of people. The death of cash is taking much longer than initially expected.

Digital payments are growing rapidly

There is little doubt that South Africa is becoming increasingly digital when it comes to payments. Contactless cards, banking apps, instant payments, digital wallets and online shopping have changed how many consumers pay. Businesses have plenty of reasons to make the switch. Digital payments can reduce cash handling, simplify reconciliation and allow businesses to accept payments without being physically present. Mastercard’s 2025 SME Confidence Index found that 90% of South African SMEs surveyed had adopted digital payments. Online shopping provides another indication of the shift. Research from World Wide Worx, Mastercard, Peach Payments and Ask Afrika estimated that online retail would reach R159 billion in 2026, representing 10% of South African retail turnover. The digital economy is booming, but it’s doing so alongside cash.

Cash remains an everyday payment method

While cards and digital payment methods tend to account for a larger proportion of higher-value transactions, the SARB found that cash is much more important for transactions involving lower amounts. According to the study, the average cash payment was R208.44, compared with an average of R529.21 across all payment methods. For many businesses and customers, the simplicity of cash still has value.

One size doesn’t fit all

Another reason cash has proved difficult to eliminate is that South Africa’s economy is not uniform. A consumer living in an affluent urban area with reliable connectivity and several digital payment options has a very different payment environment from somebody buying goods from an informal trader or living in an area where financial infrastructure is less accessible. The SARB’s Cash Smart Strategy recognises this difference, identifying rural towns, townships and informal settlements as areas where cash remains particularly important.

Immune to technological failure

Even in areas where the technology is generally available, breakdowns occur. Power failures, network problems and technical outages can interrupt electronic transactions, while cash sails steadily on. In a country that’s experienced repeated infrastructure disruptions, that remains a practical consideration.

Feel the burn

Digital payments can make spending feel invisible: a tap of a card or phone is barely noticeable. Cash makes the transaction more tangible, and withdrawing a fixed amount can also provide a straightforward way of controlling spending. This means there is also a behavioural reason for cash’s resilience. Simply making digital payments available to an area therefore does not guarantee that everyone will adopt them.

The informal economy matters

South Africa’s informal economy is another important part of the picture. Many informal businesses operate on a smaller scale and may have different banking relationships, infrastructure and administrative requirements from larger formal retailers. In this sector, cash remains a practical way of accepting payment from customers without investing in additional technology, or third-party systems, which may be costly or cut into margins which are already extremely tight.

What this means for small business owners

For the average South African small business owner, cash’s resilience points to a practical lesson: being able to accept both is probably a smart choice when plotting the way forward. We can help you work out just how relevant each payment option is to your business, but here are some general rules.

  • Don’t turn away the cash customer. With cash still making up about 56% of consumer transactions by volume, a business that refuses cash risks losing a large share of everyday spending. That matters most for lower-value purchases. For businesses selling small-ticket items, cash customers are most likely the real core of the trade.
  • Build in a backup. Power cuts, network failures and platform outages can stop card machines and payment apps at the worst moment. A business that can still take cash, and keeps enough change on hand, can keep trading while competitors send customers away.
  • Offer a full range of options. With 90% of surveyed SMEs already using digital payments, being able to accept them is fast becoming the baseline. The advantage lies in combining that with cash, so that customers can pay however suits them.
  • Manage the costs. There are numerous reasons why taking cash might be attractive, particularly for businesses that operate alongside the informal economy. The savings on bank fees may be attractive, but this should be carefully weighed against the risks of holding cash, so regular banking of takings and careful record-keeping are essential.

The businesses best placed to benefit are those that treat cash and digital payments as partners rather than competitors. And it doesn’t look like that will change soon.

The Profit First Business Model: Could it Work for You?

The Profit First Business Model: Could it Work for You?

When less money is available to run your business, you will find ways to get the same or better results with less. By taking your profit first, you will be forced to think smarter and innovate more.

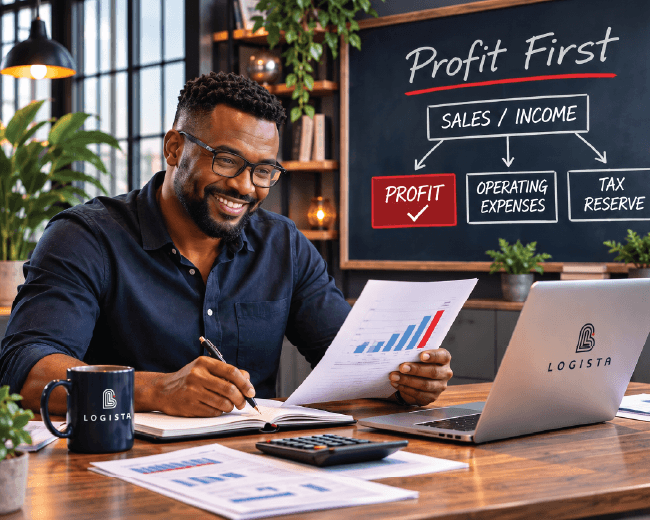
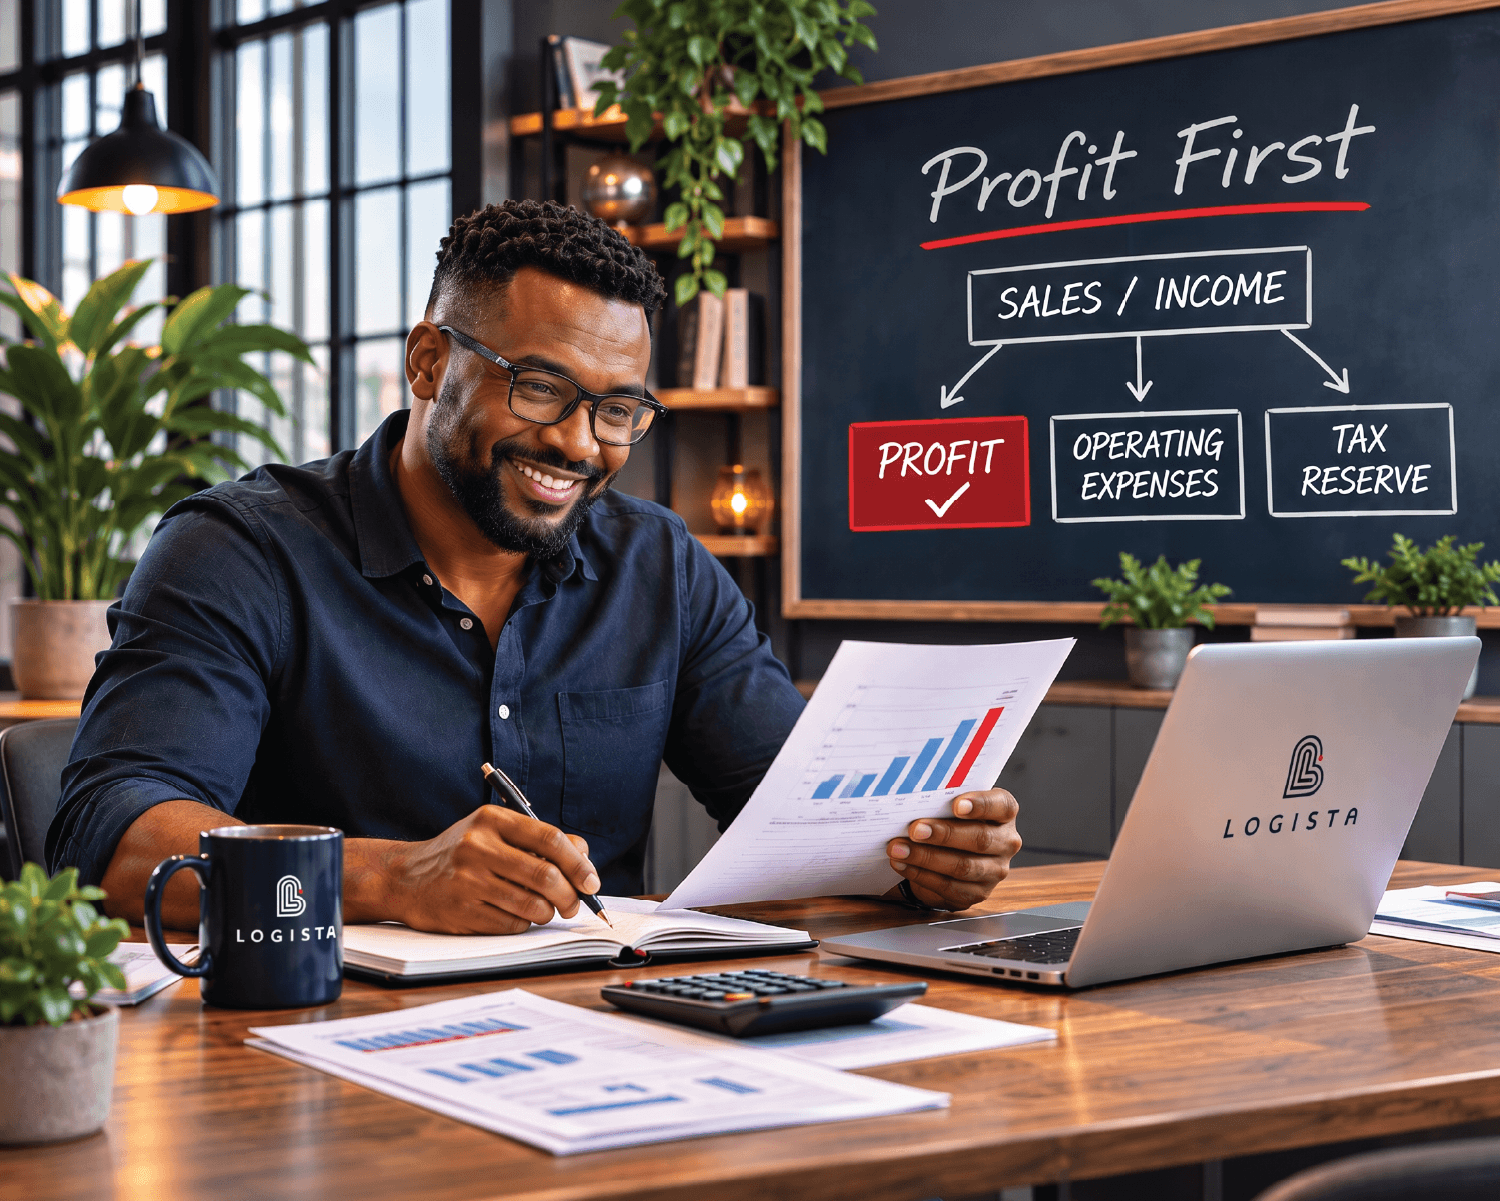
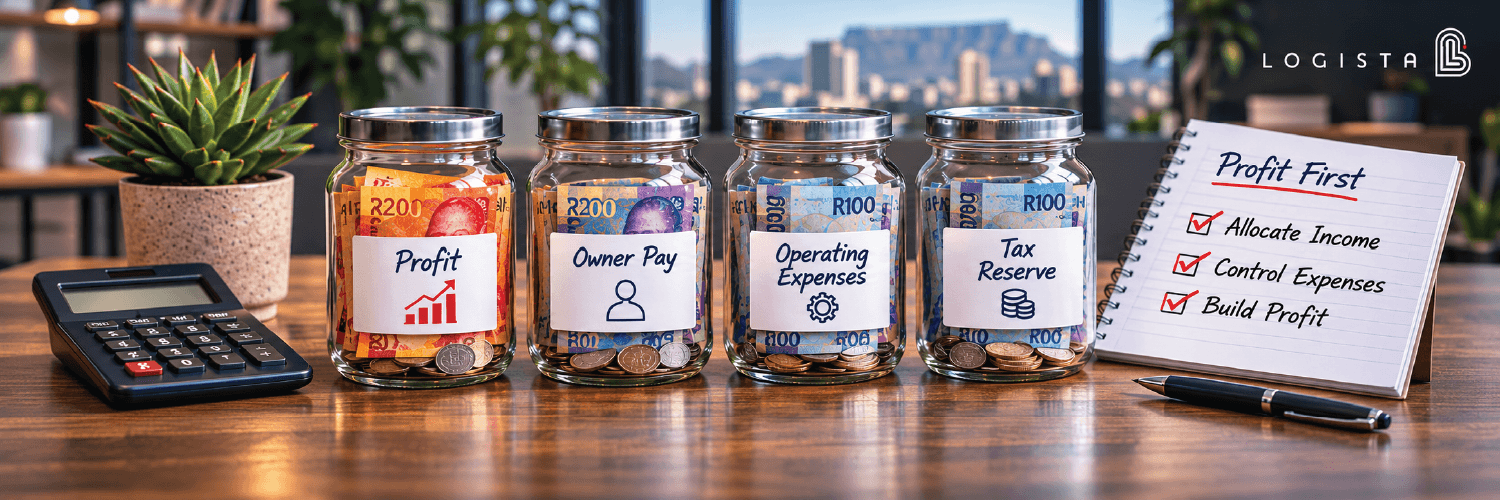
The Profit First business model flips a century-old accounting formula on its head. Instead of Sales minus Expenses equals Profit, small business owners take their profit first and let expenses shrink to fit what remains. Created by entrepreneur Mike Michalowicz, the system uses multiple bank accounts and fixed percentages to force discipline. For struggling entrepreneurs drowning in overheads, this counterintuitive approach may be the key to lasting financial control.

Ask most small business owners how they manage money, and you’ll hear a version of the same formula: Sales minus Expenses equals Profit. It seems logical, but it also means profit is whatever happens to be left over, which is often nothing at all. This is the trap author and entrepreneur Mike Michalowicz set out to fix when he developed the Profit First system. Rather than treating profit as a leftover, Profit First insists it be allocated immediately, before covering a single expense. The remaining money becomes the operating budget, forcing owners to run leaner, smarter businesses. It sounds backward, even risky. But for thousands of entrepreneurs who have adopted the method, it has proven to be less about restricting growth and more about revealing which expenses were never necessary in the first place.

Flipping the traditional accounting formula

Traditional accounting treats profit as a result: revenue comes in, bills go out, and whatever survives is profit. Michalowicz argues that this formula permits overspending, because expenses expand to consume whatever cash is available. His Profit First model reorders the equation so profit is subtracted first, and expenses are calculated from what remains. The logic doesn’t change the underlying math, but it does change behaviour. And behaviour, the maths shows, determines whether a small business survives.

The envelope system, modernised

At the heart of Profit First is a system of separate bank accounts, each representing a slice of incoming revenue: profit, owner’s compensation, taxes, and operating expenses. A fixed percentage of every rand that comes in is automatically allocated across these accounts, typically on a fortnightly basis. This is essentially the classic “envelope budgeting” method used by frugal households, but applied to a business’s income. Because the operating expenses account only ever contains a capped percentage of revenue, owners are structurally prevented from overspending. The money for extras simply isn’t there.

Cash crisis or growth problem?

Data on small businesses backs up the need for a different approach. The U.S. Bank famously found that 82 percent of small business failures are linked to cash flow problems, not lack of profitability on paper. Businesses can show a healthy income statement and still run out of cash, largely because expenses were allowed to grow unchecked while net cash flows sat as an afterthought. Profit First directly targets this mismatch by making cash flow, rather than projected profit, the operating discipline.

Constraint breeds innovation

One of the more counterintuitive claims of the Profit First philosophy is that constraint improves performance rather than limiting it. When less money is available to run the business, Michalowicz contends, owners are forced to find smarter and more efficient ways of operating instead of simply spending their way through problems. This mirrors a well-documented finding in behavioural economics known as Parkinson’s Law. This is the idea that spending, like work, expands to fill the resources available. By capping the funds available for expenses, Profit First deliberately triggers a search for efficiency that a bigger operating account would never demand.

But is it the right model for your business?

The model is not universally embraced. Some accountants and financial advisors argue that Profit First’s fixed percentage allocations can feel arbitrary for businesses with irregular revenue, seasonal cycles, or high fixed costs, such as manufacturers with heavy equipment financing. Critics also note that the system does not replace the need for a solid financial forecast or a real understanding of margins, it simply complements them. For businesses with wafer-thin margins, moving money into a profit account before covering costs can create short-term liquidity strain if it’s not paired with careful planning during the transition period.

It is therefore vital that you speak to your accountant before making any changes.

Baby steps

Advisors who work with the method generally recommend a gradual rollout rather than an abrupt switch. Business owners are encouraged to start with modest allocation percentages, sometimes as low as 1 percent to a profit account, and increase them quarterly as the business adjusts to operating on a leaner expense base. The goal isn’t to starve the business overnight, but to build, in Michalowicz’s words, a habit rather than an event: small, consistent decisions that compound into structurally healthier finances over time.

The bigger behavioural shift

Perhaps the most lasting impact of Profit First isn’t the specific percentages or the number of bank accounts a business uses; it’s the shift in mindset it demands. Instead of asking “how much did we make?” at the end of a difficult year, owners are asking “how do we protect profit from the very first rand?” That single reframing turns expense control from a reactive, after-the-fact exercise into a proactive discipline built into the rhythm of the business. This may be exactly the kind of structural change your business needs.

Trust Tax Season 2026 Is Now Open

Trust Tax Season 2026 Is Now Open

Trustees remain accountable for all tax matters of a trust, regardless of the economic activity of the trust.

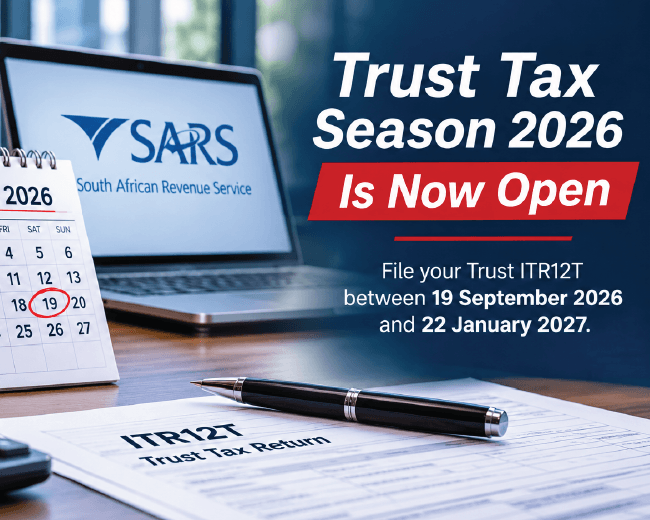
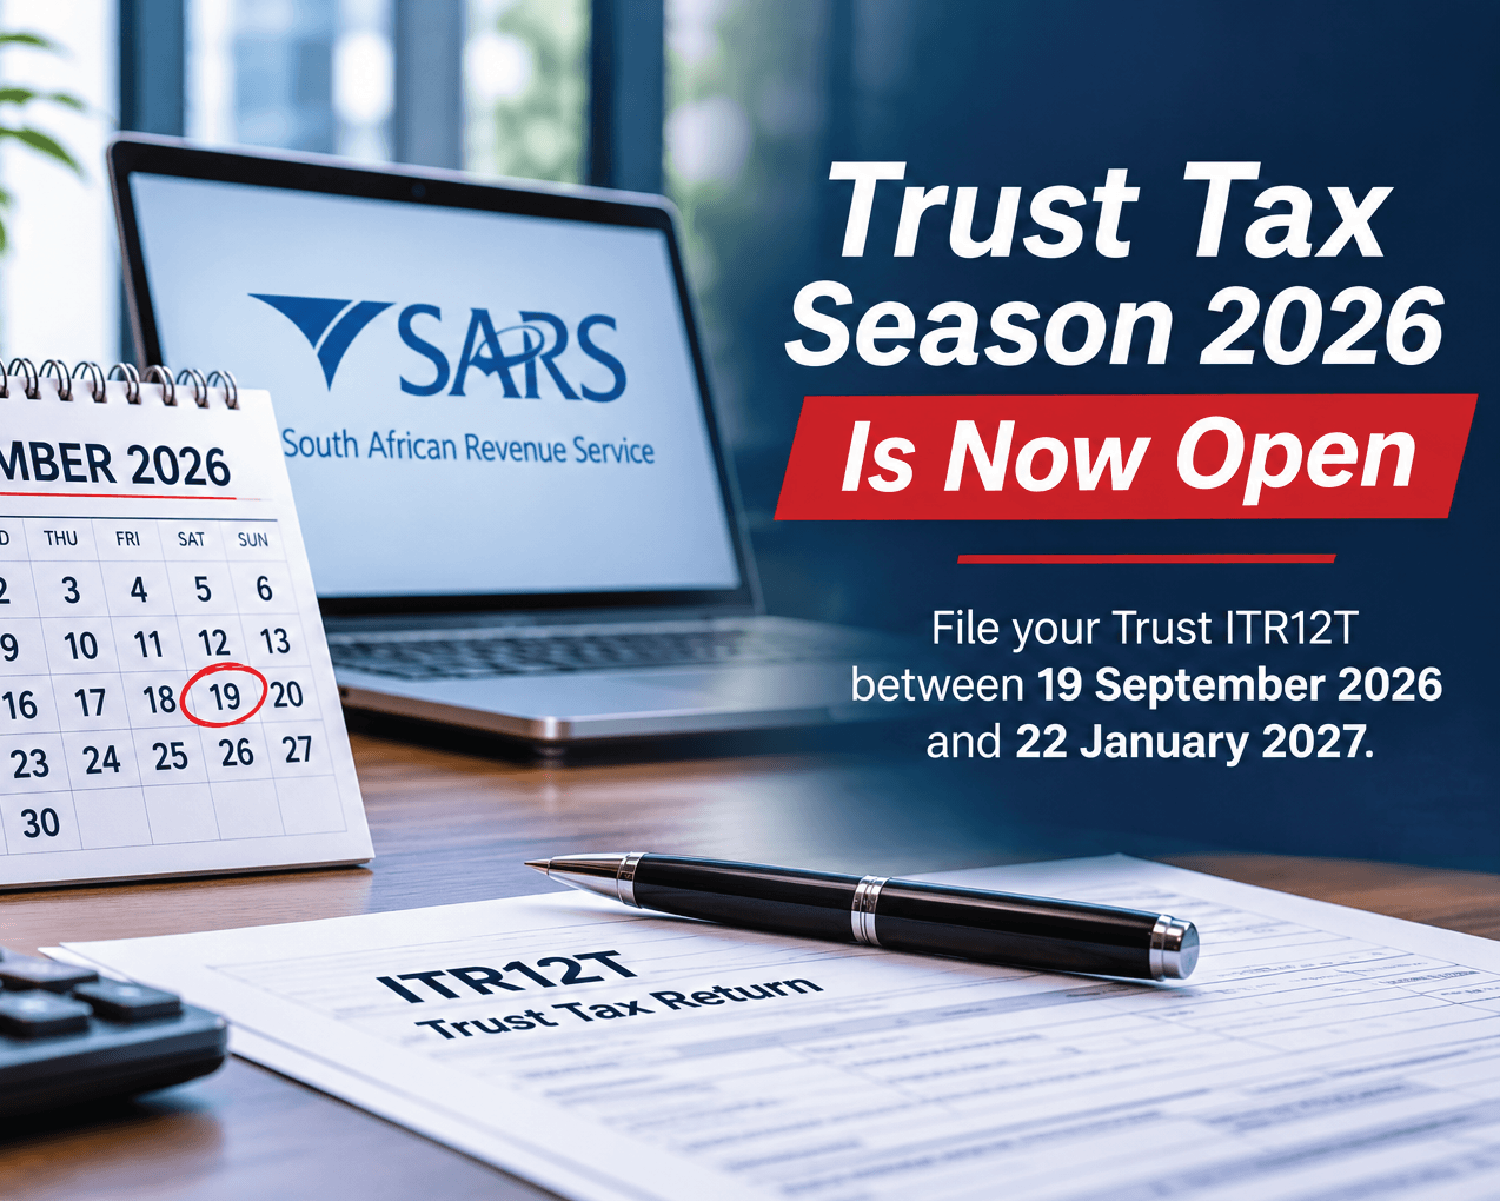
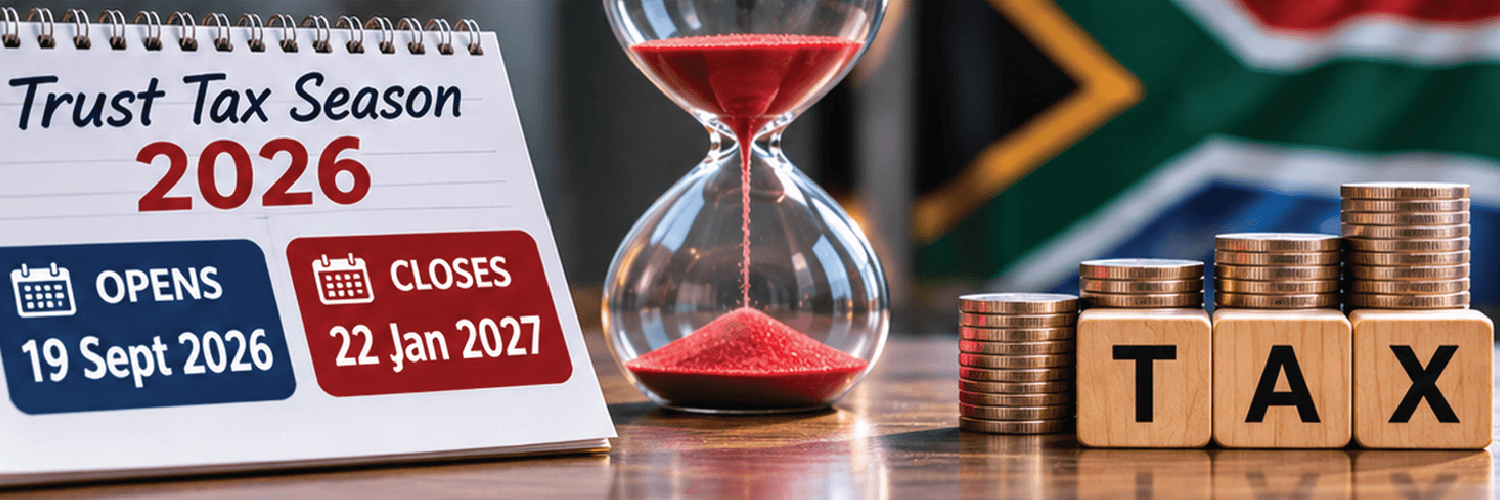
SARS has confirmed that tax filing season for Trusts opened on 19 September 2026, with the closing date set for 22 January 2027. This year brings important enhancements to the ITR12T trust return which takes place against the backdrop of SARS's administrative non-compliance penalty framework for trusts, which came into effect on 4 May 2026 and applies to outstanding trust income tax returns for tax periods from 2024 onwards.Trustees remain accountable for all trust tax matters, regardless of economic activity, so please read this article carefully.

Filing season for Trusts opened on 19 September 2026 and the closing date for Trusts to file is 22 January 2027 for both provisional and non-provisional trust taxpayers. Trustees and registered representatives should file the Income Tax Return for Trusts (ITR12T) within this period.  All registered resident Trusts and qualifying non-resident Trusts are required to submit returns in accordance with SARS’s filing requirements. For resident trusts, this obligation applies regardless of transactions or income, or whether they are active or passive, and even if they are considered “dormant”. Non-resident trusts must submit returns where they meet the applicable South African tax filing criteria.

Key changes and enhancements for 2026

The new penalty framework, which came into effect on 4 May 2026, applies to outstanding trust income tax returns for tax periods from 2024 onwards.

The ITR12T has also been enhanced to make it easier to comply with trust obligations and avoid administrative penalties for late or non-submission. These enhancements include:

  • Income, vested amounts and certain expense information has been pre-populated with IT3(t) data to reduce duplication and improve accuracy.
  • Beneficiary schedules on the ITR12T are also pre-populated using IT3(t) third-party data.
  • Beneficial ownership founder questions have been enhanced to cater for cases where the founder is a legal entity that no longer exists, in addition to deceased natural persons.
  • Tax practitioner contact details are now a mandatory field, facilitating effective communication between SARS and practitioners.

Nil returns and assessed-loss positions under the microscope

According to a 7 September press release, this filing season, “SARS will prioritise identifying, analysing, and resolving disparities detected in the submission of nil returns and assessed-loss positions.” SARS is especially keen to correct the misconception among trust taxpayers that passive trusts not actively used in the production of income may file nil returns: “The existence of passive assets does not relieve a trust from the obligation to disclose its assets, liabilities, and all relevant financial information.” Taxpayers are reminded that all assets, including “dormant” or passive assets, must be disclosed. All income and expenditure relating to such assets (e.g. a holiday home or immovable property and the upkeep of such property) must be accurately declared. “Nil returns or assessed-loss positions must be fully supported by the trust’s records and underlying circumstances,” says SARS.

The buck stops with the trustees

SARS emphasises that “the responsibility for obtaining, maintaining, and updating accurate trust information rests exclusively with the trustees.” The Trust Property Control Act No. 57 of 1988 (TPCA) requires trustees to act with care, diligence, and skill in managing trust affairs. The “joint action rule” stipulates that co-trustees must act collectively in the administration of a trust. Although trustees may appoint a tax practitioner to help administer the trust and fulfil its obligations, trustees remain legally liable and responsible for the trust’s tax compliance. This is not an idle threat: in some cases, trustees can be held personally liable for a trust’s tax obligations.

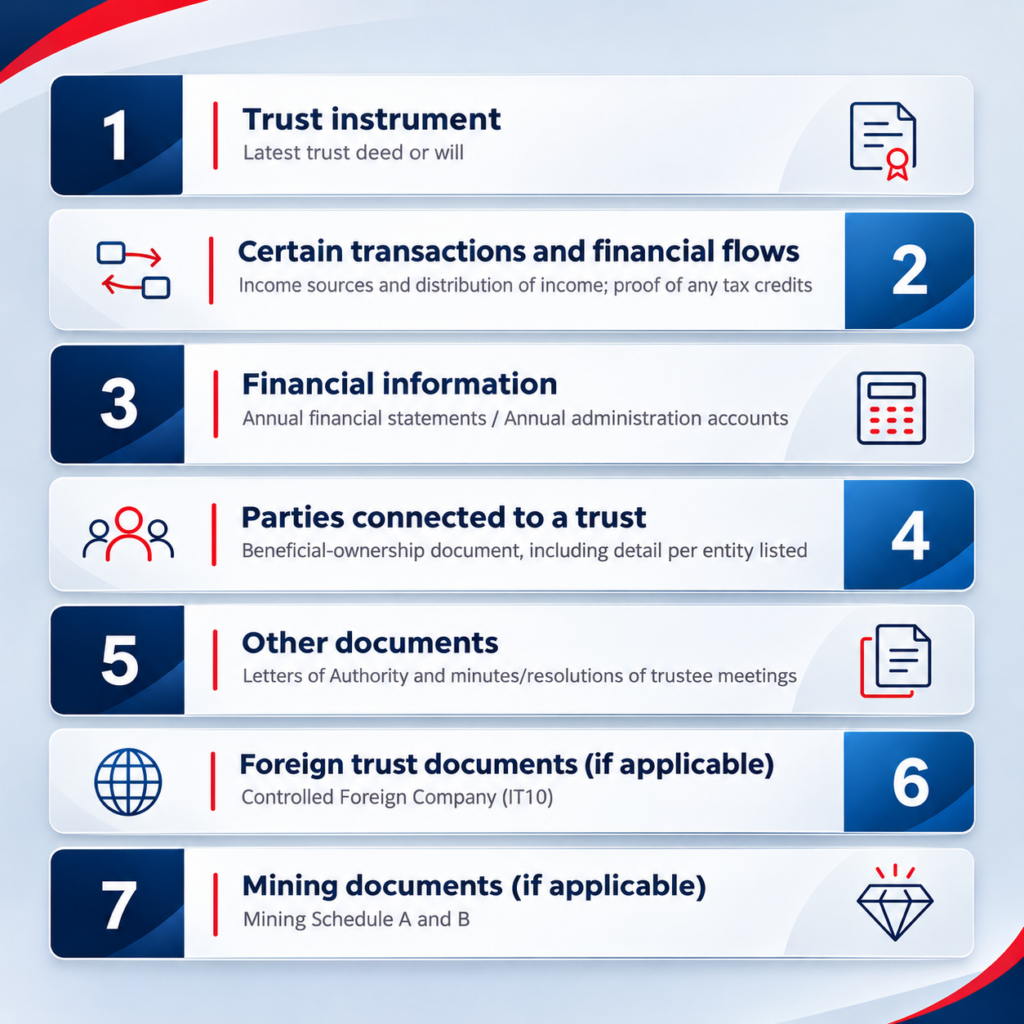
What you need to file an ITR12T trust tax return

Trustees should have these documents available when completing the ITR12T or when requested by SARS:

Trustees must remember to report any changes to the registered details of a trust to SARS within 21 business days of the change. This includes changes to trustees, the representative taxpayer, contact details, physical or postal addresses, and any other registered particulars. “Failure to notify SARS of changes may constitute a criminal offence under section 234 of the Tax Administration Act.”

Have you missed this deadline?

The IT3(t) third-party data return was due for submission on 30 September 2026 for the 2026 year of assessment. This IT3(t) return must be submitted by representative taxpayers of trusts, containing “details of amounts vested in beneficiaries for a specific year of assessment. The IT3(t) return is used to populate beneficiaries’ tax returns with the amounts vested to those beneficiaries by the trust.” If your trust missed this deadline, contact us without delay so we can assist you by taking immediate corrective action and avoiding compounding non-compliance penalties.

Deregistration of trusts

When a trust has effectively ceased to operate and has been terminated in accordance with the trust instrument and applicable law, trustees should take the necessary steps to deregister the trust with both the Master of the High Court and SARS. This is because a deregistration with the Master does not automatically mean deregistration with SARS – a trust must deregister with SARS by submitting a deregistration request, together with the required supporting documents.

We can help

Trust tax season can be complex, with significant penalties for non-compliance. Our team is experienced in keeping trusts compliant, reducing costs and preventing hassles with SARS. If you need assistance meeting the trust tax deadline on 22 January 2027, simply reach out to us. It’s the easiest way to survive this trust tax season, and those ahead.

Around the World – The Logista Way!

Around the World – The Logista Way!

Good Company, Great Fun and Memories Worth Making!

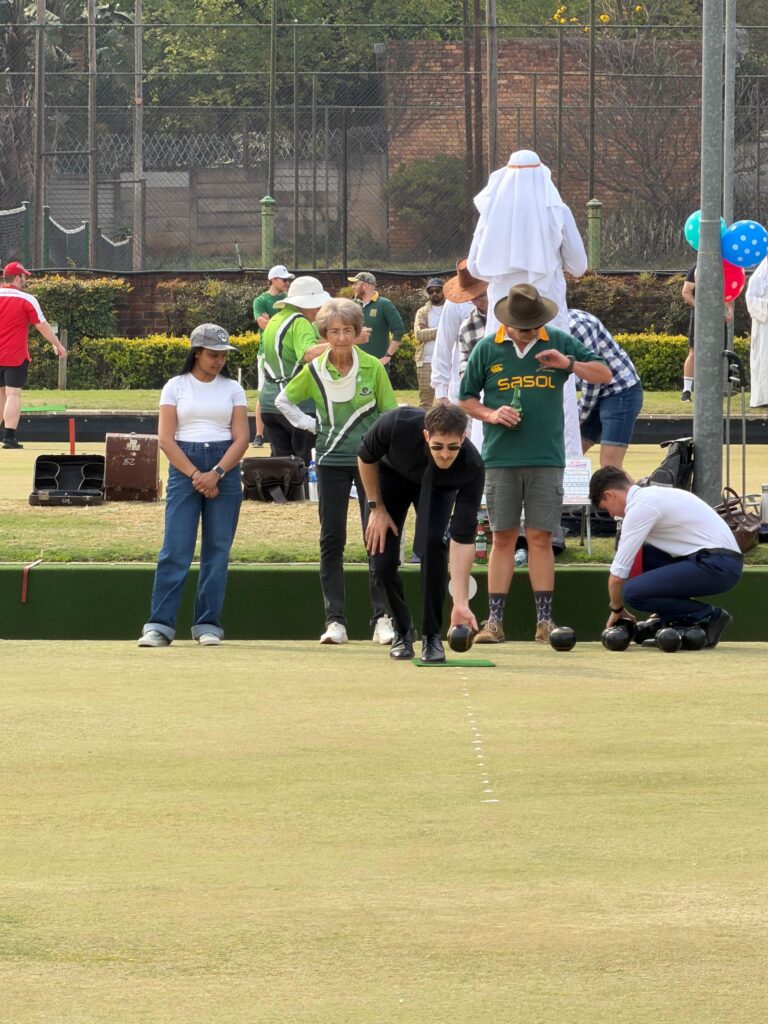
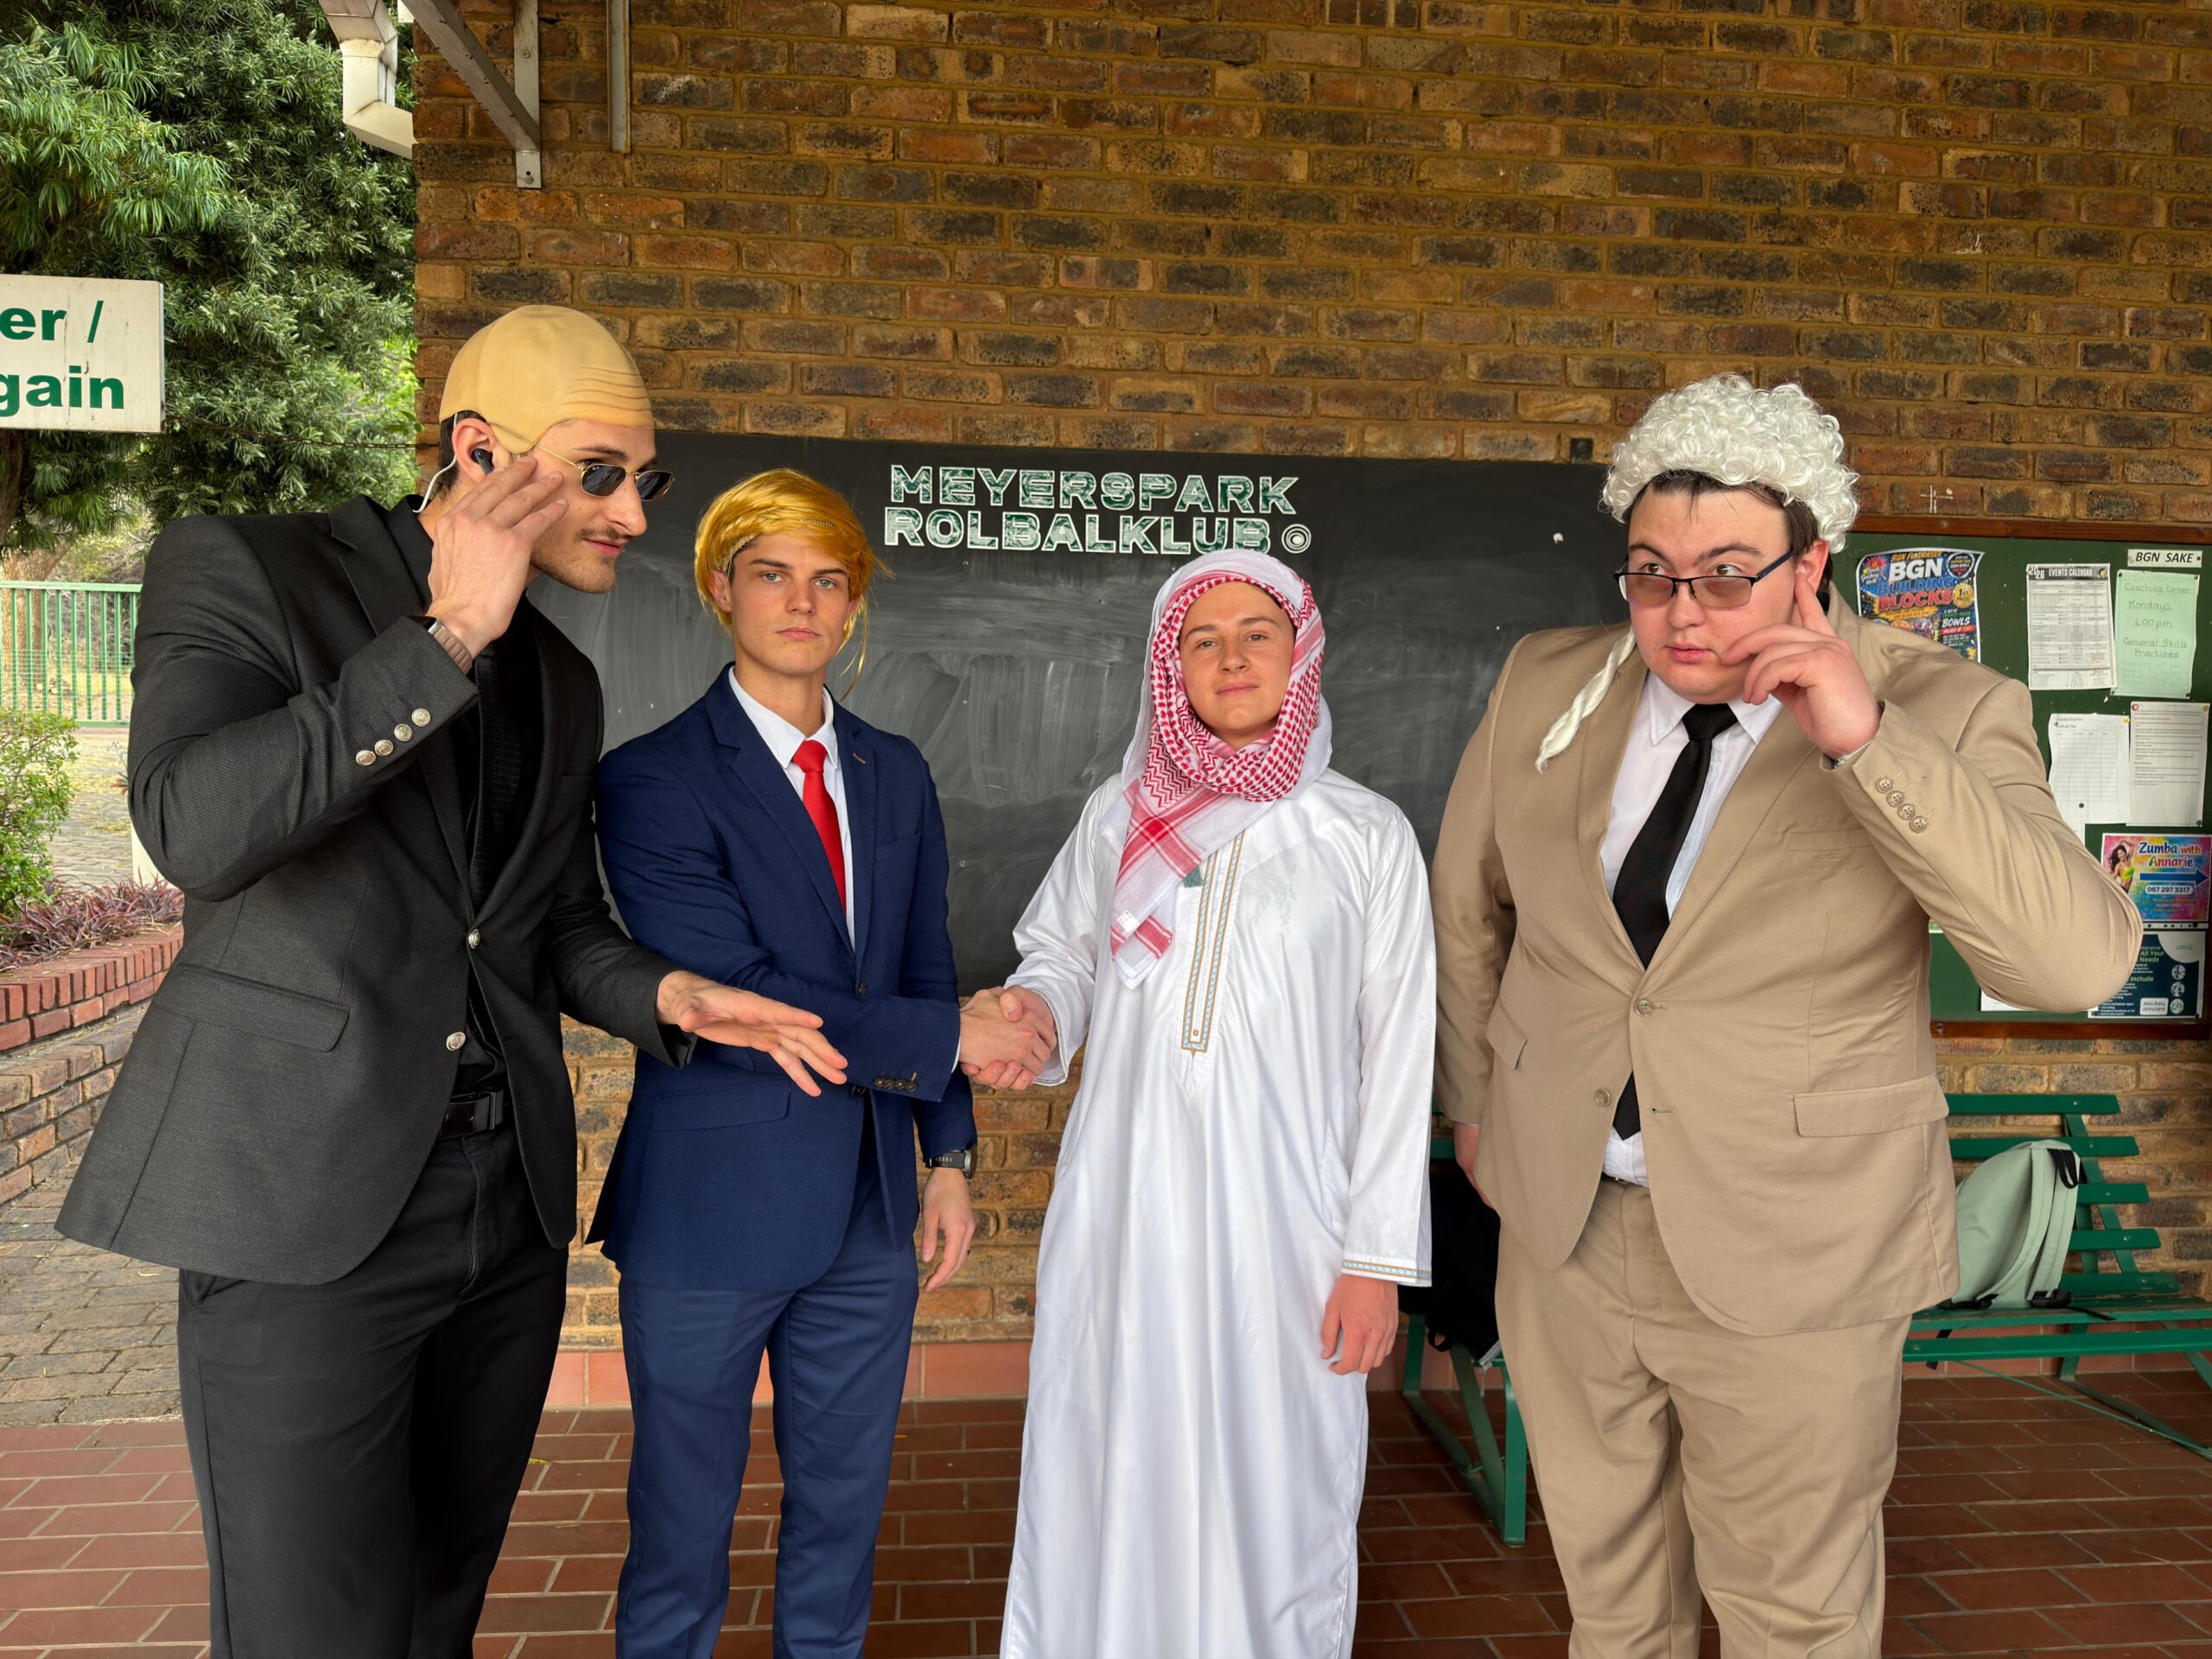
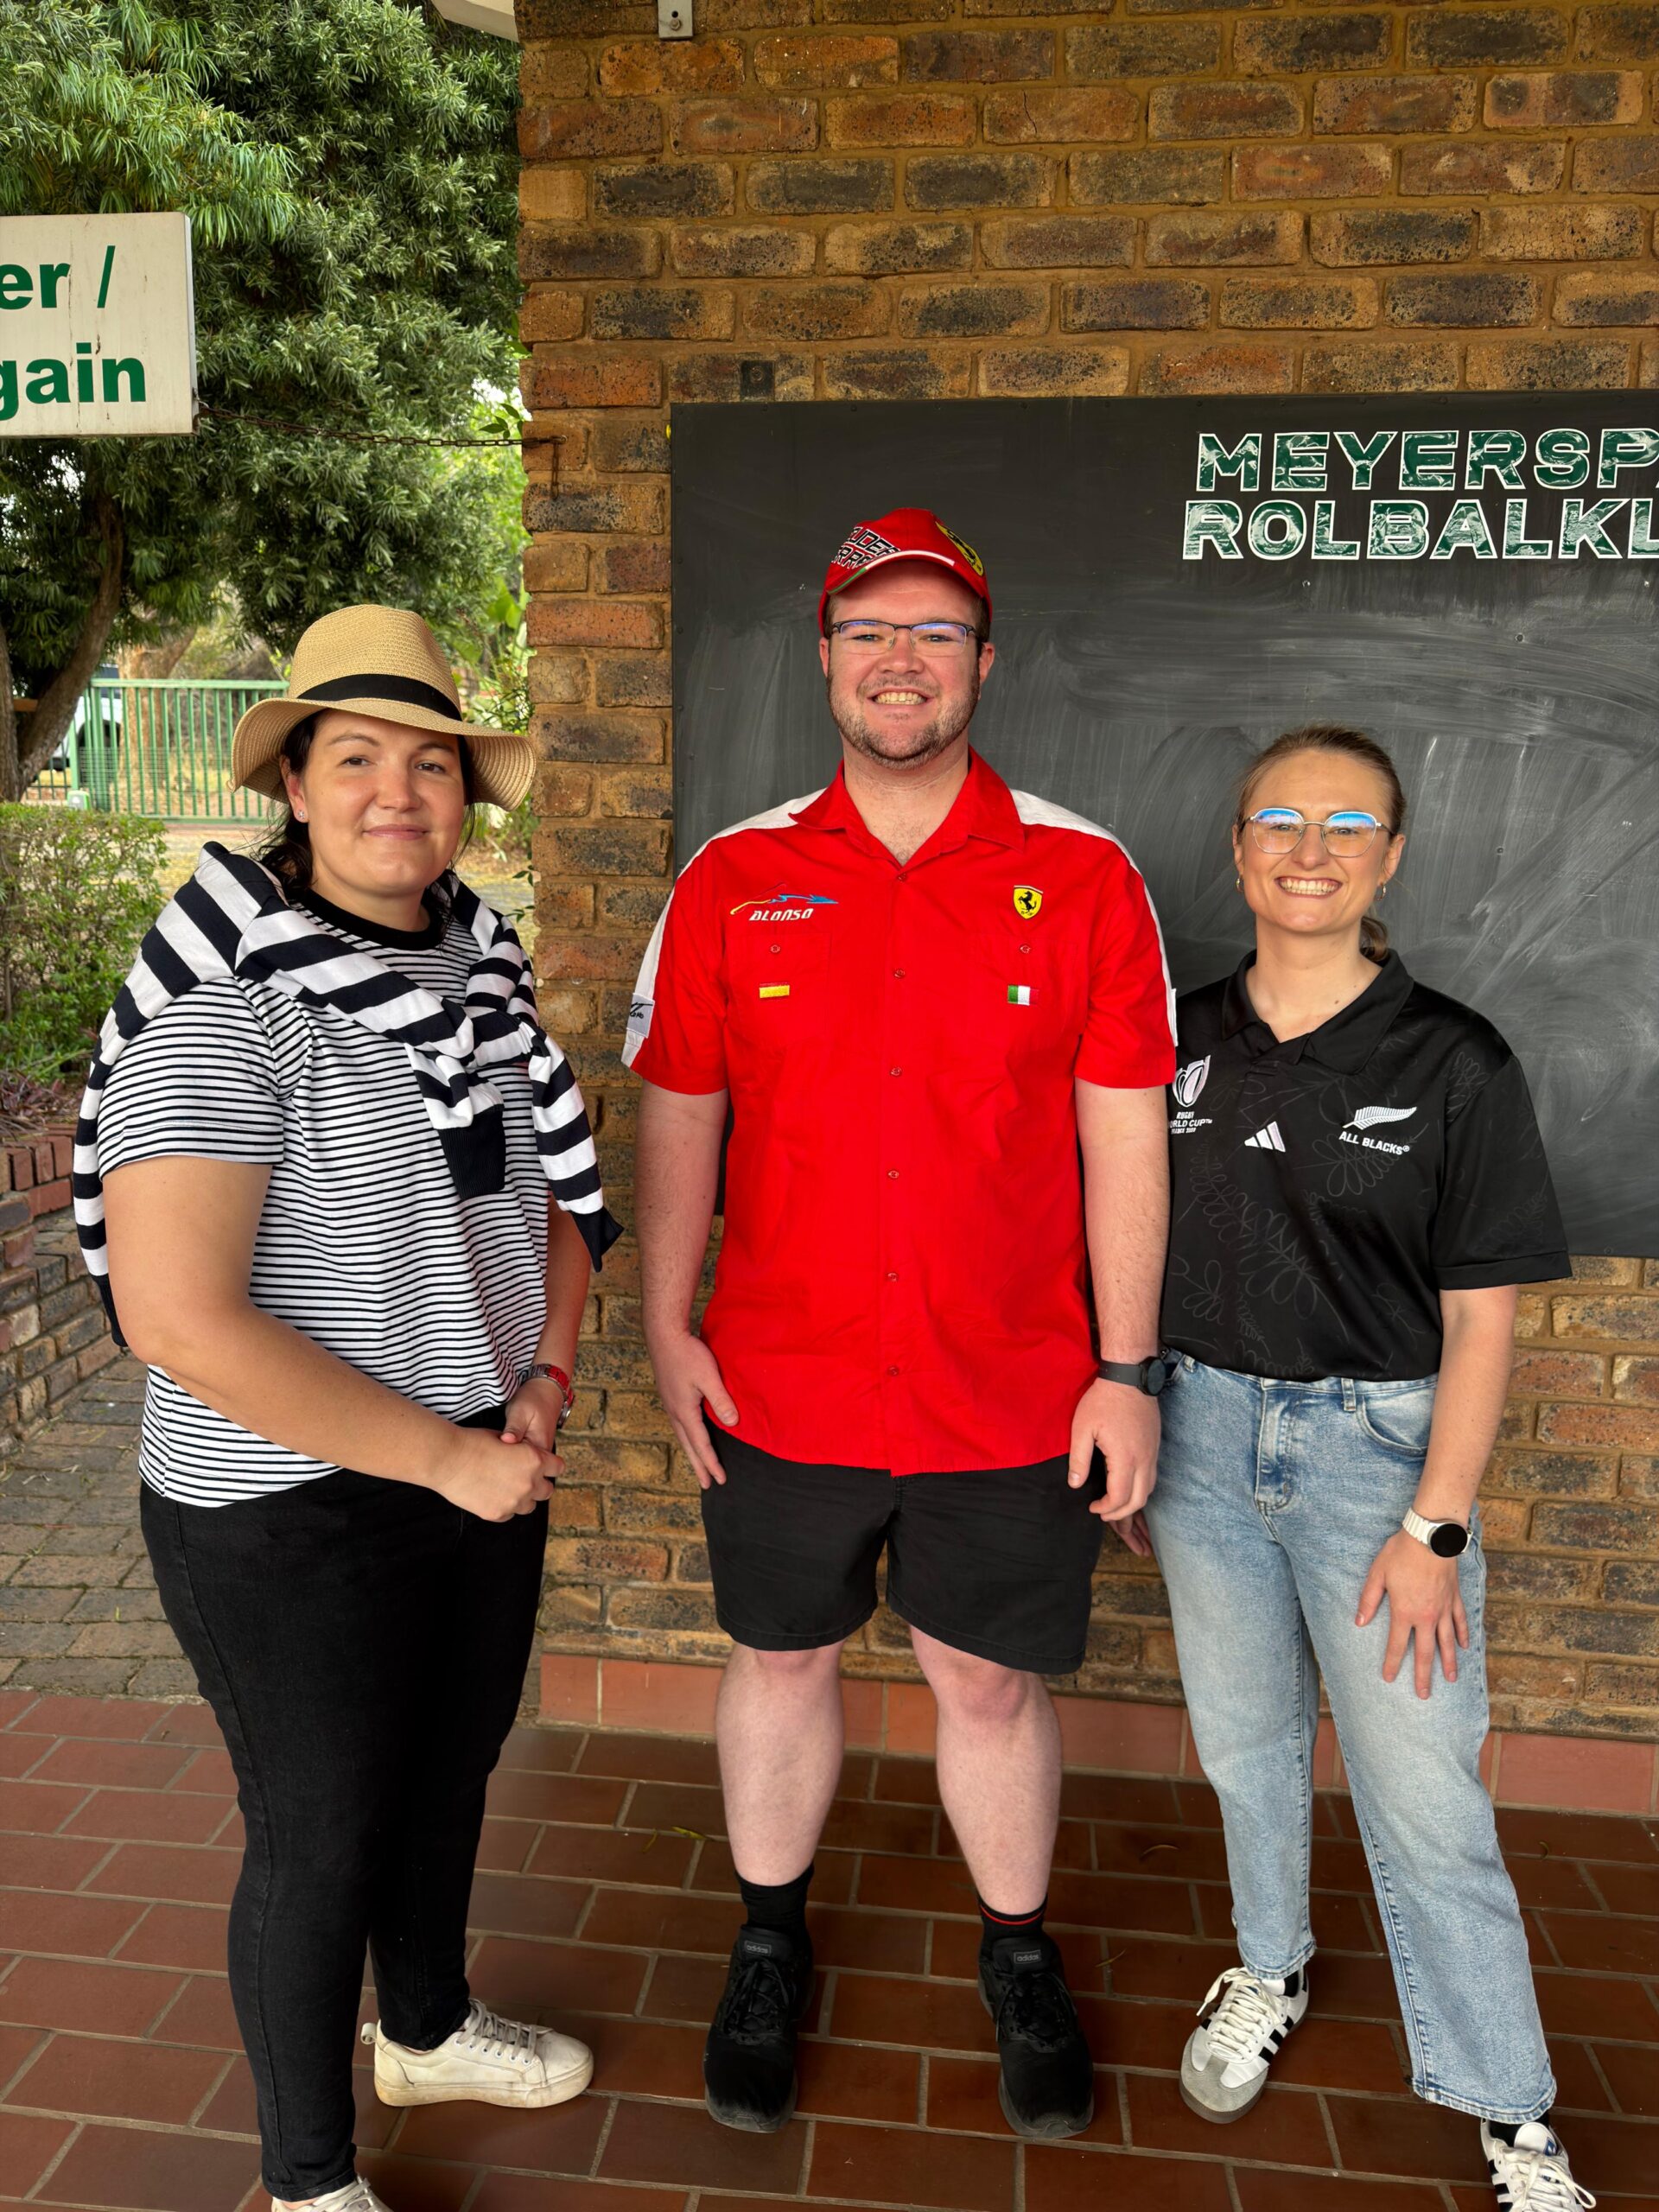
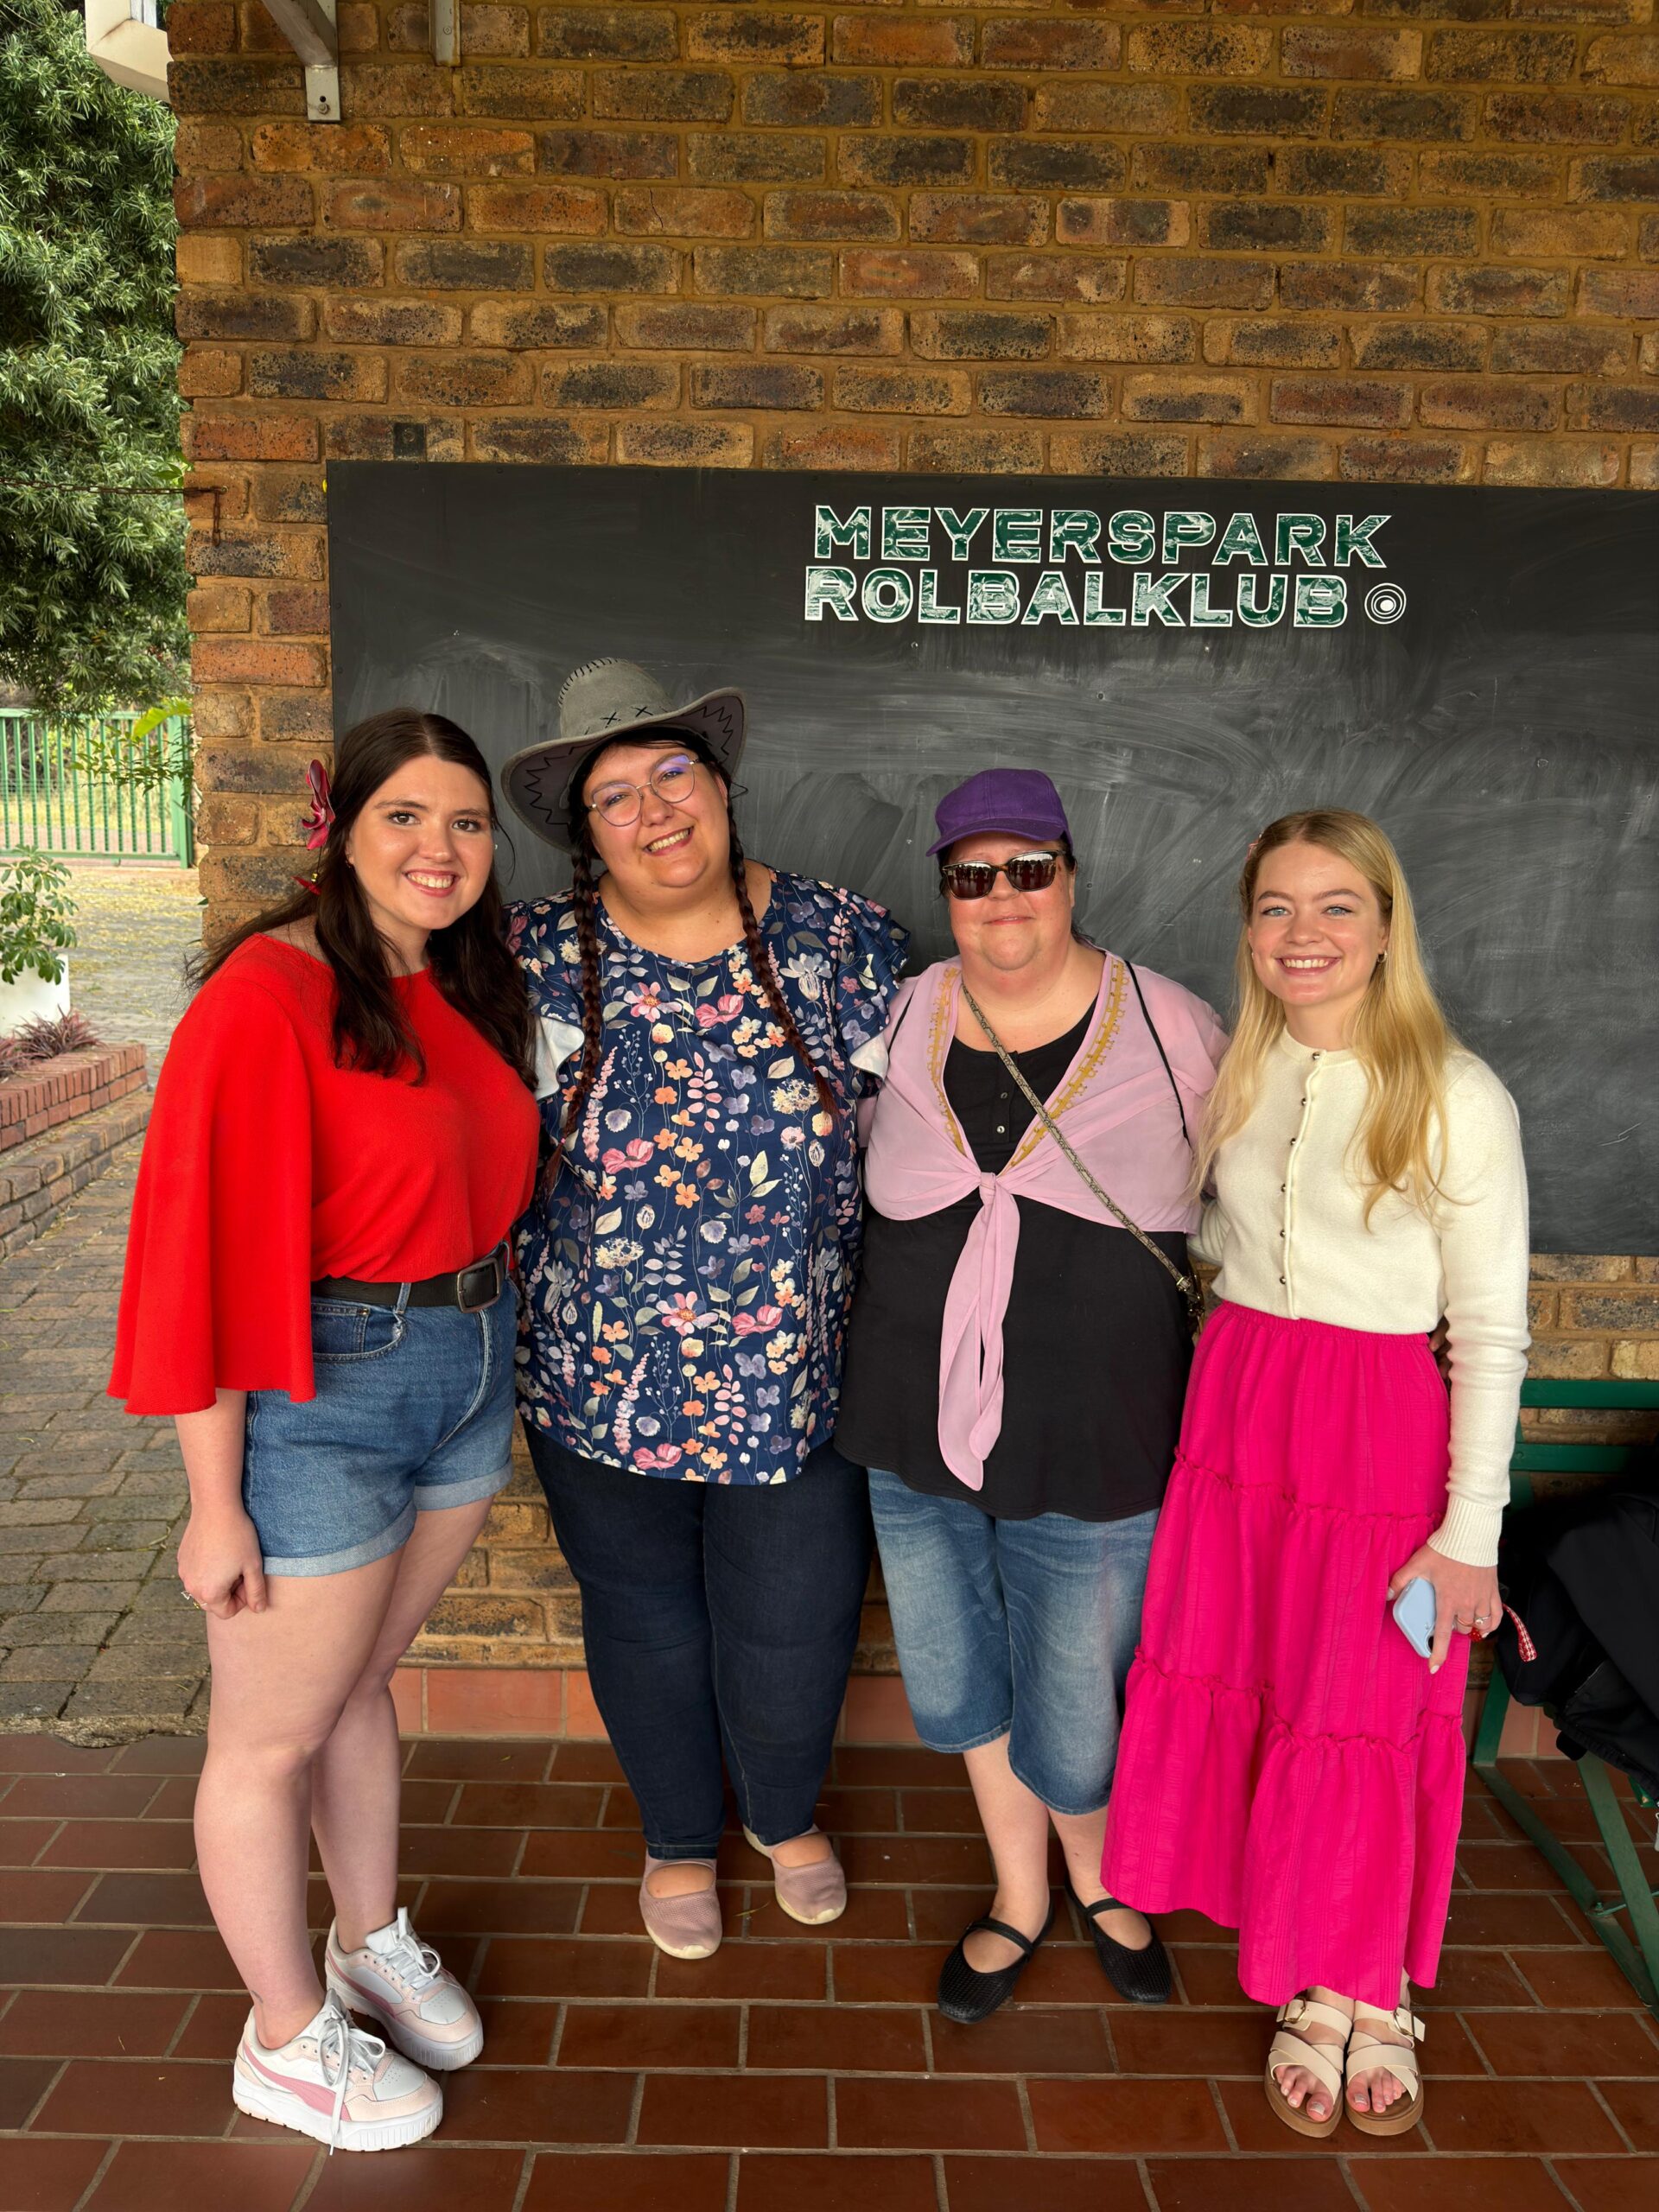
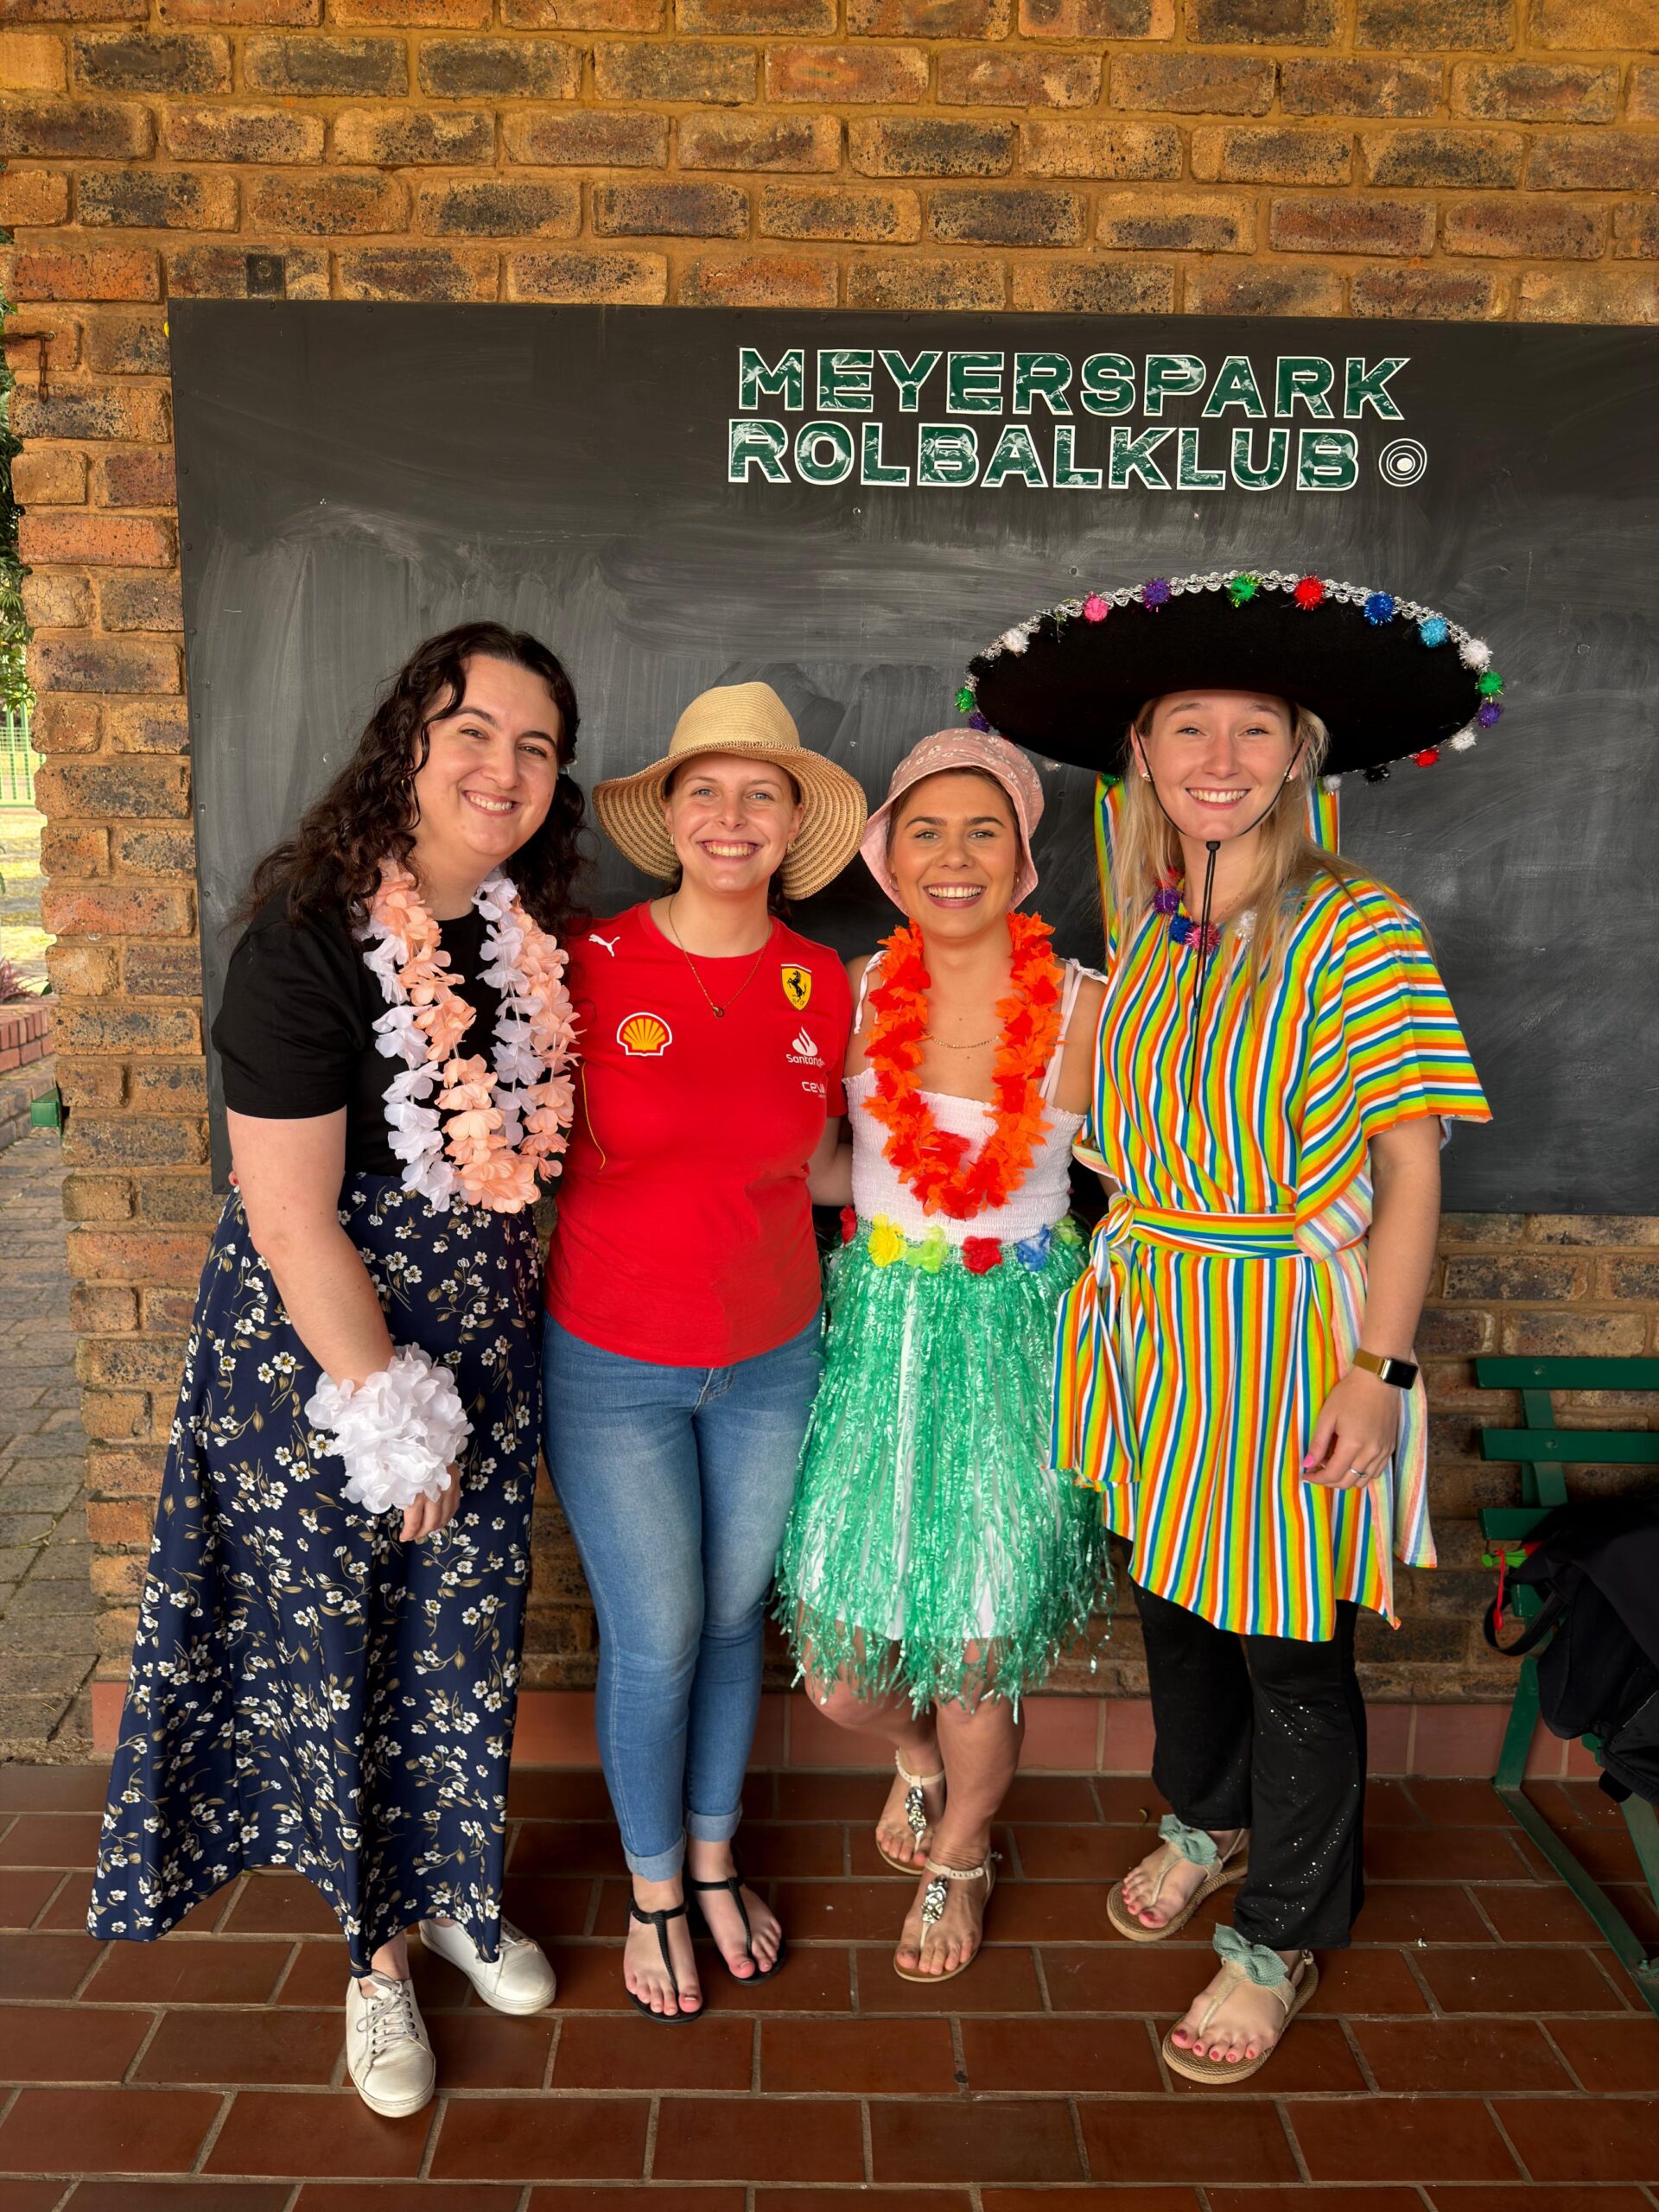
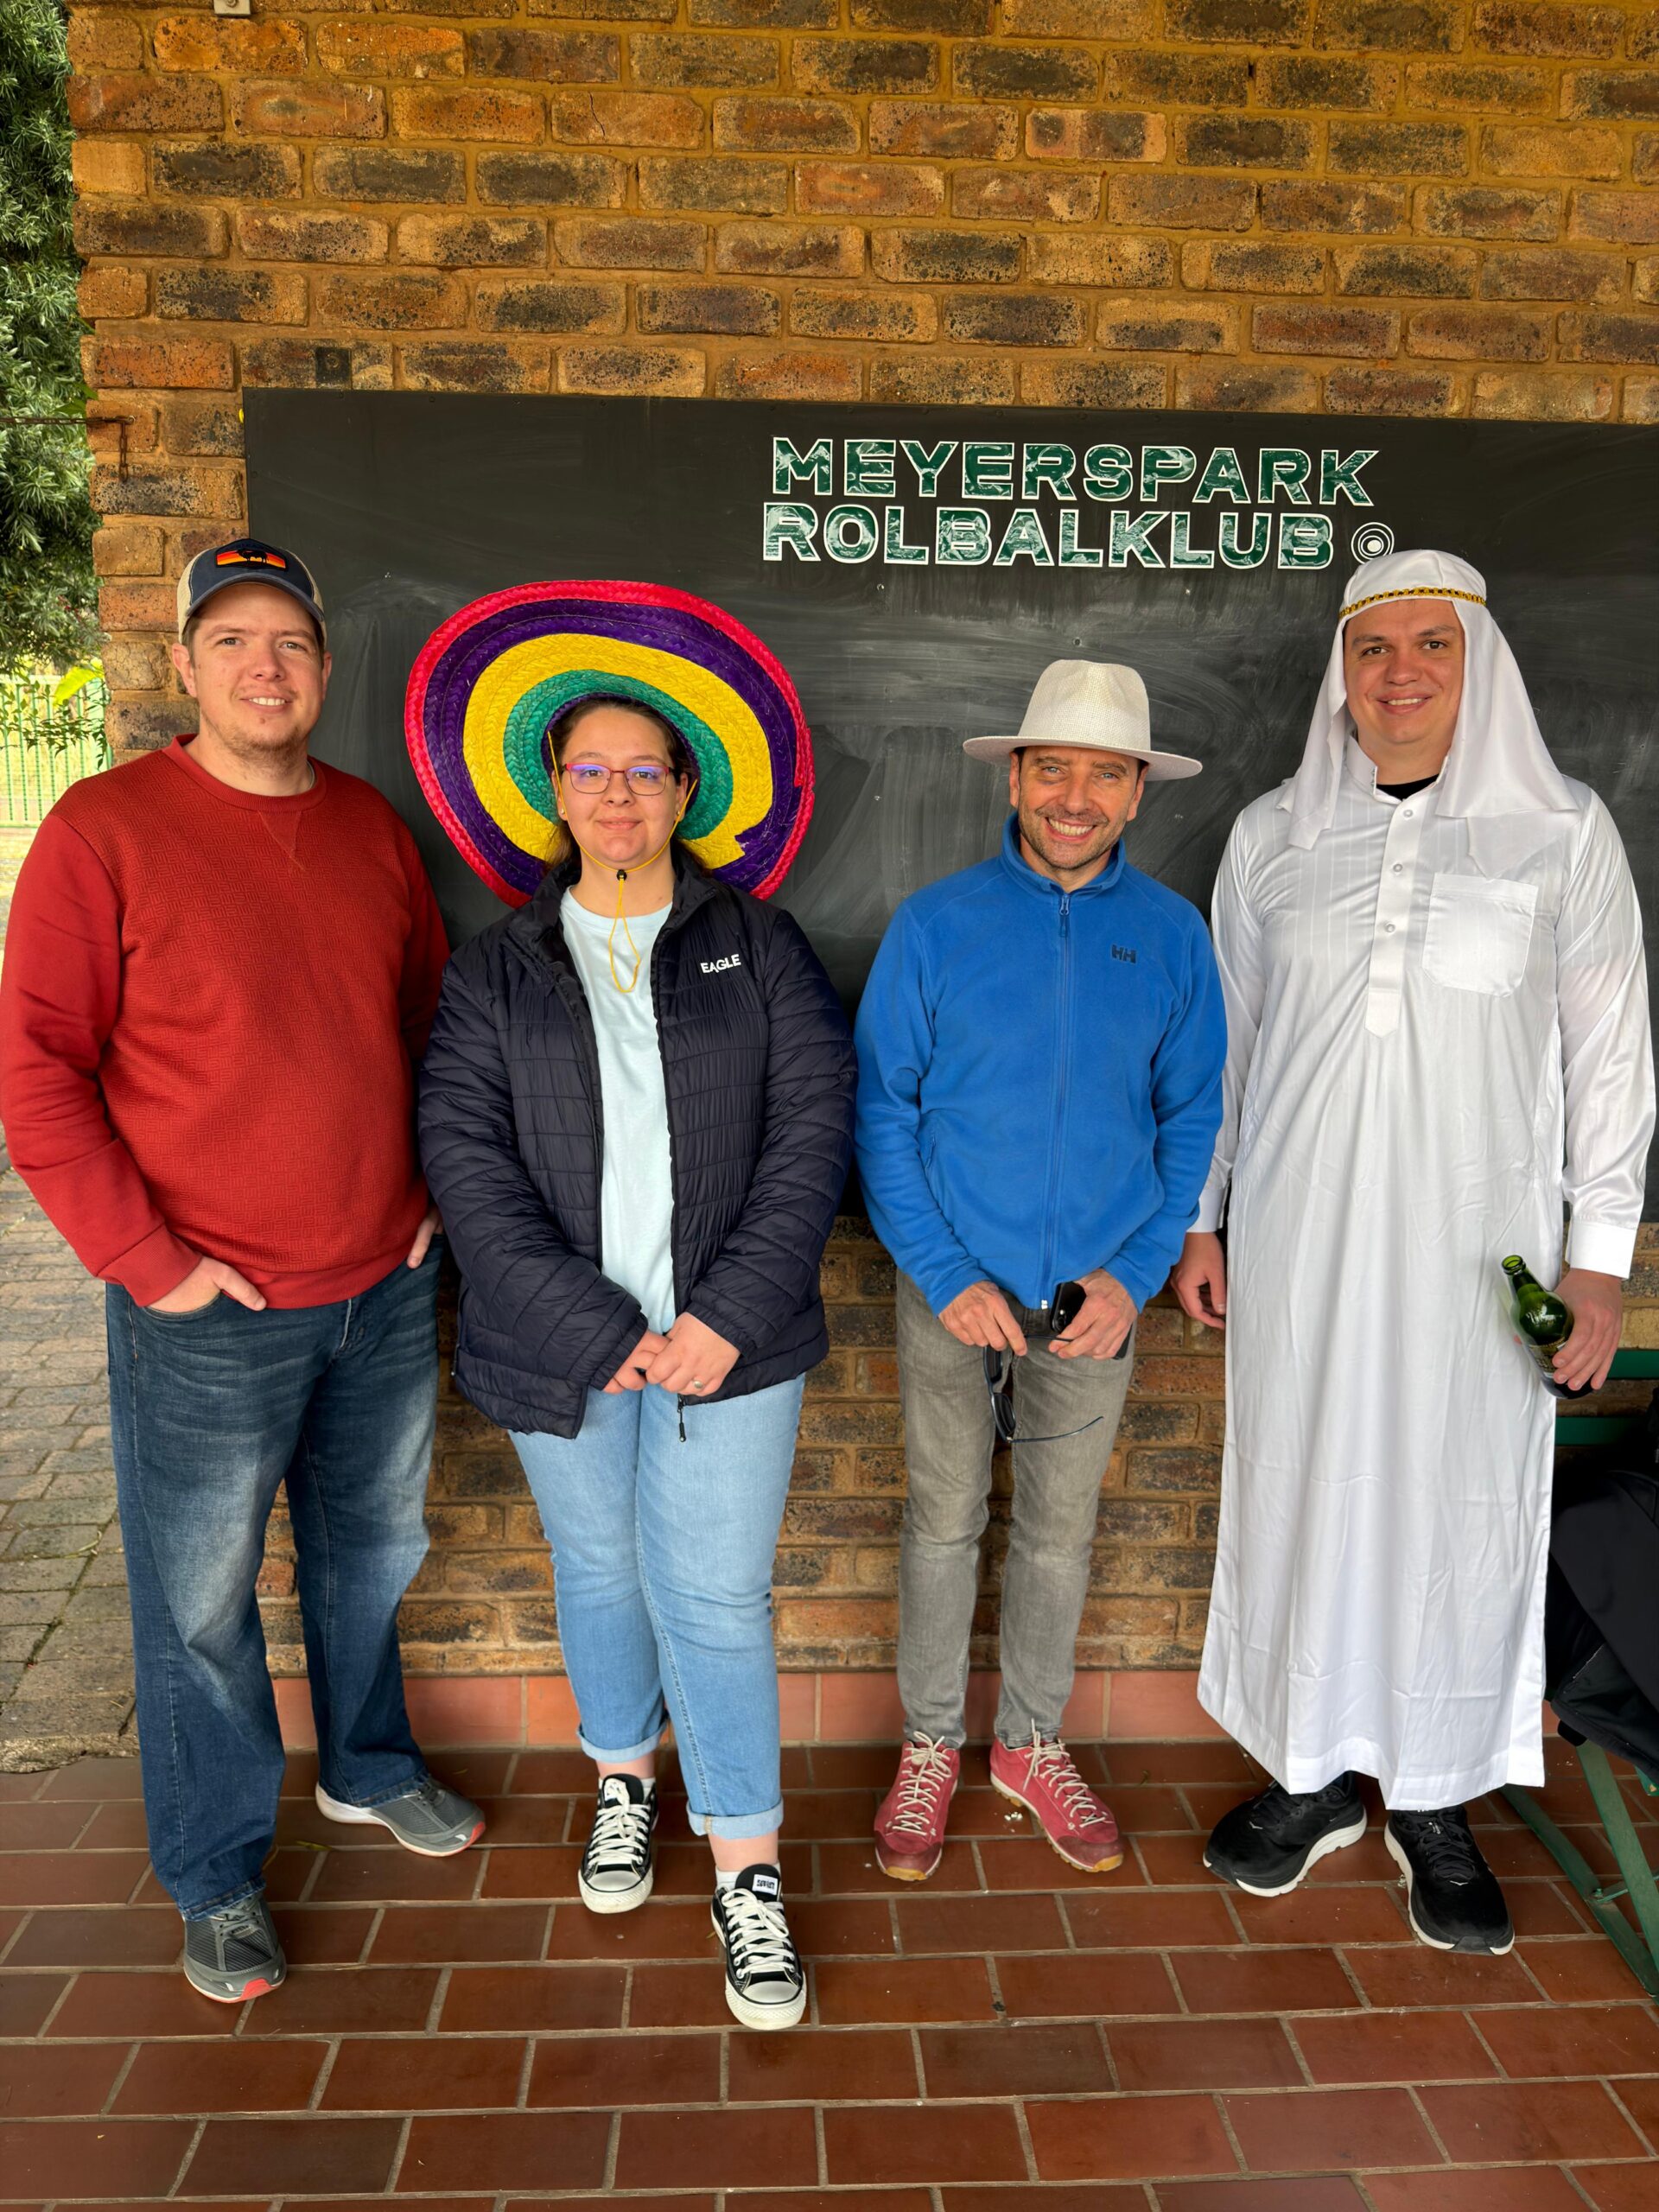
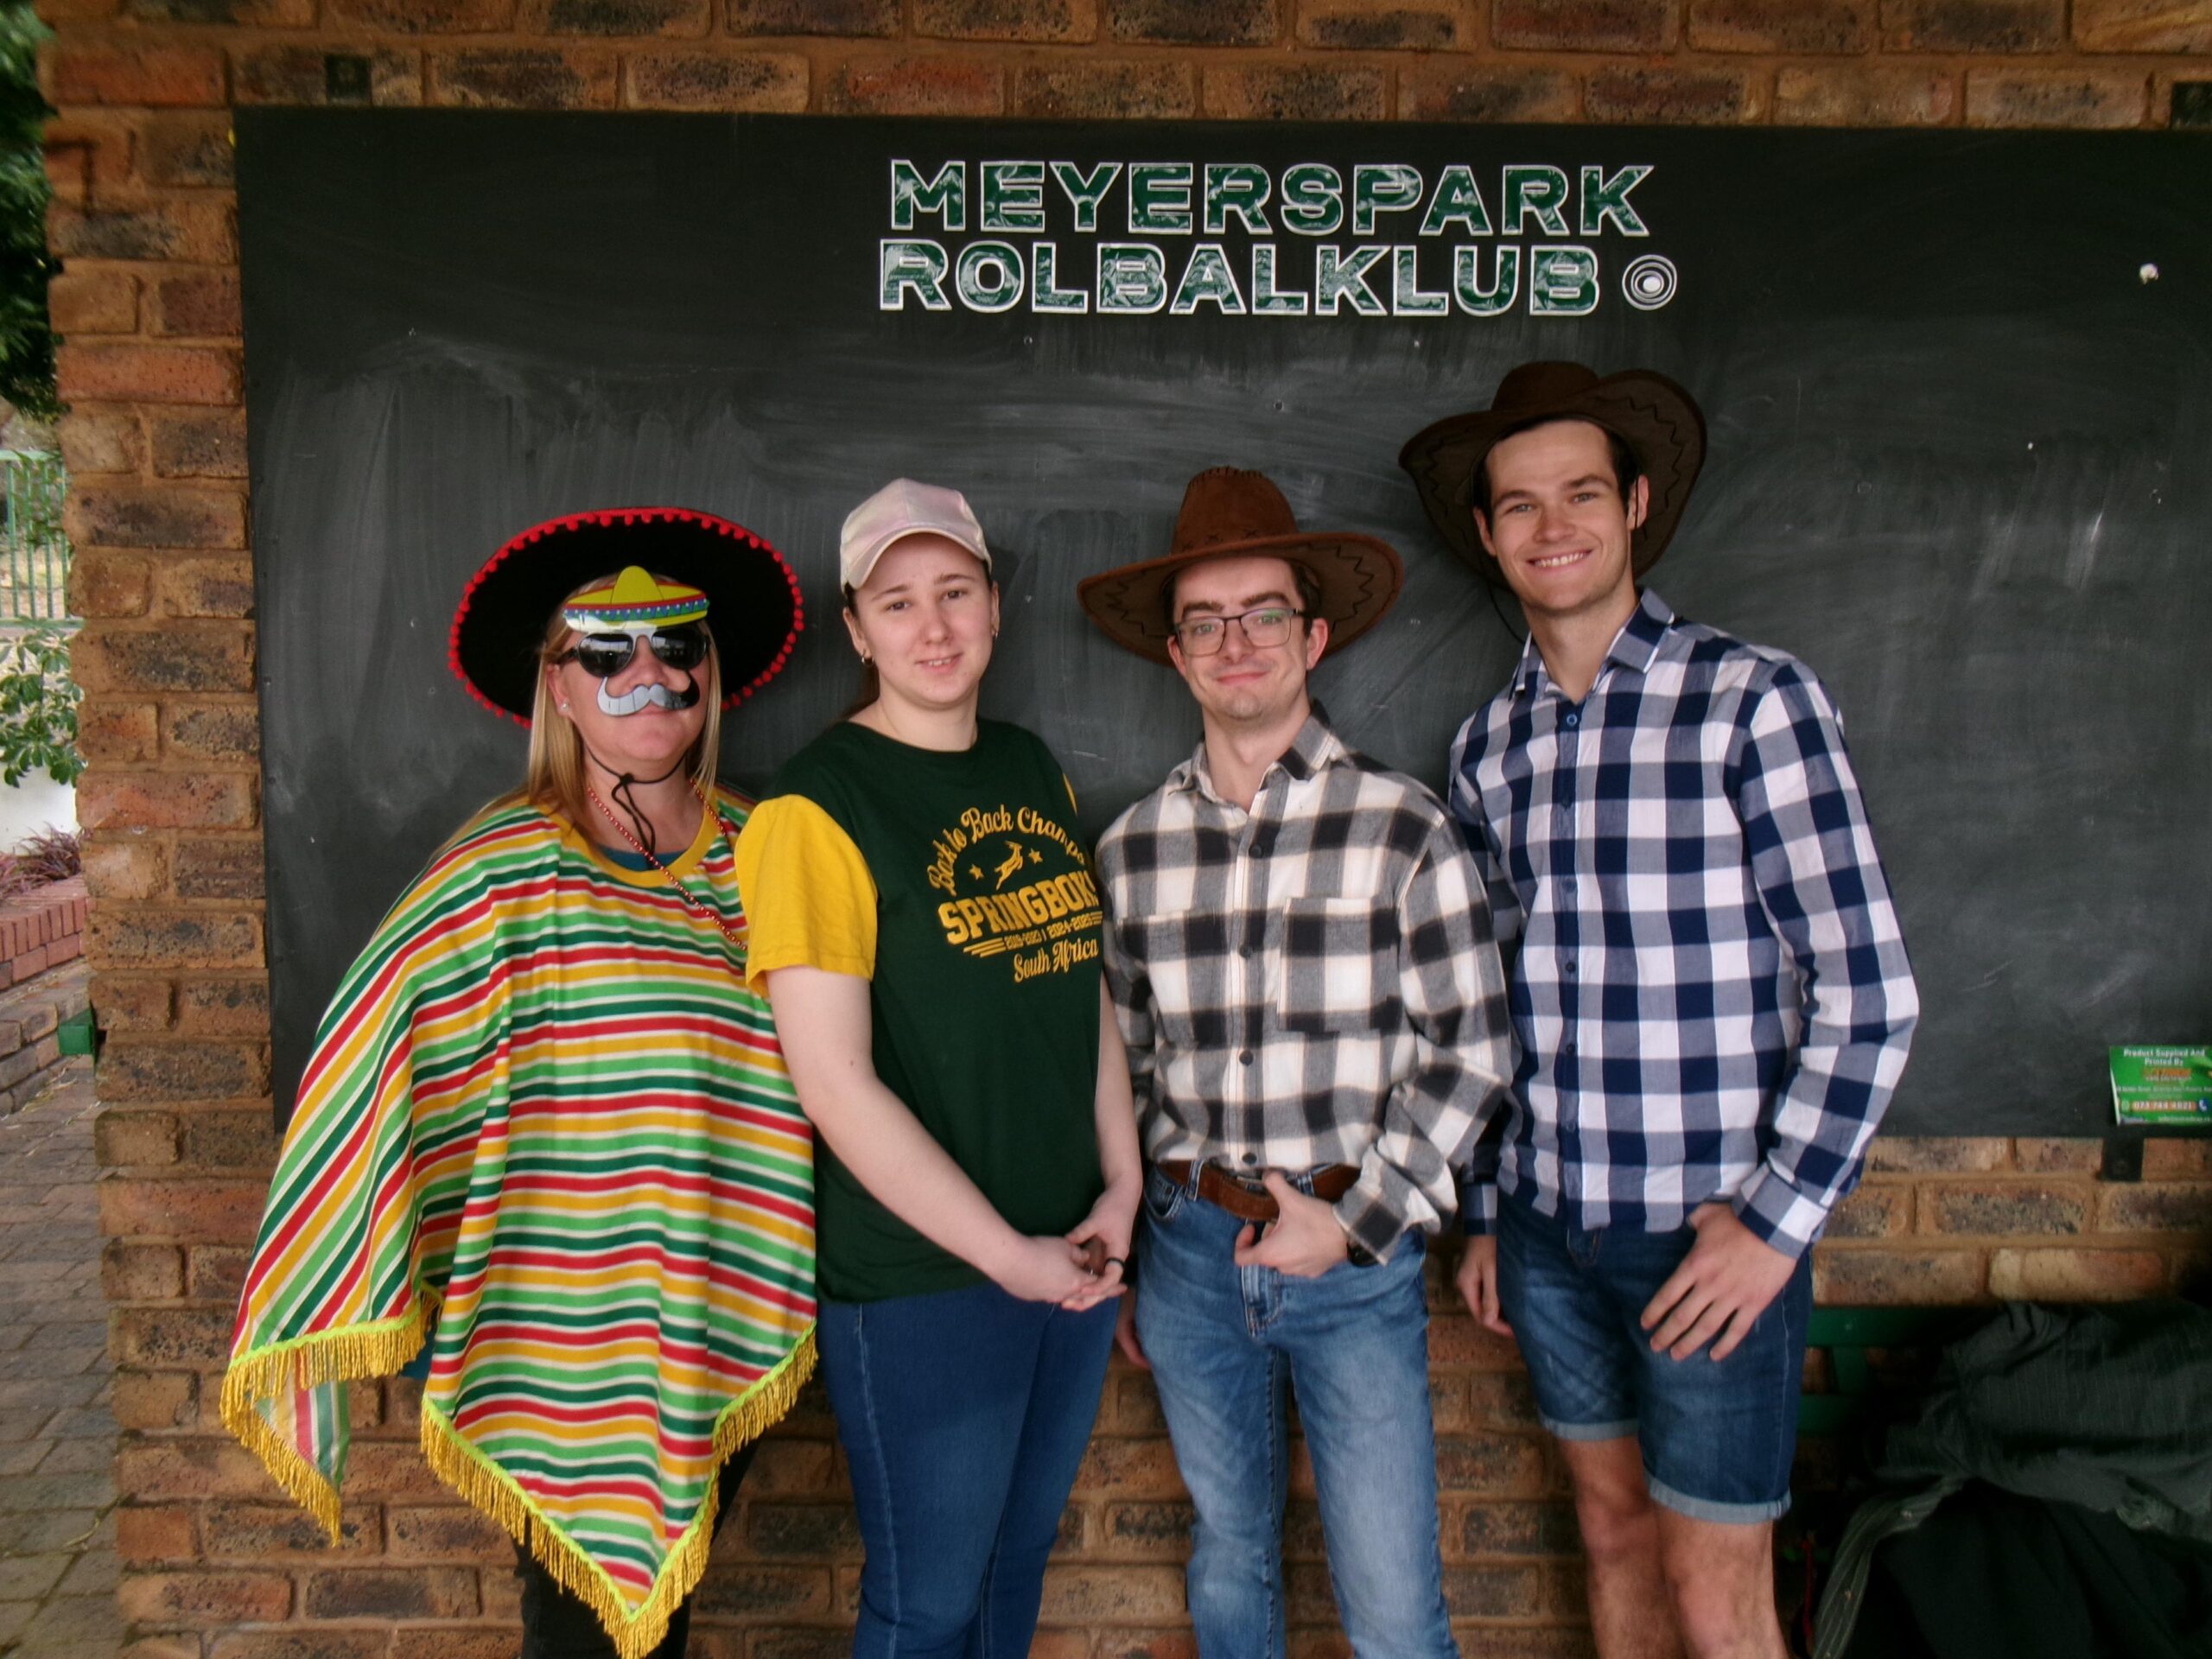
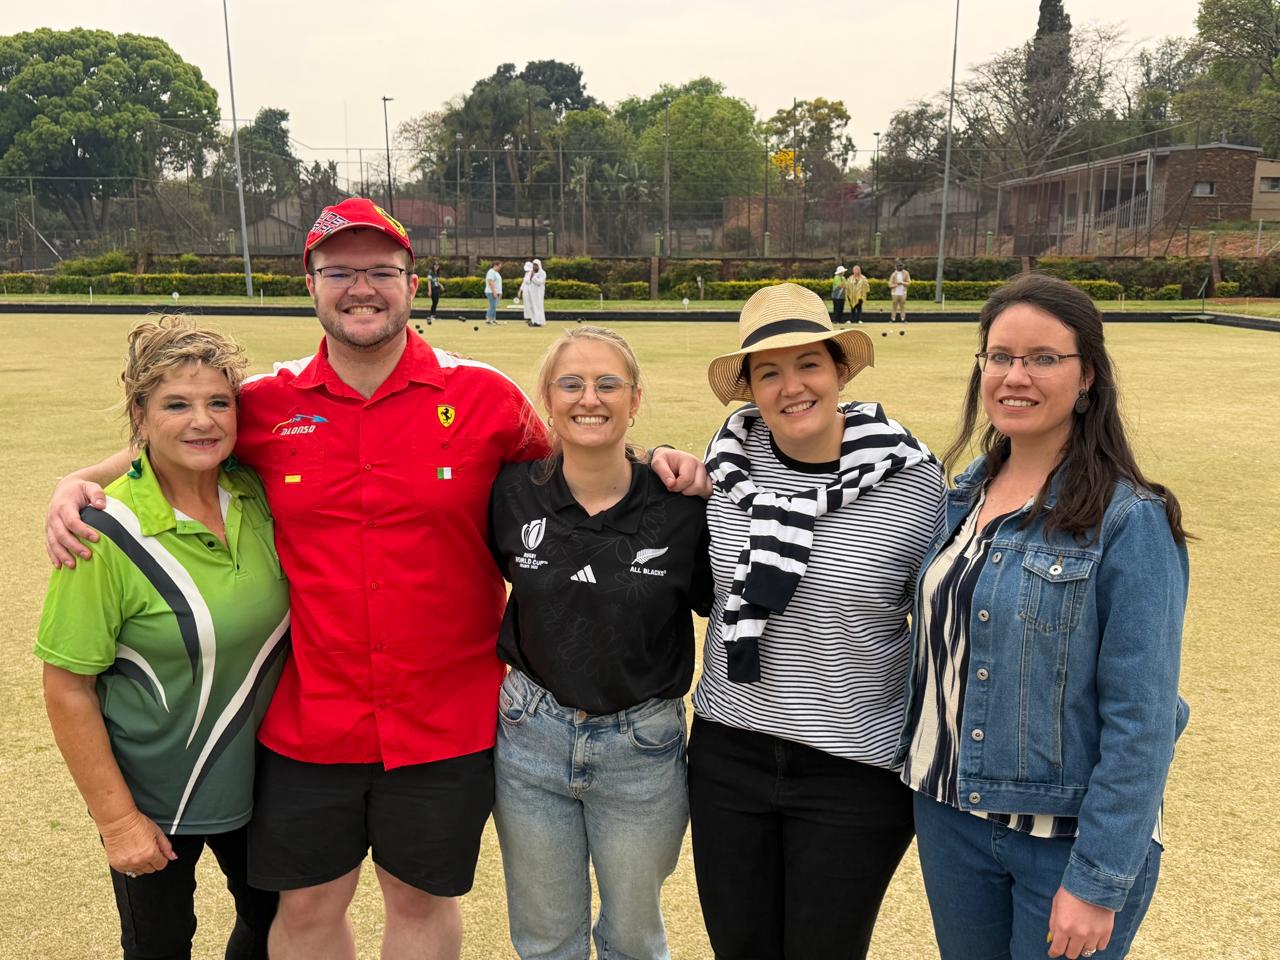
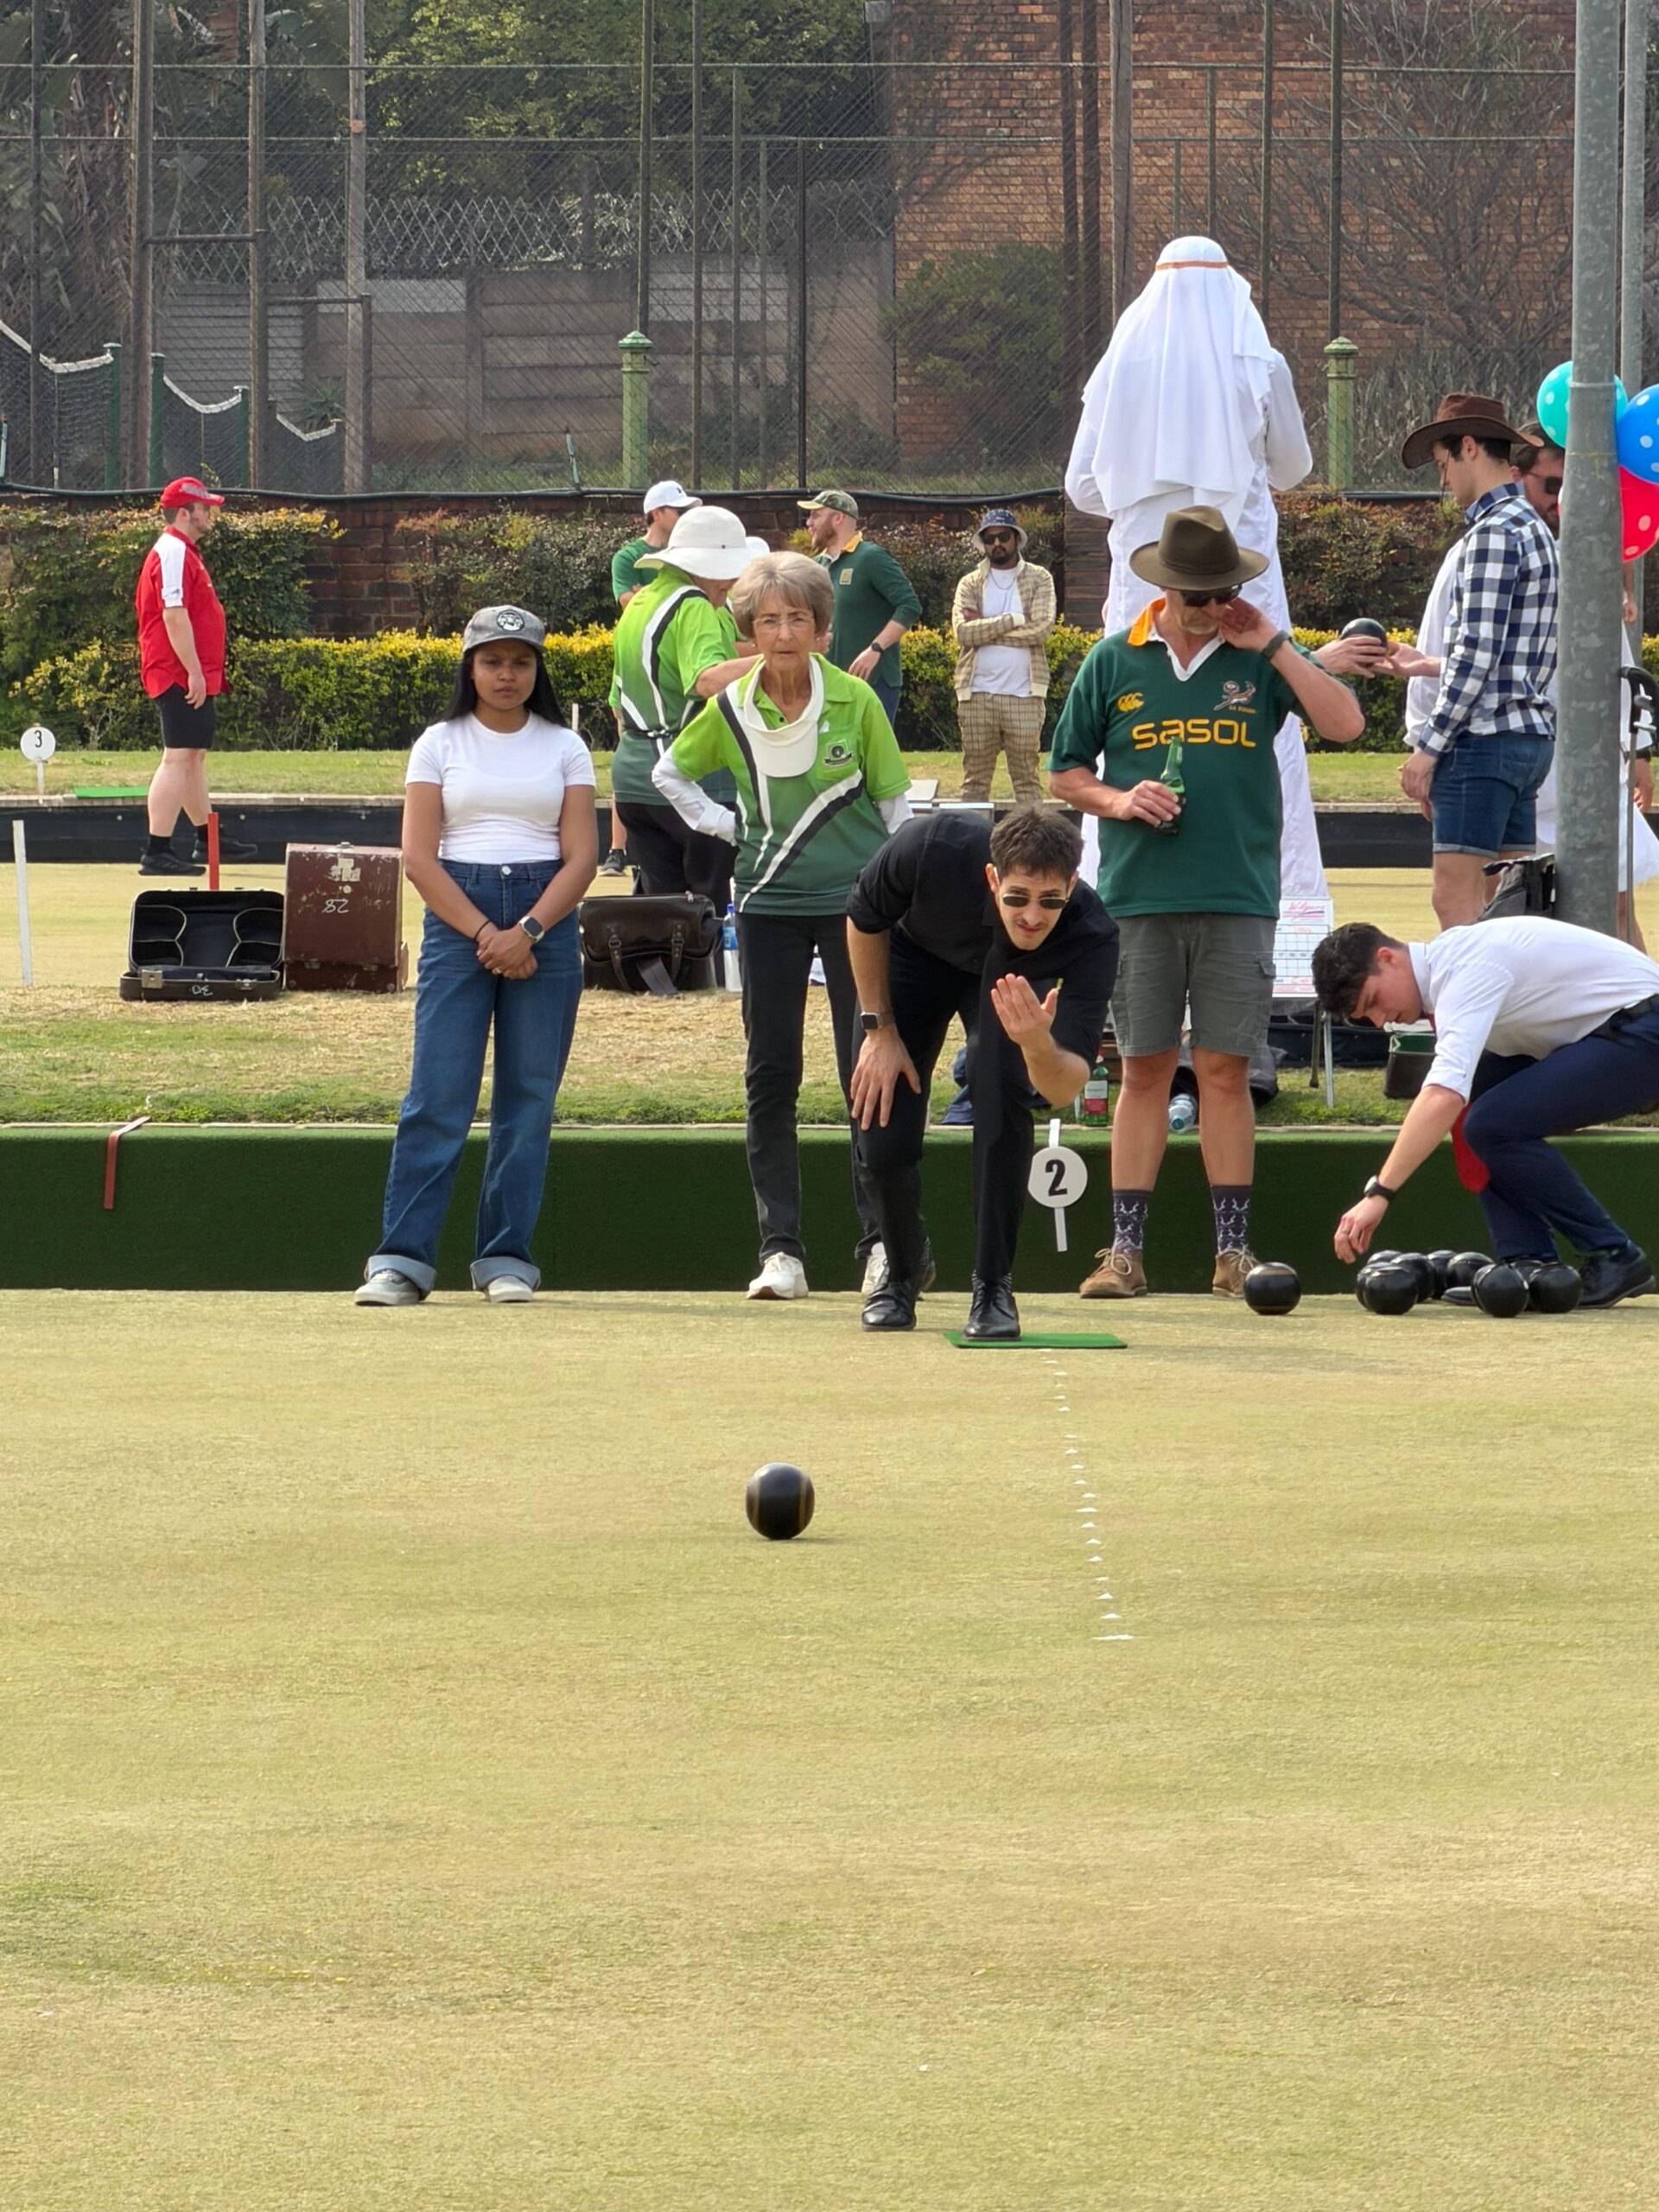
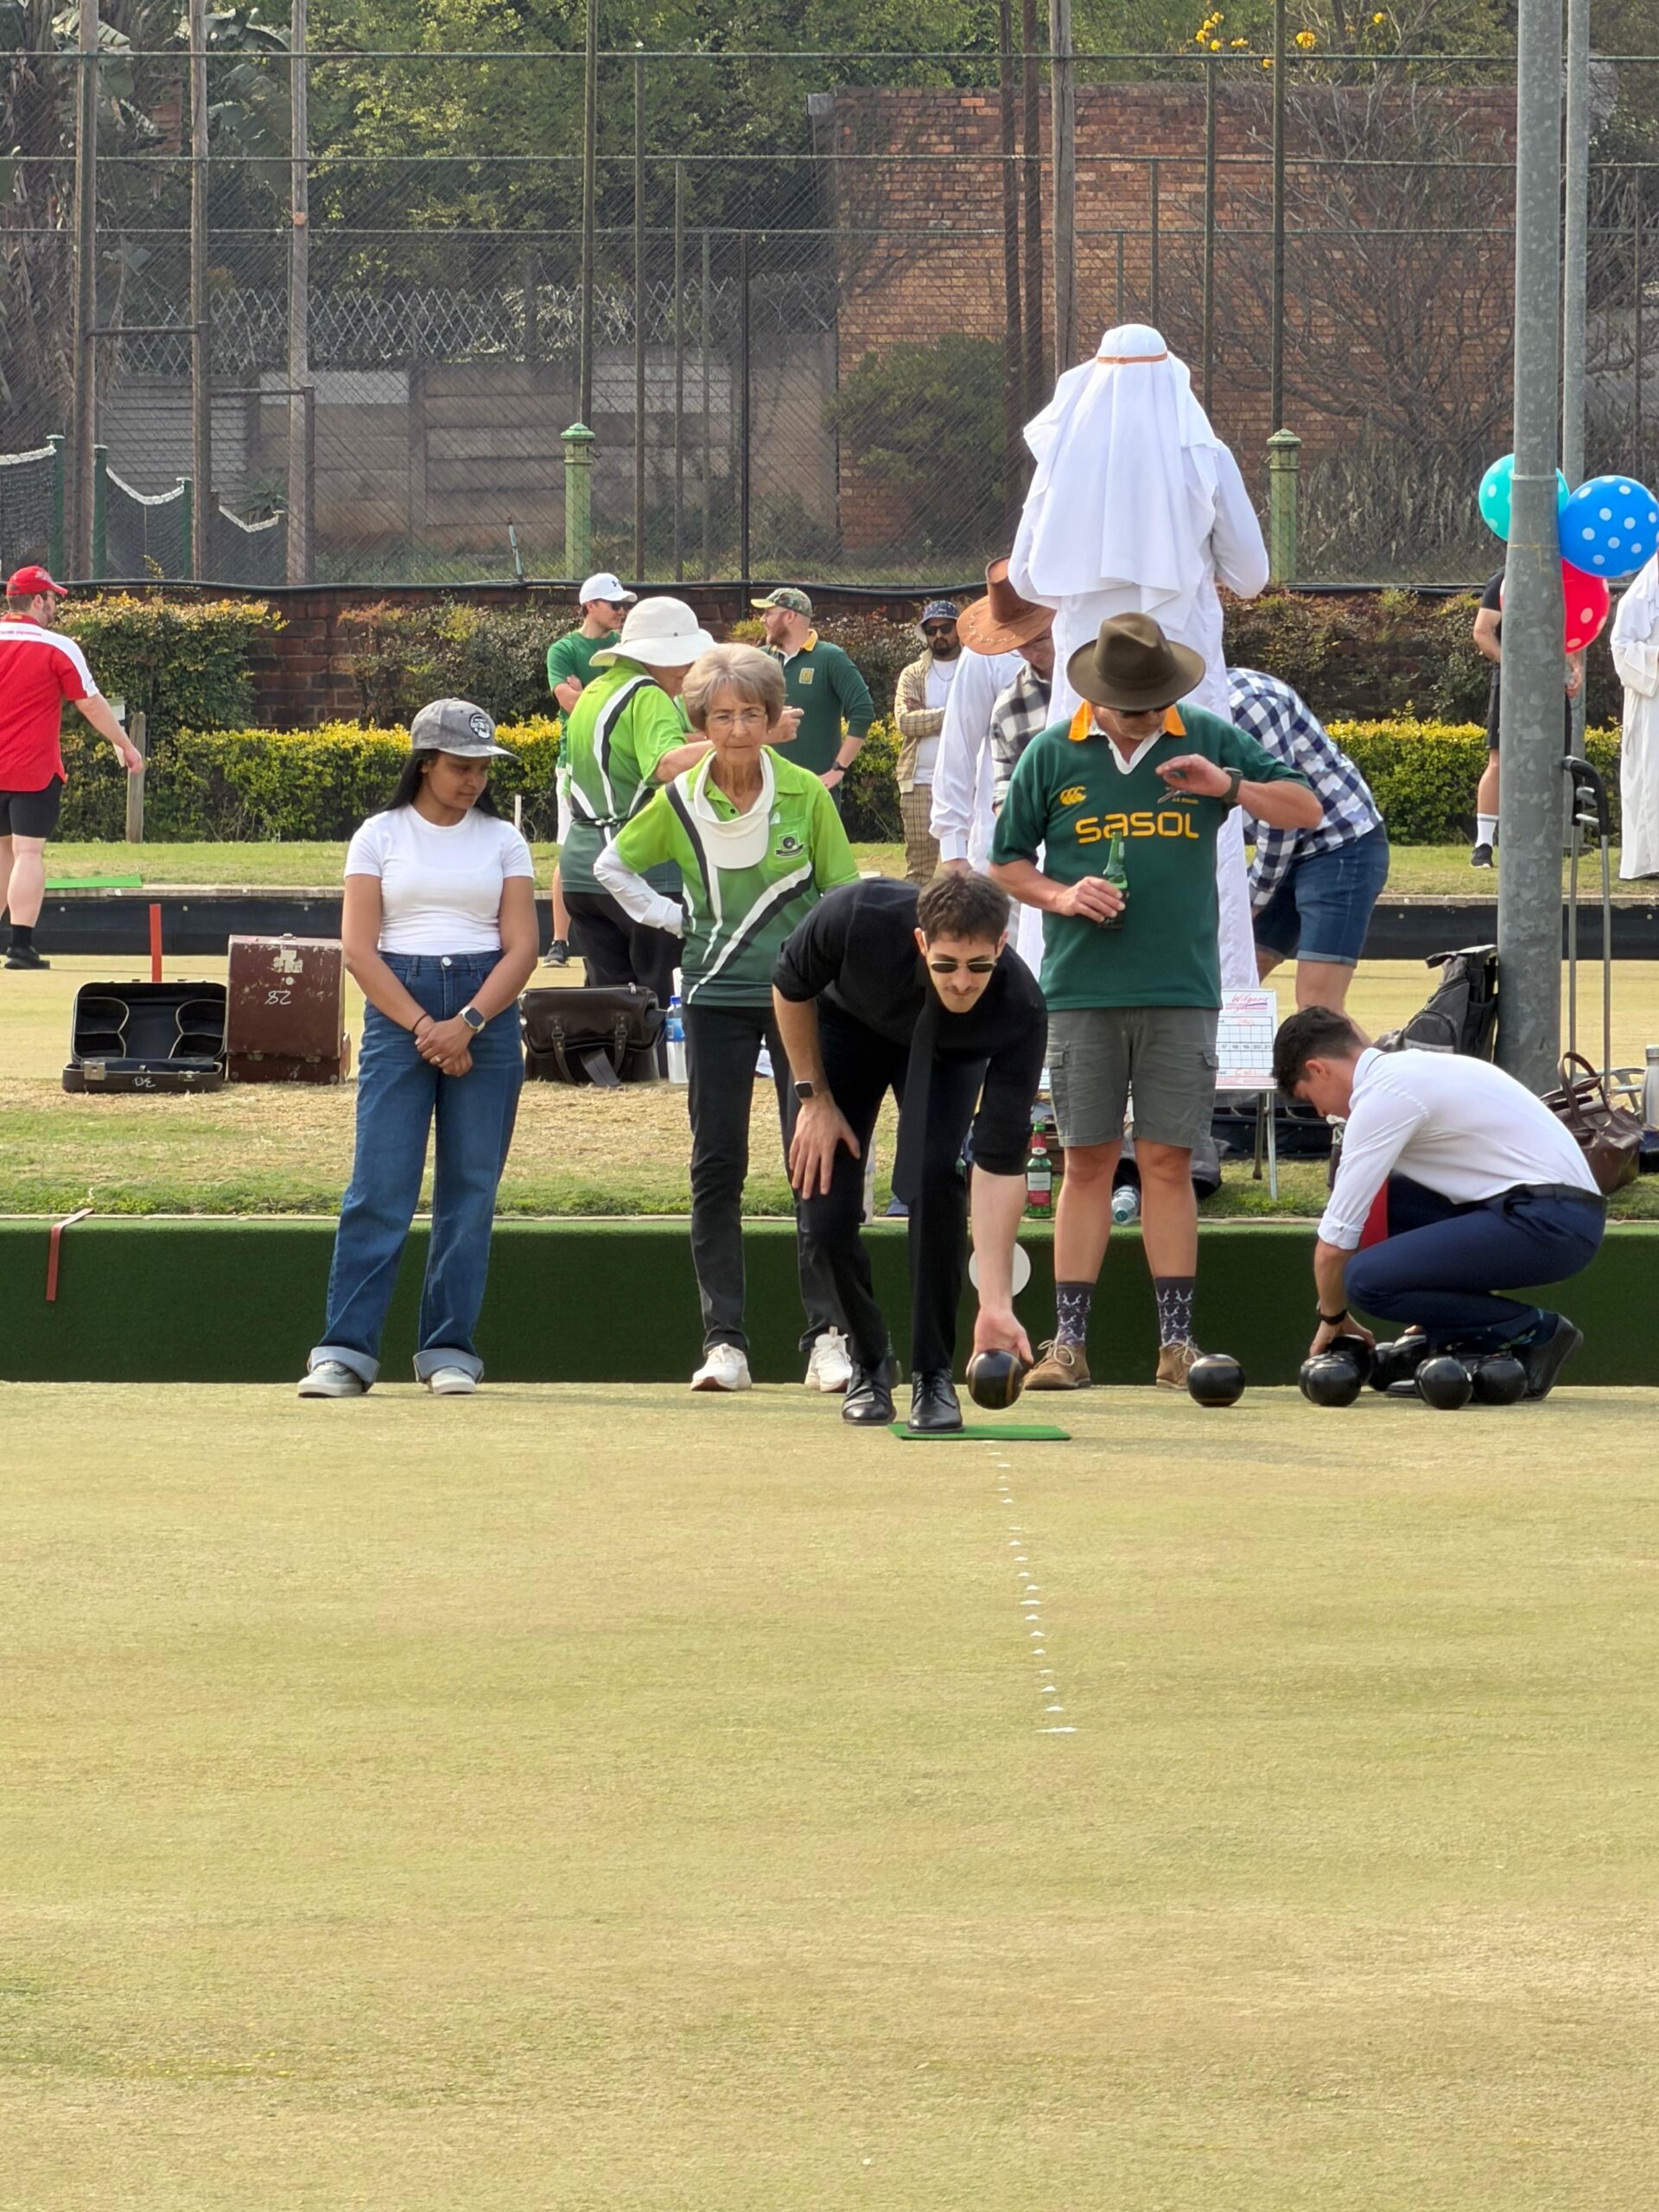
Who says you need a passport to travel the world? On 4 September, the Logista team proved that all you really need is a little creativity, a great sense of humour and some fantastic colleagues! Our “Around the World” themed bowls day brought a wonderful splash of international colour to the bowling green, with staff dressing up to represent countries of their choice. The outfits, the laughter and the enthusiasm made for a wonderfully festive atmosphere, with the Best Dressed competition adding an extra touch of friendly rivalry!

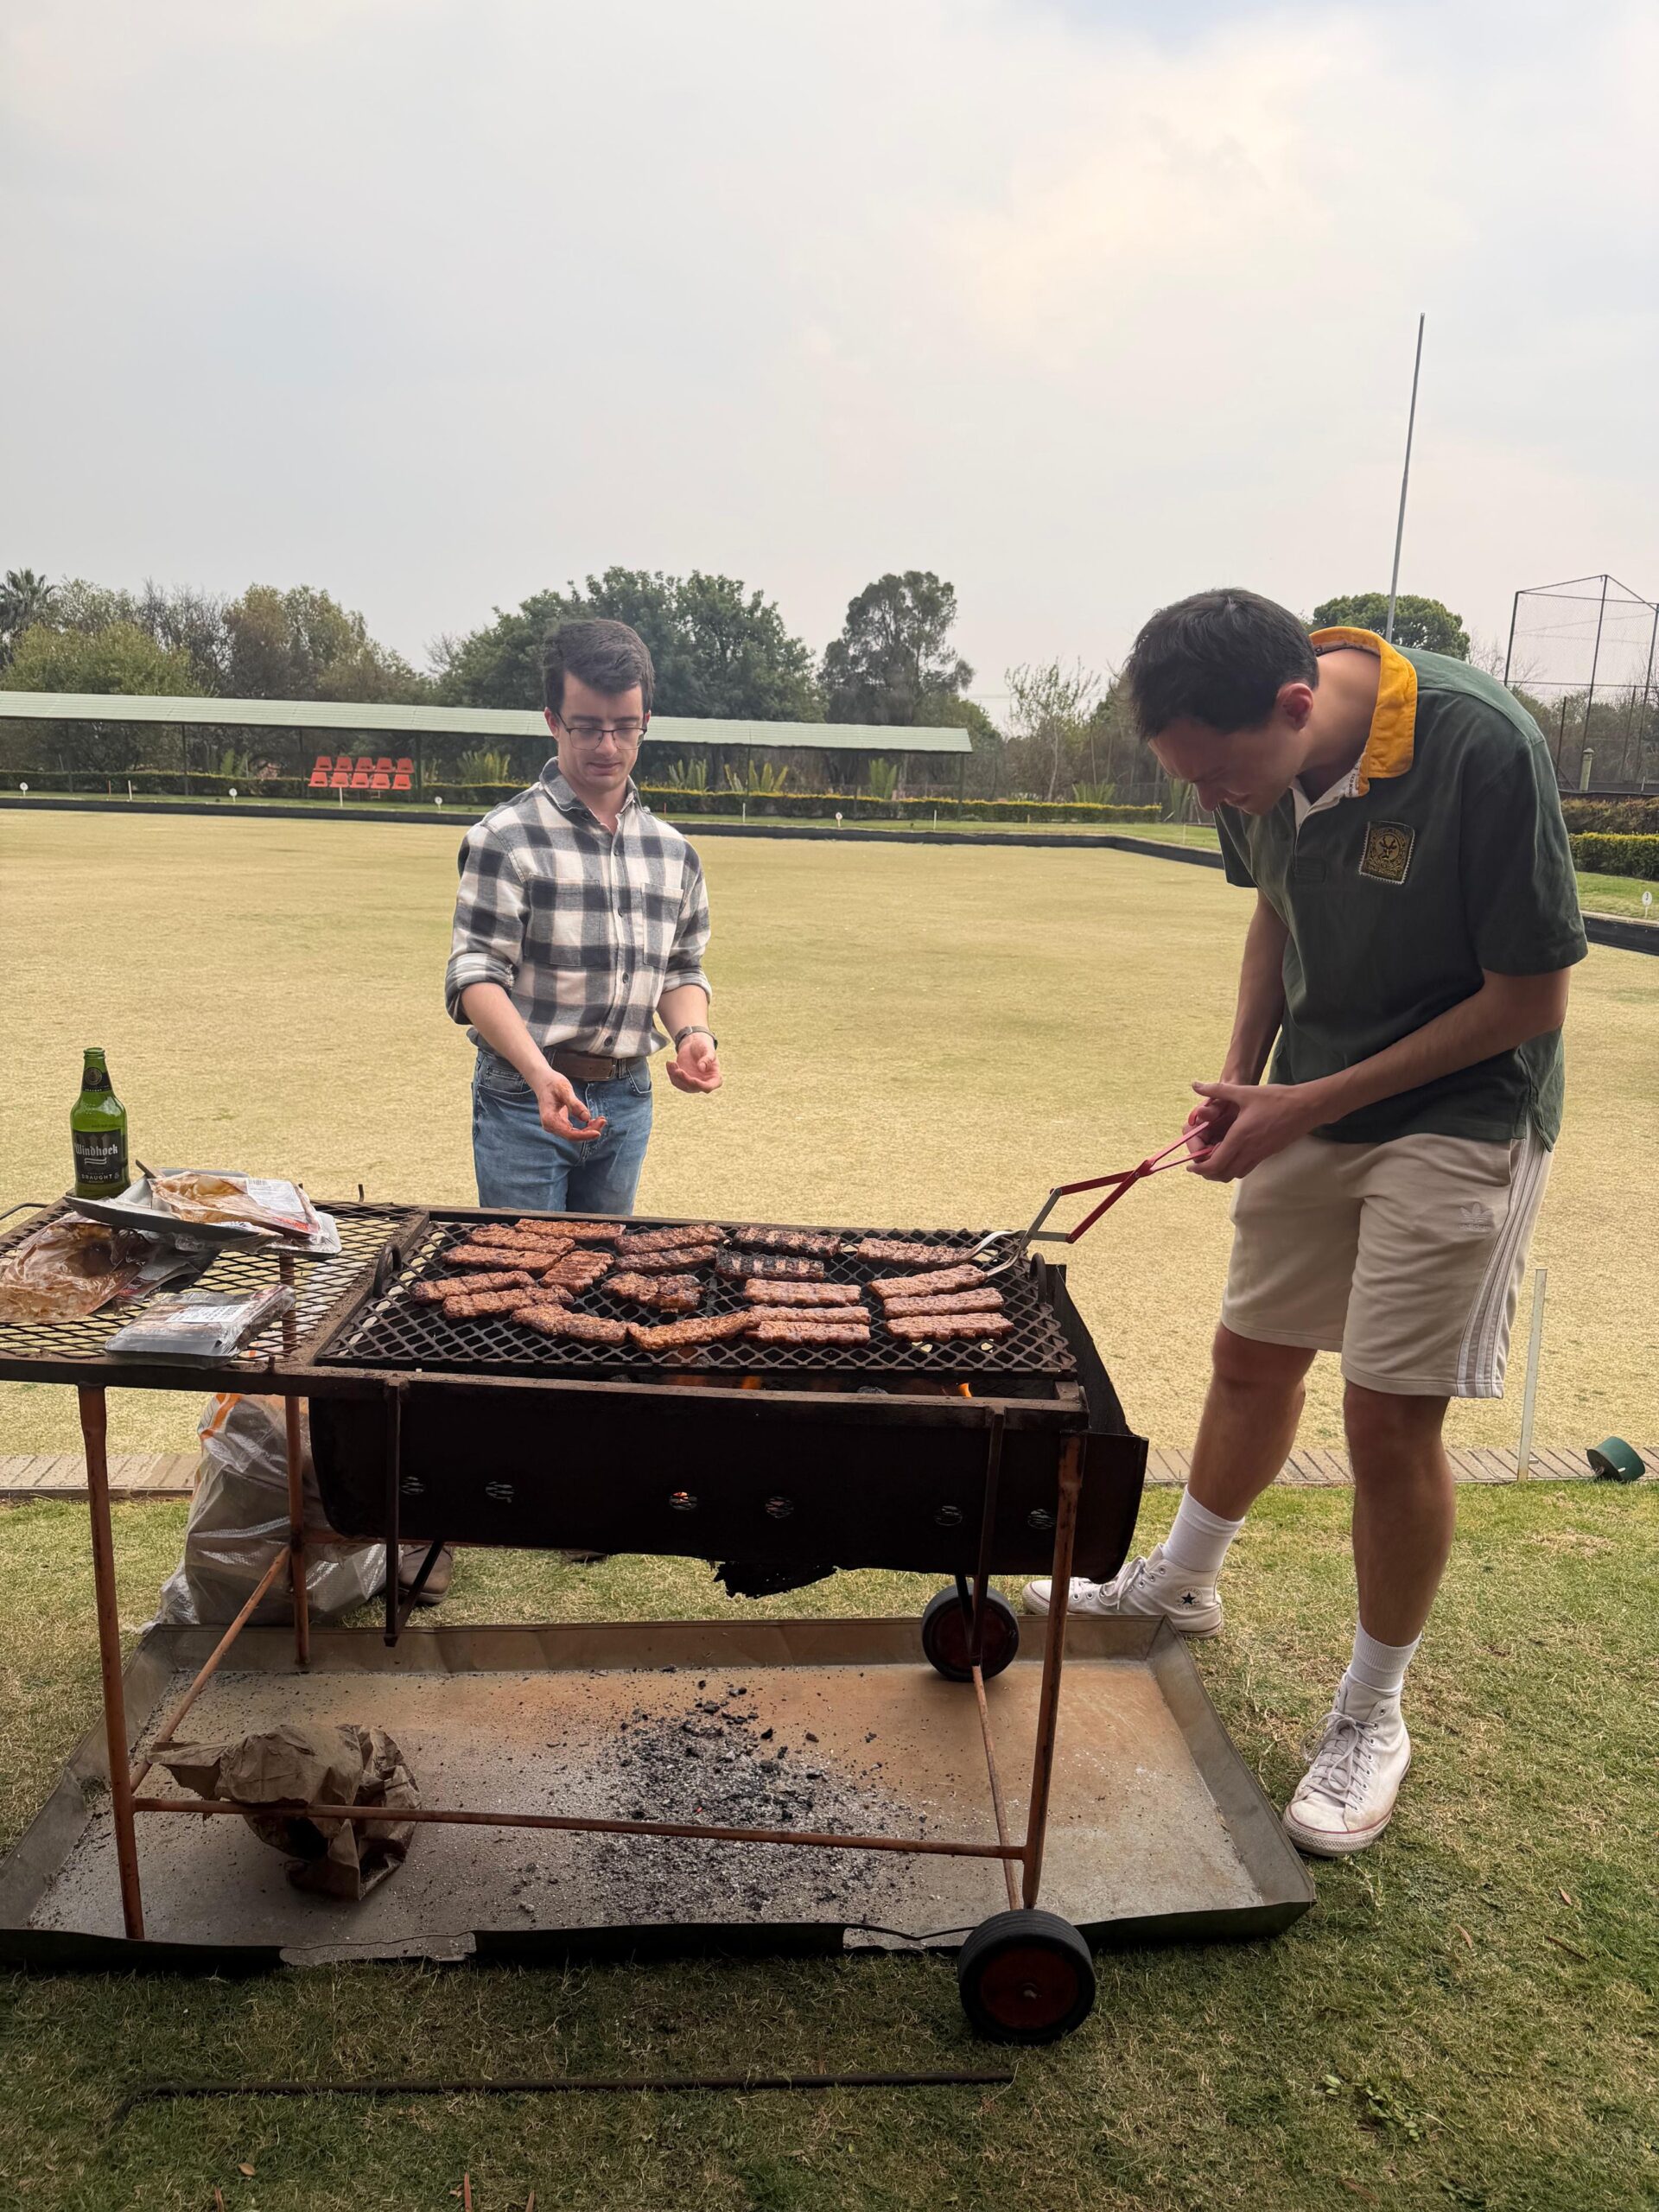
Of course, it wouldn’t be a proper Logista get-together without a good old-fashioned South African braai! Between the bowls, delicious food and plenty of catching up, the day was the perfect opportunity to put work aside, unwind and simply enjoy each other’s company.It’s these moments that remind us that being part of a great team is about more than what we achieve together at work. It’s also about the friendships we build, the laughter we share and the memories we create along the way.

A big thank you to everyone who joined in, dressed up and helped make the day such a memorable one!

The Fun Isn’t Over Yet!

There’s still plenty to look forward to on the Logista social calendar as we head towards the end of 2026!

  • 16 October | Coming Together for a Good Cause
    We’re putting our team spirit to good use by taking part in a charity event. It’s a wonderful opportunity to give back and make a positive difference.
  • 20 November | Let’s Celebrate!
    Our much-anticipated Year-End Function is just around the corner! It’s time to celebrate another year of hard work, shared successes and the people who make it all happen.
  • 15 December | One Last Braai!
    Before we say goodbye to 2026, we’ll fire up the coals one last time for our final braai of the year. A chance to relax, share a few laughs and enjoy some festive cheer together.

Here’s to the people behind Logista, the moments that bring us together and many more reasons to celebrate!

SARS Scams and eFiling Profile Hijacking: Taxpayers Beware

SARS Scams and eFiling Profile Hijacking: Taxpayers Beware

All role players must play their part to prevent criminals from accessing taxpayers’ information.

We are receiving more and more complaints, often from highly-distressed taxpayers, who are forwarding emails, SMSs and WhatsApp messages that appear to be from SARS, but are in fact scams. Increasingly convincing, these messages are causing unnecessary distress and raising the risk of being scammed. Here’s a timely Cybersecurity Awareness Month refresher on how to spot a SARS scam and what to do if you receive one. Our top suggestion? Simply check in with our team for peace of mind.

Every day, too many taxpayers fall victim to convincing scams that use SARS’ name to steal personal information and money. Cybersecurity Awareness Month (every October) raises awareness about digital security, empowering South Africans to protect their personal data from digital forms of crime. It’s a good time to revisit the growing threat of SARS scams and eFiling profile hijackings.

Common SARS scam types

  • Phishing emails: Members of the public randomly receive false ‘spoofed’ emails, made to look as if they were sent from SARS, but which are fraudulent. Examples include emails appearing to be from returns@sars.co.za or refunds@sars.co.za, indicating that taxpayers are eligible to receive tax refunds. These emails contain links to false forms and fake websites designed to look like SARS sites, with the aim of fooling taxpayers into entering personal information such as bank account details, which criminals then extract and use fraudulently.
  • Fake SMS messages: SARS does not send *.htm or *.html attachments. Any SMS claiming to be from SARS with such attachments is fraudulent.
  • Fake WhatsApp messages: SARS will not provide links to be opened or SARS bank account details for payments on a WhatsApp message.
  • eFiling profile hijacking: Criminals gain access to taxpayers’ eFiling profiles, change banking details, and divert refunds.

What SARS will and won’t do

SARS will:
✓Verify your personal details for telephonic engagement and authentication purposes
✓Communicate through official SARS channels only
✓Direct you to check your SARS profile on eFiling or the SARS MobiApp for legitimate debts
SARS won’t:
✗Request passwords, one-time pins (OTPs), banking PINs or eFiling login credentials through email, SMS, social media or telephone
✗Request your banking details in any communication via post, email or SMS (but SARS will verify your personal details for telephonic authentication)
✗Send hyperlinks to other websites, even those of banks
✗Ask for your credit card details
✗Send *.htm or *.html attachments
✗Provide a SARS bank account number for payments
✗Ask you to click any link to access its website or services


What to do if you suspect a scam 

Do not respond to communications that you suspect to be a scam. Simply contact us and let us provide certainty.

We will check whether the message is part of an official SARS communication campaign or if it’s a known scam message currently in circulation. If it’s a new scam, we can report it to the right authorities. Before you share personal information or make any payments, we can verify the communication through official SARS channels. For example, if the communication pertains to outstanding debt, we can verify this directly on SARS platforms, as any legitimate debt will reflect on your SARS profile.

How to stay safe beyond Cybersecurity Month 

  • Do not open or respond to emails from unknown sources
  • Be suspicious if a message asks for personal information or creates urgency
  • Never share confidential details with unauthorised individuals
  • Never click on any link to access SARS’ website or SARS services or to verify an account
  • Only use secure internet platforms to access electronic services such as eFiling
  • Enable two-factor authentication on eFiling profiles
  • Use strong, unique passwords and change these regularly

SARS scams are becoming more sophisticated, but the rules for spotting them remain unchanged. When in doubt, and before taking any action, contact us.

Win the War for Talent Without Paying Enterprise-Level Salaries

Win the War for Talent Without Paying Enterprise-Level Salaries

Recognise flexibility as a selling point. Generally speaking, top talent wants the option to crunch numbers at a coffee shop or stay in their slippers at home.

Small businesses can't match the paychecks that big corporations dangle in front of job candidates, but they don't always have to. There are many different ways to entice the best candidates that money can’t buy and which smaller employers are uniquely positioned to activate. This article gives eight practical, low-cost strategies owners can use to attract and keep great people.

Every small business owner knows the feeling: a promising candidate sails through the interview process, everyone loves them … And then a bigger company swoops in with a salary offer that simply can’t be matched.

It’s easy to assume the fight for talent is over before it starts. But compensation is only one variable in a much larger equation. In addition to cold hard cash, candidates today are looking for flexibility, growth potential, purpose, and how much their work actually matters. These are all areas where lean, close-knit companies often outperform corporate giants. Business advisors, HR experts, and small-business owners increasingly agree: the “war for talent” isn’t only won with bigger paychecks. It’s won by understanding what employees genuinely value and building an offer around it. Here are our 8 tips.

1. Lead with flexibility

Flexible work arrangements have become one of the most powerful, low-cost tools available to small employers. Staffing firm Spherion notes that many candidates weigh flexibility and growth opportunities just as heavily as salary, and that smaller companies tend to have far more room to build compelling offers around said flexibility. Data backs this up: research from the Harvard Business School found that a significant proportion of employees would accept a pay cut just to keep their remote work arrangement.

2. Make company culture your differentiator

Culture is a genuine competitive advantage for small teams. As staffing firm Beacon Hill notes, many professionals actually prefer working at smaller companies where they can see the direct impact of their work. Business owners who can’t win on salary may still win by offering something large employers structurally can’t: proximity to leadership, visibility, and a relaxed work-life balance. Small companies should lean into this rather than apologise for their size. Job postings, interviews, and onboarding should all reflect the authentic, non-corporate environment.

3. Prioritise cultural fit as much as skill

Hiring for the right personality can matter more than choosing the candidate with the most impressive CV. PureWow CEO Ryan Harwood has said he’d rather bring on someone slightly less talented who fits the culture perfectly than someone highly talented who doesn’t mesh with the team. For small businesses, where every hire has an outsized impact on daily operations, getting the right fit is doubly important.

4. Invest in growth and development

Career growth is one of the most persuasive, and least expensive, tools a small business has. The Small Business Association of Michigan points to LinkedIn’s Workplace Learning Report, which found that 94% of employees said they would stay at a company longer if it invested in their career development. Mentorship, cross-training, and covering the cost of a certification or course all send the same message: this company is invested in where you’re headed, not just what you can do for it today.

5. Recognise and reward often, informally and formally

Recognition costs a little and matters a lot. The Small Business Association of Michigan also recommends building in low- or no-cost perks. A relaxed dress code, team activities, a pet-friendly workplace, alongside regular recognition programs and small rewards to boost morale are all great ideas. Because small teams are more visible to leadership day-to-day, recognition can be personal and immediate rather than buried in an annual review cycle. A spontaneous gesture from the boss is often more meaningful to employees than the corporate version of the same action.

6. Move fast and communicate clearly during hiring

Large companies are often slowed down by layers of approval. Small businesses can turn speed into a selling point. Business.com points out that while a small business likely can’t offer the highest salaries in its market, it can offer the fastest hiring process. On top of speed, simple communication matters. Saïd Eastman, of JobsInTheUS.com, highlights how something as small as an automatic application confirmation, or a real phone number candidates can call with questions, signals respect for applicants’ time, and sets a small business apart.

7. Build the whole compensation picture, not just the base salary

Salary is only one line item in total compensation. HireHive’s guidance for small employers stresses looking at the entire compensation package, including health insurance, retirement contributions, flexible time off, and remote-work stipends. This can meaningfully close the gap between a small business’s offer and a larger competitor’s, without requiring the same payroll spend. That’s not to say salary isn’t important: the number you offer has to be realistic, of course.

8. Treat staffing as flexible, not fixed

Not every role needs to be a full-time hire on day one. Robert Half’s research into small-business staffing points back to management theorist Charles Handy’s “shamrock organization” model, blending core full-time staff with contractors and outsourced specialists, as a way to access skilled talent without committing to enterprise-level headcount costs. This approach lets small businesses bring in specialised expertise for a project or busy season, then scale back down, all while keeping the core team lean and well cared for.
The Exit You Might Not Have Considered: Selling Your Company to Your Employees

The Exit You Might Not Have Considered: Selling Your Company to Your Employees

I've never been a guy who's just about getting a check, so I thought: is there a way we can keep this going, and bring others along for the ride?

For South African business owners, selling to your employees can offer something a traditional buyer often cannot: a lasting legacy. Through employee share ownership schemes, broad-based trusts and B-BBEE ownership structures, founders can reward loyal staff, preserve their company's culture and create a structured exit. Success, however, depends on getting the financial, tax and legal foundations right. Here’s how to do it.

When entrepreneurs imagine an exit, they usually picture three doors: a trade sale, a private-equity deal, or a family handover. Yet there is a fourth route that is often less discussed and, for the right company, more emotionally and strategically satisfying: selling the business to the people who already know it best. When properly structured, employee ownership is a succession strategy that can deliver liquidity to the founders, stability to the staff and continuity to the customers.
Beyond the obvious buyer

For many owners, employee sales may work because they offer benefits more traditional sales do not. External bidders may promise a premium, but they can also bring integration risks, redundancies, culture changes and potentially even the wholesale dismantling of what made the company valuable in the first place. Selling to your employees, on the other hand, may offer a route towards preserving the enterprise, rewarding the workforce and allowing you to retire without feeling like you’ve sold the soul of the business.

Is it even possible?

In a conventional business sale, accountants are commonly responsible for preparing financial statements, supporting due diligence and calculating the tax implications of the transaction. An employee ownership transaction requires a much broader advisory role. The first question your accountant (that’s us) must help you answer is the vital question of what the company is worth, and just how employees might be able to purchase it. Valuation may draw on normalising earnings, cash flow forecasts, comparable market multiples, the asset base and the particular risks of the business and ensuring accurate financial reporting. This will give you a clearer understanding of what the business is worth and whether the proposed transaction is financially sustainable. Where employees do not have the capital to purchase a business outright, it becomes important to evaluate the options available to finance the purchase as this will impact the viability of the transaction.

How to make it happen

Once you’ve established that selling to your employees is possible, you need to decide which route to take. In South Africa, there are many different ways of doing it. Employees may acquire shares directly, either individually or through an acquisition vehicle. Some employee ownership arrangements may be structured to hold shares collectively on behalf of employees, often through a trust or another ownership vehicle. B-BBEE objectives can also be incorporated into an employee ownership arrangement. There are many different ways to skin this cat. Each option carries different tax, governance and funding implications that change based on your company’s unique situation. Taking into account your wishes, and the financial landscape of the business, your accountant can determine exactly which of these methods is most viable.

Other considerations

Another thing which may impact the decision-making process is how taxation could be applied. Depending on how the deal is structured, founders may become liable for Capital Gains Tax on the disposal of their shares, while employees could face income tax implications if shares are acquired below market value or through certain incentive arrangements. Trusts, debt-funded acquisitions and phased ownership transfers can all influence the overall tax outcome, making early advice essential. As your accountants, we can model different scenarios, identify potential tax efficiencies and ensure the transaction complies with the requirements of the Income Tax Act while avoiding costly surprises for both buyer and seller.

The bottom line

Selling to employees is rarely the quickest or simplest exit. It demands careful structuring, realistic valuations, appropriate funding arrangements and ongoing governance. But for founders who value continuity as much as financial return, it can provide one of the most meaningful succession strategies out there.

SUBSCRIBE TO RECEIVE
OUR NEWSLETTERS